

Benefits OnLine
3.5FinanceUpdated October 5, 2026
Screenshots
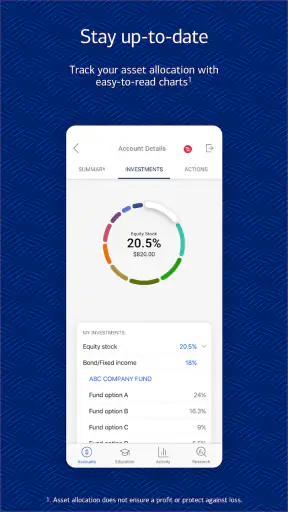
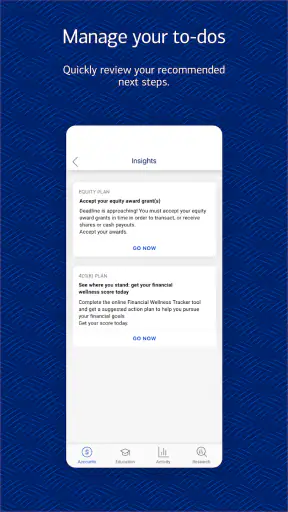
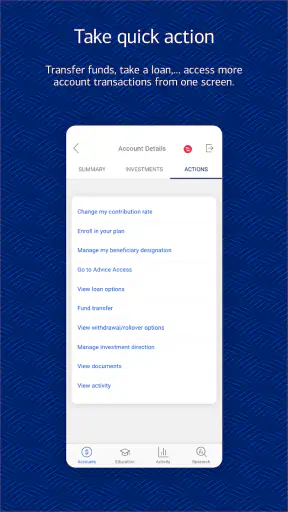
Pros
- Centralizes employee benefits
- discounts
- and wellness resources in one app.
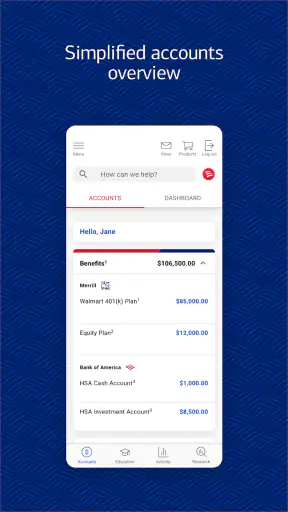
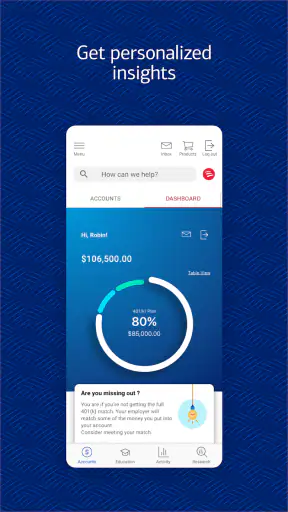
- Personalized access helps users find benefits relevant to their employer and plan.
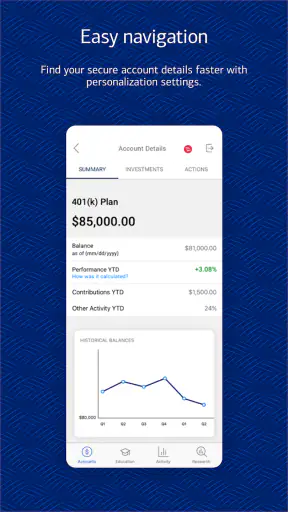
- Useful tools can make it easier to track activities and rewards.
- Mobile access lets users review benefits without visiting a desktop portal.
- May include educational content to support healthier financial and lifestyle choices.
Cons
- Available features depend heavily on the employer’s benefits program.
- Some sections may require separate logins or additional account verification.
- Information can become outdated if an employer does not update its offerings.
- The interface may feel crowded when many benefit categories are enabled.
- Certain rewards or discounts may have eligibility limits and expiration dates.
 Analysis By Mobexer
Benefits OnLine is a finance app for people who manage retirement and workplace benefit information through Merrill Lynch, Pierce, Fenner, and Smith Inc. I found its purpose fairly clear: it is not a general budgeting tool or a complete replacement for a bank app, but a focused place to check and work with benefits connected to an employer plan. That narrow role is also the key to deciding whether it belongs on your phone.
The app is free, carries an Everyone age rating, and has passed the one-million-install mark. Its average rating is 3.5 from roughly 3,400 ratings, with about 1,100 written reviews. Those figures suggest a useful but uneven experience: plenty of people can get value from it, while others are likely running into account access, plan-specific, or device-related friction rather than judging it as a polished everyday money manager.
Where the experience usually gets stuck
The first thing I would tell a friend is not to treat Benefits OnLine like a finance app that works immediately after installation. Its usefulness depends on whether your employer or retirement arrangement is supported and whether your login details match the information held for that plan. Installing it is only the beginning; the important step is connecting the app to the right benefits account.
That distinction explains a common source of disappointment. Someone may download it expecting to browse retirement options, only to discover that the app is mainly a secure doorway into information already associated with a workplace account. If you do not have an eligible plan, or if your employer uses a different benefits administrator, the application will not become useful simply because it is installed.
I also found that sign-in problems can look more mysterious than they really are. A rejected login may come from using credentials for another Merrill service, entering an old workplace username, or selecting the wrong account path. Before repeatedly trying the same password, I would check whether the account is specifically tied to Benefits OnLine and whether your employer recently changed its benefits portal or enrollment process.
The most important practical lesson is to separate account access from app performance. If the application opens normally but refuses to show your plan, the problem may be account eligibility or an incomplete employer setup. If the app closes, freezes, or behaves strangely before you reach sign-in, the phone or app installation becomes a more likely suspect.
Another point worth understanding is that retirement information can feel slower and less immediate than a checking-account balance. A workplace contribution, enrollment change, or beneficiary update may depend on processing outside the app. I would not assume that a screen failing to change instantly means the action was lost, and I would avoid repeating a submission until I had checked whether it was already accepted.
What I would check before blaming the app
My first check would be the exact account route supplied by the employer. Benefits platforms often have similar names, and a familiar Merrill login does not automatically prove that it is the correct one for this service. I would also confirm that the plan is still active through the current employer, especially after changing jobs, moving between benefit programs, or returning from leave.
Next, I would review the phone itself. The current version is 26.08.02 and the minimum operating-system requirement is 11, so an older device system can prevent a smooth installation or leave the app behaving unpredictably. Updating the operating system is not always convenient, but it is a sensible first step when the phone is below that requirement or has pending system updates.
I would then install the latest available app update through the normal store process and restart the phone. This is basic advice, but it matters more for a secure finance application than for a casual game: a partially completed update, low storage, or a background process stuck during installation can create problems that look like failed authentication.
For connection issues, I would test a reliable Wi-Fi connection and then, if appropriate, a mobile connection. A benefits app may load a sign-in screen while still failing when it tries to retrieve account information. If one network works and the other does not, that points toward connectivity or network filtering rather than incorrect account details.
I would also check the phone’s date and time settings. Secure sign-in systems can react badly when the device clock is substantially wrong. Keeping automatic date and time enabled is a small setup detail, but it is one of those checks that can save a great deal of unnecessary password resetting.
Finally, I would make sure the app was installed from the official app marketplace and that the developer shown there is Merrill Lynch, Pierce, Fenner, and Smith Inc. That check is especially important for financial software. I would never enter retirement credentials into an unofficial copy, a page reached through an unexpected message, or a form that does not clearly belong to the normal sign-in flow.
A safer setup routine
My preferred setup sequence is deliberately slow. I would install the app, confirm the developer, open it on a stable connection, and use the credentials associated with the workplace benefits account rather than guessing from another Merrill product. I would keep the phone’s operating system current and avoid switching repeatedly between several account-recovery attempts.
If the app asks for information I do not recognize, I would stop and verify the request through an official employer benefits channel. That is not a sign that the app is necessarily unsafe; it is simply the right habit for retirement information. A rushed setup can lead to locked access, duplicate recovery attempts, or confusion about which account is actually being repaired.
I would also keep a note of the exact message shown on screen. “Incorrect credentials,” “account unavailable,” and “page cannot load” point to different next steps. Recording the wording, the time, and whether the failure happened on Wi-Fi or mobile data makes any later conversation with employer support much more efficient.
One useful trade-off is convenience versus control. If the app offers a faster sign-in method on your device, it may make routine checks easier, but I would only enable it after the main account works and the phone itself is protected with a reliable screen lock. Retirement access is not the place to optimize for speed before confirming the basics.
Recovering a stalled workflow
Once access works, I would use Benefits OnLine for short, deliberate sessions rather than treating it as a financial dashboard that needs constant attention. A practical routine might be checking plan information after a paycheck, reviewing a change made during enrollment, or confirming that a retirement-related request appears to have moved forward.
When a page seems stuck, I would first wait briefly and avoid tapping the same action several times. Repeated taps are especially risky around submissions or changes because the screen may be slow while the service is processing the first request. If the app remains unresponsive, I would close it normally, reopen it, and check whether the account reflects the action before trying again.
If the app returns to the sign-in screen, I would treat that as a session problem rather than immediately assuming that my account has disappeared. Reopening the app and signing in once more may restore the workflow. If the same loop continues, I would capture the message and contact the appropriate plan or employer support route instead of repeatedly changing credentials.
Clearing local app data or reinstalling can sometimes help with a damaged installation, but I would use that step carefully with a finance app. I would only do it after confirming that I know the correct login details and recovery method. Reinstallation may remove local convenience settings, and it does not repair an employer-side account issue.
A particularly useful recovery habit is to distinguish information viewing from account changes. If a balance or plan page fails to load, retrying later may be reasonable. If you were changing an election, updating personal information, or submitting another consequential request, I would verify the result through the account history or an official support channel before submitting anything again.
This is where the app’s focused design can work in its favor. It is less distracting than combining retirement tasks with spending categories, credit cards, and shopping alerts in a general-purpose money app. I can approach it with one question in mind and leave when that question is answered. The downside is that it may feel limited if I want a full picture of household finances in the same place.
When the phone is not the real problem
Benefits OnLine sits between your device and a workplace benefits system, so not every failure can be repaired from the phone. Maintenance, employer enrollment changes, an unrecognized plan, delayed processing, or an account lock can all produce an experience that looks like an app defect.
This matters when other parts of the phone work normally. If websites load, other secure apps open, and the Benefits OnLine sign-in screen appears, I would not begin by resetting the entire device. I would first verify the plan, account status, and employer instructions. A device reset is disruptive and rarely the sensible response to a benefits record that has not been activated correctly.
The same reasoning applies to missing or outdated information. A retirement record may depend on payroll, enrollment, or administrative processing outside the mobile interface. I would compare the timing of the expected update with any confirmation received through the employer and ask the plan administrator for clarification if the information remains inconsistent.
For security, I would never send a full password, security answer, or sensitive retirement details through an informal message while asking for help. The safest support conversation starts with the error wording and general account context, not with handing over credentials. If a message pressures me to bypass the normal sign-in process, I would treat that as a warning sign.
Who will find it worthwhile
I think this app makes the most sense for employees and former employees whose retirement or benefit arrangements are administered through Merrill Lynch, Pierce, Fenner, and Smith Inc. It is also a good fit for someone who wants a dedicated mobile view of workplace benefits instead of relying on a desktop browser every time a plan question comes up.
Its value is practical rather than broad. If I only need to check plan-related information occasionally, having a focused app can reduce the effort of finding the right portal. It is particularly handy in an everyday situation such as reviewing a paycheck contribution, checking a benefits change after an enrollment period, or confirming that I am looking at the correct workplace account before contacting support.
I would skip it if I am looking for expense tracking, bill reminders, a complete household budget, or a universal investment dashboard. A general finance app is better for combining bank accounts and spending habits, while the employer’s official web or support channel may be better when I need detailed plan explanations or administrative action.
I would also hesitate to rely on it as my only record for important retirement decisions. The app can be a convenient access point, but serious choices deserve careful reading of the plan information and, where needed, direct clarification from the employer or plan administrator. Convenience should support judgment, not replace it.
How it compares with the usual alternatives
Compared with a general budgeting app, Benefits OnLine is narrower but more relevant when the question concerns a workplace retirement or benefit account. Budgeting tools usually excel at spending visibility and household organization; they are not designed to be the authoritative place for employer-plan details. Using one instead of this app could leave me with a neat financial overview but no direct connection to the benefit information I actually need.
Compared with a mobile browser, the dedicated app should be more convenient for repeated access because it gives the task its own place on the phone. The browser may still be preferable when I need a wider page, more complete administrative navigation, or a desktop-sized view. I would keep the browser option in mind whenever the mobile workflow feels cramped or a page repeatedly fails inside the app.
Compared with calling support, the app is faster for routine checks and less disruptive when I only need to look at information. Support remains the stronger option for account ownership questions, plan eligibility, delayed updates, or actions whose status is unclear. The best approach is not to choose one permanently: use the app for visibility and a verified support route for issues that depend on records outside the phone.
My practical verdict
After using Benefits OnLine as a focused benefits tool, I see it as useful for the right audience rather than universally essential. The free price removes an obvious barrier, and the Everyone rating makes it broadly approachable, but neither fact changes the central requirement: you need an eligible workplace or retirement relationship behind the login.
The app’s strongest quality is its purpose. It keeps retirement and benefit access separate from everyday spending, which can make a quick check easier and less distracting. Its weakest point is the dependency on account setup and employer-side systems. When something goes wrong, the visible app is not always the part that needs fixing.
My advice is to install it if your employer directs you to Benefits OnLine, confirm the developer and operating-system requirement, and complete the first sign-in patiently. Keep the exact error message if access fails, verify whether an action already processed before repeating it, and use official plan support when the issue concerns eligibility or account records.
With those expectations, Benefits OnLine is a sensible companion for checking workplace benefits on a phone. I would recommend it to eligible plan participants who want convenient access, but not to someone searching for a full personal-finance manager. Its rating of 3.5 feels consistent with that balanced conclusion: useful in its intended lane, yet dependent on a setup and support experience that may not always feel effortless.
FAQ
What is Benefits OnLine and what can I use it for?
Benefits OnLine is a mobile platform designed to help eligible users access and manage information about their employee benefits. Depending on the organization providing access, the app may let you review plan details, check balances, view available resources, access important documents, and find contact information for support. The exact tools can vary, so the experience depends on your employer, plan administrator, or benefits provider.
Who can use the Benefits OnLine app?
Access to Benefits OnLine is generally limited to people whose employer, financial institution, or benefits administrator supports the service. You may need an active account, participant number, username, or registration code before signing in. Downloading the app alone does not guarantee access. If you are unsure whether you are eligible, check the enrollment information supplied by your organization or contact the benefits administrator directly.
How do I sign in or recover my Benefits OnLine account?
After installing Benefits OnLine, users typically sign in with credentials connected to their benefits account. New users may need to complete a registration process before they can access personal information. If you forget your password or username, use the recovery option shown on the login screen and follow the verification steps. For locked accounts, failed verification, or registration problems, official support may be required.
Is my personal and benefits information secure in Benefits OnLine?
Benefits OnLine is intended to protect sensitive account and benefits information through standard security measures such as account authentication, encrypted connections, and session controls. However, users should still take precautions by installing the app only from an official store, keeping the operating system updated, avoiding public Wi-Fi for sensitive activity, and never sharing passwords or verification codes. Enable device security whenever possible.
What should I do if a benefit, balance, or document appears to be missing?
If information is not displayed correctly, first confirm that you are using the correct account and that your benefits enrollment or account update has already taken effect. Some changes can take time to appear in the app, particularly after enrollment, employment changes, or administrative updates. Try refreshing the app and checking again. If the issue continues, contact your employer or plan administrator because they control the underlying benefit records.











