

Avant
4.7FinanceUpdated October 5, 2026
Screenshots
Pros
- Clean
- modern interface that is easy to navigate
- Useful tools are organized logically for quick access
- Runs smoothly on compatible Android and iOS devices
- Helpful for users who want a focused
- straightforward experience
- Regular updates can improve stability and add useful refinements
Cons
- Some features may require a subscription or in-app purchase
- The app may feel limited for users seeking advanced customization
- Performance can vary on older or less powerful devices
- Certain functions may depend on an active internet connection
- Privacy details and permissions should be reviewed before signing up
 Analysis By Mobexer
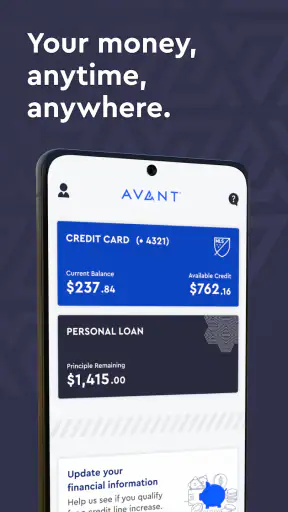
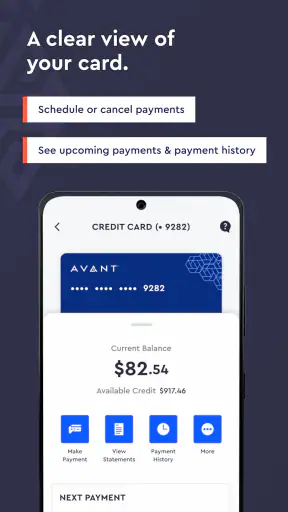
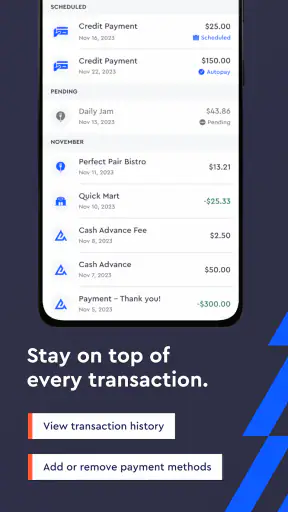
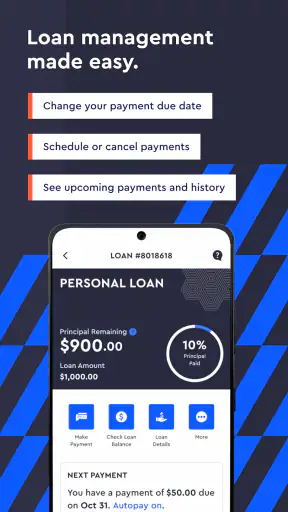
I approached Avant as a practical finance companion rather than a full replacement for a bank’s mobile app. Its purpose is straightforward: help card or loan customers make payments, review transactions, and keep an eye on their Avant account from a phone. After using it, my impression is that the app is most useful when you already have an Avant financial product and want a quicker way to handle routine account tasks without reaching for a browser.
That focus matters. Avant, LLC has built this as a customer-management tool, not as a budgeting platform, investment service, or general-purpose money manager. I would recommend it to someone who wants a simple view of their Avant activity and an easier payment routine. I would not choose it for detailed household budgeting, tracking several unrelated banks, or analyzing spending across multiple cards.
How the current Avant experience feels
The app sits in the finance category and is free to install, with an Everyone content rating. Its audience is fairly clear: people managing an Avant card or loan who would rather complete common tasks on a phone. The interface is at its best when I use it for a short visit—checking recent activity, confirming that a payment was made, or opening the account before deciding what needs attention.
That narrow purpose gives the experience a useful sense of direction. I do not have to sort through investment charts, promotional shopping areas, or unrelated financial tools before getting to account information. For an existing customer, that can be more valuable than a feature-heavy app that tries to do everything. The trade-off is that the app does not feel designed to become the central command center for every part of personal finance.
Avant has reached over 500 thousand installs and holds a 4.7 average from around 58 thousand ratings. Those figures suggest that the basic mobile-account workflow has found a substantial audience, although they should not be treated as proof that every customer will have the same experience. A payment app can feel excellent when the account is straightforward and less convenient when a user needs unusual support or more detailed financial planning.
In everyday use, I found the strongest reason to keep it installed is convenience between billing moments. Suppose I am about to make a purchase and want to check recent card activity first. Opening the app is more direct than logging into a desktop site. Later, when I am ready to pay, I can return to the same place instead of searching through email or paperwork for account details. That small reduction in friction is exactly where the app earns its place.
A sensible fit for card and loan customers
The app is especially suitable for someone who prefers handling financial chores in brief sessions. A user can open it with a specific question in mind: What transactions have appeared? Did my payment go through? What does my Avant account currently show? The value comes from answering those questions quickly, not from turning a few minutes of account maintenance into a long planning exercise.
It can also help users create a more reliable payment habit. I would use a repeatable routine: open the account after payday, review activity for anything unfamiliar, check the amount due, and complete the payment if needed. The important insight is that transaction review should happen before payment, not after it. That order makes it easier to notice a purchase that needs attention before treating the displayed balance as final.
For a loan customer, the same routine has a different purpose. Rather than watching card purchases, the app becomes a place to review the account and keep payments organized. I would still treat it as an account-access tool, not as a complete debt-reduction planner. Anyone trying to compare payoff strategies across several loans will probably need a separate spreadsheet or budgeting app alongside Avant.
The app is also a reasonable choice for people who dislike managing accounts through a mobile browser. A browser can work, but a dedicated app is usually easier to reach and more comfortable for a quick check. On the other hand, if you rarely use your Avant account or prefer doing all financial tasks on a computer, installing another app may not add much value.
What the version information tells existing users
The current version is 4.7.0, while the app was released on February 11, 2020. That combination tells me this is an established product rather than a brand-new experiment. It has had time to become a recognizable part of the Avant account experience, and the version number indicates an ongoing product line rather than a one-off utility.
I would be careful, however, not to read a version number as a promise of a particular feature. A later version can reflect maintenance, refinements, compatibility work, or changes that are not obvious during a short visit. What I can say from the current experience is that the app remains centered on payments, transactions, and account management. I would not install it expecting a dramatic shift into a different type of finance product.
For existing users, the practical effect of keeping the app updated is less about chasing novelty and more about preserving a dependable account workflow. When a finance app is used for payments, stability matters more than flashy additions. I would update it through the normal app-store process, then open the account and verify that the familiar tasks are still easy to find before relying on it for a time-sensitive payment.
There is also a useful distinction between product evolution and personal expectations. The app may become smoother over time, but that does not mean it will suddenly provide the deep spending categories or cross-bank overview found in dedicated budgeting tools. Existing users should judge each update by whether it makes their actual routine—checking activity and managing payments—clearer and less error-prone.
Small workflows that make it more useful
My first practical tip is to separate “checking” from “acting.” I would open the transaction view and scan recent activity before starting a payment. This is a simple habit, but it prevents the common mistake of making a payment based on an incomplete understanding of what has posted or what has already been handled.
My second tip is to use the app as a confirmation point, not merely a payment button. After completing a payment, I would return to the account and look for the resulting status or transaction information. That extra moment is worthwhile because it gives me a clearer record of what the account is showing. I would not assume that tapping a button alone is enough evidence that the task is complete.
A third useful workflow is to check the account before making a larger planned purchase. If the app shows recent activity and account information in one place, I can make a more informed decision about whether the purchase fits my current obligations. This is not the same as a budgeting forecast, but it is a practical checkpoint that many people skip when they rely only on memory.
I also like the idea of using a consistent weekly review rather than opening the app only when something feels wrong. A short review can cover recent transactions, payment status, and any account detail that deserves attention. The benefit is not sophisticated analysis; it is reducing surprises. For a card user, this habit can make unfamiliar activity easier to notice. For a loan user, it can make payment management feel less reactive.
One limitation of these workflows is that they depend on the user interpreting account information carefully. The app can put the details within reach, but it cannot replace judgment about affordability, debt priorities, or suspicious activity. If something looks incorrect, I would treat the app as the place where I noticed the issue, not necessarily the complete solution to it.
Where it differs from common alternatives
Compared with using a mobile browser, the Avant app feels more appropriate for frequent short checks. A browser is flexible and may be preferable when I am already working on a computer, but an installed app removes some of the steps between picking up the phone and reaching the account. That convenience is its clearest advantage over the usual browser alternative.
Compared with a general budgeting app, Avant is much narrower. Budgeting tools often focus on categories, spending trends, goals, and accounts from different providers. Avant is better when the question is specifically about an Avant card or loan. If I want to understand my entire household’s cash flow, I would choose a broader finance tool and use this app as the account-specific companion.
Compared with a bank app, the comparison depends on what I need to do. A bank app may offer a wider view of checking, savings, transfers, and other products. Avant is more focused on its own card and loan relationship. That focus can make it less cluttered for the relevant task, but it also means I should not expect it to provide the same breadth as an app built around full-service banking.
The most important trade-off is therefore focus versus coverage. I prefer Avant when I want direct access to Avant account activity. I prefer another option when I need consolidated finances, detailed analysis, or a broader set of money-management tools. Installing both can make sense, but they serve different jobs rather than replacing one another.
Friction points and remaining gaps
The main limitation is scope. Someone looking for a complete financial dashboard may quickly outgrow the experience because payments and transactions are the center of attention. There is nothing wrong with that design choice, but it should shape expectations before downloading. The app is not the right pick simply because it belongs to the finance category; it is the right pick when the user has an Avant account to manage.
I would also avoid treating it as a substitute for personal records. For important financial decisions, I still prefer keeping my own payment calendar and reviewing statements or account documentation when necessary. A mobile view is convenient, but convenience can encourage quick glances instead of careful review. The app works best when it supports a responsible routine rather than becoming the only place I think about money.
Another possible source of friction is the difference between a straightforward account and an unusual situation. Routine payment management is a good match for a focused app. A complicated dispute, a question requiring detailed explanation, or a situation involving several financial products may call for direct customer support or a larger-screen review. I would not measure the app only by how quickly it handles normal days; the harder cases matter too.
Users should also remember that a free download does not mean every financial service connected with an account is free or suitable for every person. The app itself costs nothing to install, but decisions about borrowing, payments, and account use deserve the same care they would receive outside the app. I would read the terms associated with my own Avant product and avoid making a financial choice solely because the app makes it easy to tap through.
Who should use it and who should skip it
I think Avant is a strong candidate for an existing Avant card or loan customer who wants a dedicated mobile route to account information. It is also a good fit for someone who values quick transaction checks and wants payment management close at hand. The Everyone rating makes it broadly accessible from a content perspective, while the minimum operating-system requirement of Android 6.0 or later gives older compatible devices a chance to run it.
I would skip it if I am searching for a tool to combine several banks, build a detailed budget, track investments, or visualize long-term spending patterns. I would also skip it if I do not have an Avant relationship to manage. In that case, the app’s focused design is not a benefit; it simply does not address the problem I am trying to solve.
It is worth asking one practical question before installing: do I need account access often enough for a dedicated app to improve my routine? If the answer is yes, the convenience is easy to understand. If I check the account only occasionally and already prefer a desktop browser, the additional installation may not change much.
What I would watch as the product continues
As the app evolves, I would watch for improvements that make payment and transaction workflows clearer without pushing the product away from its focused purpose. Better organization, clearer status information, and smoother movement between card or loan tasks would matter more to me than decorative changes. In a finance app, small clarity improvements can have a bigger effect than a long list of new buttons.
I would also pay attention to how well the app serves both sides of its audience. Card users and loan users share a need for account access, but their daily questions are not identical. A good future direction would keep the experience understandable for both groups while avoiding unnecessary complexity for people who only need one type of account task.
The broader question is whether Avant remains a companion for its own products or tries to become a general finance platform. My preference is a disciplined approach. The app already has a clear job, and doing that job reliably is more valuable than adding features that make a payment or transaction check harder to find.
After using it, I see Avant as a practical, focused finance app rather than an all-in-one money manager. Its free access, established release history, current 4.7.0 version, and strong user response make it an easy recommendation for the right audience. My strongest recommendation is simple: use it as a dedicated Avant account tool, and pair it with a broader budgeting method if your financial life extends beyond that account.
That distinction keeps expectations realistic. For quick checks, payment routines, and a clearer connection to an Avant card or loan, the app is useful and easy to justify. For complete financial planning, another tool will serve you better. I would install it when the account relationship is already there, build a careful review-and-payment habit around it, and remember that convenience is most valuable when it supports—not replaces—good financial judgment.
FAQ
What is Avant and what can I use it for?
Avant is an app designed to provide users with a convenient digital experience through its available tools and services. Depending on the version and platform, it may help you manage information, access specific features, or interact with content from one place. Before downloading, check the official description carefully because available functions can differ between Android and iOS versions or change after updates.
Is Avant free to download and use?
Avant may be available as a free download, but some features could require in-app purchases, a subscription, or an account. I recommend reviewing the pricing details shown on the official Google Play Store or Apple App Store listing before installing it. Also check whether the free version includes advertising, usage limits, or restricted tools, since these conditions can affect the overall experience.
Is Avant safe and trustworthy to install?
As with any application, Avant should be downloaded only from an official store or a verified source. Before installation, review the developer name, recent user feedback, update history, requested permissions, and privacy information. Avoid modified APK files or unofficial download links, as they may contain security risks. The app’s safety can also depend on keeping your device and the application updated.
What permissions and personal information does Avant require?
The permissions Avant requests depend on the features you use and the operating system on your device. It may request access to items such as notifications, storage, camera, location, or account information, although not every permission is necessarily required. Read the privacy policy and permission prompts carefully, and deny access that seems unrelated to the app’s main purpose or that you do not feel comfortable providing.
Will Avant work on my Android or iPhone?
Avant’s compatibility depends on the operating system version, device model, available storage, and the current requirements listed in the app store. Older phones or tablets may not support the newest release, and certain functions may work differently on Android and iOS. Before downloading, check the official store page for supported versions, app size, recent update information, and any device-specific limitations.











