

Ava Finance
4.7FinanceUpdated October 5, 2026
Screenshots
Pros
- Easy access to crypto lending and borrowing from a mobile interface.
- Supports multiple assets for managing a more diversified DeFi portfolio.
- Transparent blockchain transactions make activity easier to verify.
- May offer competitive yields compared with some traditional savings products.
- Useful for experienced users seeking decentralized financial tools.
Cons
- Crypto prices and collateral values can change sharply
- increasing repayment risk.
- Loan liquidation may occur if collateral falls below required levels.
- DeFi transactions can involve network fees and variable confirmation times.
- Smart-contract bugs or exploits could put deposited funds at risk.
- The platform may be difficult for beginners unfamiliar with wallets and Web3.
 Analysis By Mobexer
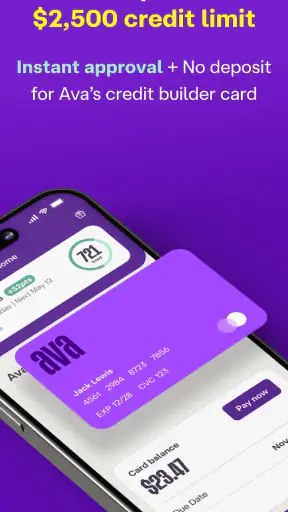
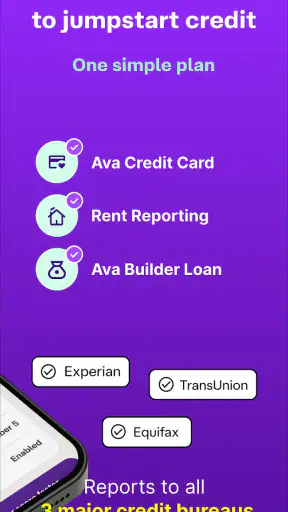
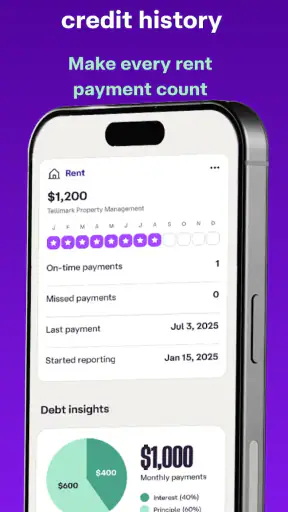
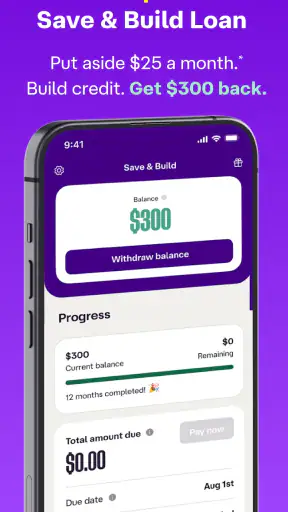
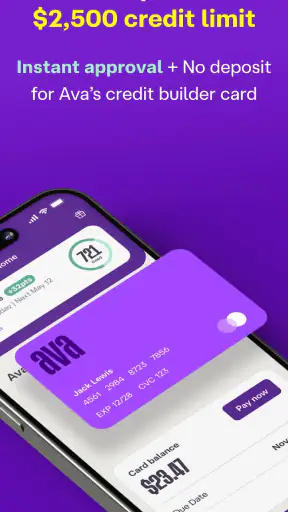
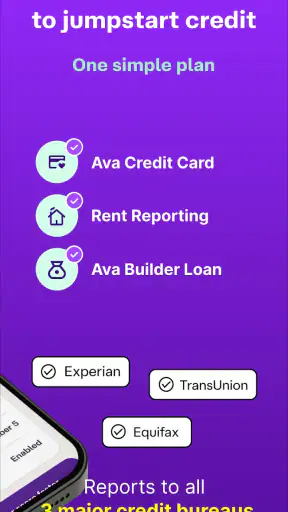
I approached Ava Finance as a practical credit-building app rather than another general budgeting tool. Its focus is narrower: helping people work toward stronger credit habits through a mobile finance experience. That makes it potentially useful for someone who wants a simple starting point, but it also means it should not be judged like a full bank account, investment platform, or detailed expense manager.
The app comes from Ava Finance, Inc. and is free to install, with an Everyone content rating. It is available for devices running Android 9 or later, and the current version is 5.1.6626. Those details matter because finance apps need to feel dependable on the phone you use every day, not just look polished during a quick first launch.
How Ava feels during everyday use
Speed expectations when checking your credit routine
My first impression is that Ava is designed for short, purposeful visits rather than long sessions. A credit-building app works best when I can open it, understand what needs attention, and leave with a clear next step. That is a better fit for a morning check-in or a quick review before making a purchase than for someone who wants to spend an hour categorizing every transaction.
The perceived speed of a finance app is not only about how quickly screens appear. It is also about how quickly I can understand the information on them. Ava’s value depends on reducing uncertainty: I want to know what action is expected, whether I am keeping up with my plan, and what I should review before moving on. A clean, focused workflow can feel faster than a more feature-heavy alternative even when both take a similar amount of time to load.
That focus is one of the app’s strongest practical qualities. People who find traditional credit information confusing may prefer a guided mobile experience over a large financial dashboard filled with unfamiliar terms. I would especially consider it for someone beginning to take credit seriously and looking for one place to build a repeatable routine.
There is an important distinction, though. Ava should not be treated as an instant solution to every credit problem. Building credit requires consistent behavior, careful attention to obligations, and patience. The app can make the process easier to follow, but it cannot replace reviewing the details of any financial commitment before accepting it.
What happens during heavier use
Heavy use for this kind of app does not usually mean streaming media or running complex games. It means repeated account checks, reading explanations, reviewing activity, and moving through financial steps while switching between the app and other services. That is where I would judge Ava less by flashy performance and more by whether it remains understandable when I am doing several related tasks in one sitting.
A realistic example is a user who receives an alert about an upcoming obligation, checks the app during a lunch break, compares the information with a bank balance, and returns later to confirm that everything is in order. The best workflow is one that prevents small uncertainties from becoming missed actions. I would recommend setting aside a regular review moment rather than opening the app randomly whenever anxiety about credit appears.
Another useful approach is to use Ava as a checkpoint alongside a broader money routine. I might review my spending in a banking app, then open Ava specifically to think about credit-related progress. Keeping those jobs separate can reduce mental clutter. It also avoids expecting a credit-building product to provide the same depth of budgeting, bill management, or account aggregation that a dedicated personal-finance app may offer.
The trade-off is that a focused app can feel limited when my needs expand. If I want detailed cash-flow forecasting, investment tracking, or a complete household budget, I would likely need another tool. Using Ava together with a bank’s app may be more effective than trying to force it into the role of an all-purpose financial command center.
Reliability and the importance of recovery
Reliability matters more in finance than in many other app categories. A minor interruption in a game is annoying; uncertainty during a credit-related task can be much more stressful. I therefore look for a workflow that encourages me to verify important information and return calmly if a session is interrupted.
My practical advice is to avoid starting an important financial action while rushing between appointments or relying on an unstable connection. Read each screen carefully, keep confirmation details where appropriate, and reopen the app afterward if you are unsure whether a step completed. That is not a criticism unique to Ava; it is a sensible habit for any app connected to financial decisions.
Recovery also means knowing what to do when the app does not behave as expected. If a screen takes longer than usual, I would first check the connection, close and reopen the app, and avoid repeating an action until I know whether the first attempt went through. Repeated tapping is a poor habit in finance because it can create confusion about what was submitted or confirmed.
I also prefer to judge reliability over repeated, ordinary visits rather than one impressive session. A finance app earns trust when its information remains easy to interpret and its workflow does not make me guess. Ava’s strong public reception—an average rating of 4.7 from around 17 thousand ratings—suggests that many users find the overall experience useful, although a rating cannot tell me whether it matches every person’s financial situation.
Device constraints and the right phone for it
Ava’s minimum requirement of Android 9 keeps it accessible to many older Android phones, which is helpful for users who do not upgrade frequently. Still, operating-system compatibility is only one part of the experience. A phone with very little free storage, an overloaded background workload, or an unreliable connection can make any finance app feel slow or unstable.
I would be more comfortable using it on a phone that receives security updates and has a lock screen enabled. The app deals with a sensitive subject, so basic device hygiene matters: use a strong device passcode, avoid signing in on a shared phone, and install updates through the normal official app channel. These steps are especially important for people using an older device simply because it meets the minimum operating-system requirement.
Screen size can affect comfort too. A compact phone may be perfectly adequate for quick checks, while a larger display can make longer explanations easier to read. I would not choose a tablet or second device solely for Ava unless it already fits my wider financial routine. The app’s usefulness comes from being available during normal daily decisions, not from turning credit management into a separate workstation.
Resource demands are best considered in context. Ava is a finance utility, so I would expect short sessions and modest interaction rather than continuous foreground use. The sensible test is whether it fits comfortably into my phone’s normal workload. If the device already struggles with basic apps, the problem may be the phone’s overall condition rather than this particular product.
Who will benefit most from the focused approach
I see Ava as a good candidate for someone who wants a structured introduction to credit building and prefers mobile guidance to researching every concept independently. It may also suit a person who has avoided credit because the subject feels intimidating and wants a more approachable way to develop consistent habits.
The app can be useful when my goal is narrow and measurable: checking in regularly, understanding the next action, and keeping credit-related behavior from disappearing among other financial tasks. Its free price lowers the barrier to trying the experience, although free access should never be confused with a guarantee that every financial outcome will be free of conditions or responsibilities. I would read every screen before agreeing to anything.
I would skip it if I already have a sophisticated credit-monitoring and budgeting system that I understand well. Adding another finance app can create duplicate reminders, conflicting information, or unnecessary account management. I would also look elsewhere if my main need is investing, tax preparation, detailed debt payoff modeling, or full household expense tracking. Ava’s focused purpose is a strength only when that purpose matches the problem I am trying to solve.
How it compares with familiar alternatives
The usual alternatives fall into several groups. A bank app is often better for checking balances and moving money. A budgeting app is usually better for categorizing spending and planning monthly expenses. A credit-report service may be better for people who want broad monitoring and historical information. Ava sits closer to the credit-building side of the spectrum, where the main question is how to establish and maintain constructive credit behavior.
That difference changes how I would use it. I would not replace my bank’s app with Ava, and I would not expect it to replace a detailed budget. Instead, I would use each tool for the job it handles best. The advantage is less duplication when the roles are clear. The disadvantage is having another financial login and another place to review.
Ava’s appeal is therefore strongest for beginners or for users whose existing tools explain what happened but do not make the next credit-related step feel manageable. Someone who already knows exactly what they are doing may prefer a more comprehensive service with fewer separate apps. The better choice depends on whether guidance and focus are more valuable to me than breadth.
Small habits that make the app more useful
My first tip is to create a fixed review habit instead of checking compulsively. A brief, scheduled visit makes it easier to notice changes without letting credit concerns dominate the day. I would pair that review with a quick look at my available cash so that any planned action fits my real budget.
My second tip is to separate education from execution. If Ava presents information I do not understand, I would pause and research the term before proceeding. Moving quickly through a financial screen just because the app feels simple is still risky. The app can organize the process, but I remain responsible for understanding the commitment.
My third tip is to keep a personal record of important decisions rather than relying on memory. I might note the date I reviewed an item and what I intended to do next. This is useful if I later compare information across Ava and my bank, or if I need to work out whether a change is new or simply something I overlooked.
A fourth practical insight is to avoid measuring success only by how often I open the app. Frequent launches are not the goal. The meaningful outcome is a consistent, informed routine that supports healthier credit behavior. If opening Ava becomes a source of repeated worry without leading to a clear action, I would step back and reassess whether a counselor, bank resource, or different financial tool would serve me better.
Version, reach, and overall confidence
The current release is 5.1.6626, and the app has passed around half a million installs. That level of adoption makes it easier for me to view Ava as an established product rather than an experiment with no visible user base. The developer, Ava Finance, Inc., has built the app specifically around its credit-focused identity instead of presenting it as a generic money dashboard.
At the same time, adoption and ratings are not substitutes for personal suitability. A 4.7 average is encouraging, but finance products can work very well for one user and be a poor fit for another because goals, income patterns, and existing credit histories differ. I would install Ava because its purpose matches my needs, not simply because many people have rated it positively.
The Everyone rating makes the app broadly approachable from a content perspective, but younger or inexperienced users still need adult guidance when a financial decision involves obligations. A simple interface should encourage careful reading, not remove the need for it.
My performance verdict
After looking at Ava through the lens of speed, heavier use, reliability, recovery, and device limits, I think its strongest quality is focus. It is built for people who want credit building to feel like a manageable routine rather than an abstract financial subject. Short sessions, a compatible Android device, and a habit of checking information carefully should provide the most comfortable experience.
I would recommend trying it if I were starting to build credit, wanted a more guided process, and was willing to keep a separate tool for everyday banking or budgeting. I would not recommend treating it as a complete replacement for those services, nor would I use it as a reason to accept financial terms without understanding them.
My final view is positive but deliberately measured: Ava is most valuable when it turns credit-building intentions into consistent, informed check-ins. It is less convincing for experienced users who already have a complete system or for anyone looking for broad financial management. Used within its proper role, the free app offers a focused way to make credit a regular part of my money routine instead of something I only think about when a problem appears.
FAQ
What is Ava Finance, and what can I use it for?
Ava Finance is a mobile-focused financial application designed to help users manage and interact with digital assets and related financial services. Depending on your location and the version available, it may provide tools such as account management, asset tracking, transfers, and access to decentralized finance features. Before downloading, review the supported services, currencies, and regional availability carefully.
Is Ava Finance safe to use for managing digital assets?
Ava Finance may include security features such as account authentication, encrypted connections, and wallet or transaction protections, but no financial application is completely risk-free. Digital-asset transactions can be irreversible, and users are responsible for protecting passwords, recovery phrases, and verification codes. Download the app only from an official store and check the developer details before signing in.
Does Ava Finance charge fees for transactions or other services?
Fees can vary depending on the service you use, the asset involved, network conditions, and your location. Some actions may include platform fees, blockchain network fees, exchange spreads, withdrawal charges, or other costs displayed before confirmation. I recommend checking the current fee schedule inside the app and reviewing every transaction summary carefully rather than assuming that transfers are free.
Can beginners use Ava Finance without previous cryptocurrency experience?
Ava Finance may be approachable for users who are new to digital finance, particularly if its interface provides clear balances, transaction histories, and guided actions. However, beginners should understand basic concepts such as wallet addresses, network selection, market volatility, and transaction fees before depositing money. Start with a small amount, read the in-app explanations, and avoid products you do not fully understand.
What should I check before downloading Ava Finance on Android or iPhone?
Before installing Ava Finance, confirm that the application is available in your country and that you are downloading the genuine listing from the official Google Play Store or Apple App Store. Check the developer name, recent reviews, requested permissions, privacy policy, supported devices, and update history. Also verify whether identity checks, minimum deposits, age requirements, or regional restrictions apply to the features you want.











