

Aspire Account Center
3.3FinanceUpdated October 5, 2026
Screenshots
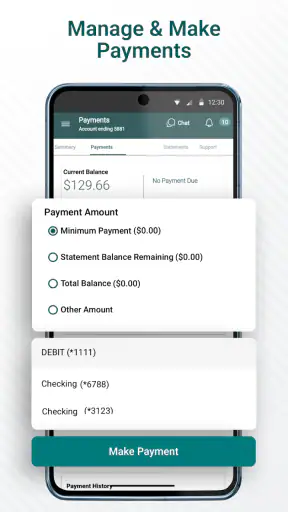
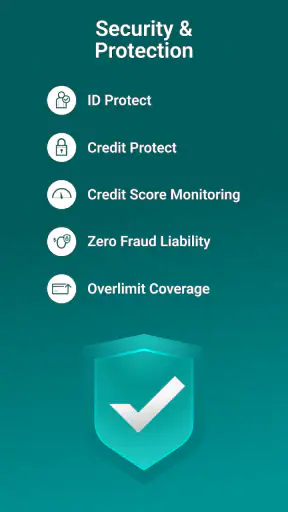
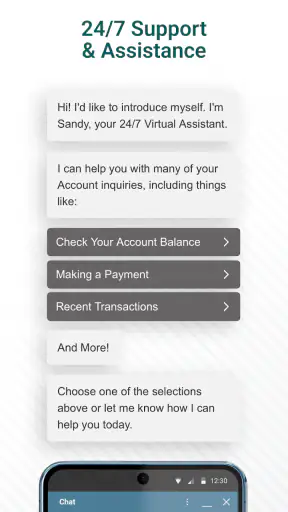
Pros
- Centralizes account settings and profile information in one place.
- Makes it easier to manage Aspire-related services from a mobile device.
- Provides quick access to account details without visiting a website.
- Simple layout is suitable for users who prefer straightforward navigation.
- Can reduce the time needed to update personal or account preferences.
Cons
- Some features may require an active Aspire account or eligible service.
- Availability of tools can vary by region
- account type
- or Aspire product.
- Limited value for users who rarely need to manage their account settings.
- Account-related actions may depend on a stable internet connection.
- Users may need to contact support for issues not covered in the app.
 Analysis By Mobexer
I found Aspire Account Center most useful as a focused companion for people who already use Aspire credit cards and want a simpler way to keep an eye on their account. It is a free finance app from Atlanticus Services, designed to bring card management into one mobile location rather than making you rely on a browser or scattered account notes. My impression is that it succeeds best as a practical account-access tool, not as a complete personal-finance system.
That distinction matters. If your goal is to check your card, review activity, and stay aware of what is happening between statements, the app has a clear purpose. If you want budgeting across several banks, investment tracking, bill negotiation, or a broad spending dashboard, I would look elsewhere. Its value comes from being tied to the Aspire card experience, so the right question is not whether it can replace every finance app, but whether it makes managing this particular credit relationship easier.
How the app fits into everyday card management
The app belongs to the finance category and is intended for general audiences, with an Everyone content rating. It has been available since June 25, 2019, and the current release is version 4.22.47-6102 for devices running Android 6.0 or later. Those details suggest a product with a long-running mobile presence and broad device compatibility, rather than a service aimed only at newer phones.
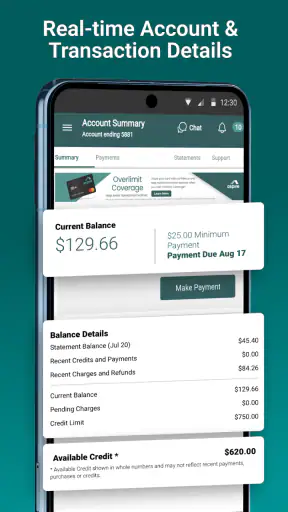
In practical use, I think of it as a control point for routine card tasks. Instead of opening a desktop browser whenever I want to check an account, I can use a phone-based interface built around the card relationship. That is especially convenient when I am standing at a checkout, checking whether a recent purchase has appeared, or trying to understand how much room remains before making another purchase.
The app is not presented as a general-purpose wallet. That is one of its defining characteristics. A banking aggregator may collect checking, savings, loans, cards, and investments in one dashboard, while a budgeting app may classify spending across multiple institutions. Aspire Account Center takes a narrower route. Its strength is concentration: the experience is organized around Aspire credit-card management instead of trying to become a complete financial command center.
I also appreciate that the app’s audience is easy to identify. Existing Aspire cardholders have an obvious reason to install it. Someone who does not have an Aspire account is unlikely to gain much from downloading it simply to browse. This is not a discovery tool for comparing cards or a financial education app; it is an account companion.
What free access means here
The app is free to use. That makes the initial decision straightforward: there is no purchase price to weigh against the convenience of mobile access. For an existing cardholder, the useful comparison is between installing the app and continuing to manage the account through other available channels, such as a browser or paper statements.
Free access does not automatically make every finance app valuable, so I would still judge it by how often it removes friction. If I check my card regularly, a dedicated app can save time and make account awareness part of my normal phone routine. If I only look at the account once every few months, the benefit is smaller. The financial value is therefore indirect: the app does not become worthwhile because it has a price advantage over paid software, but because convenient access may help me notice activity and stay organized.
I would not treat “free” as a promise that every possible financial service is included. The sensible expectation is access to the Aspire account center itself, not a replacement for a paid budgeting platform or a full banking suite. That boundary keeps the value assessment honest. The app costs nothing to install, but its usefulness depends heavily on whether I already have an Aspire card and how much I want mobile access.
Where the focused design helps
The most useful benefit is reduced context switching. When a finance app is built around one account, I do not need to search through a broad collection of institutions to find the card I care about. That can be helpful during ordinary moments that are easy to overlook: confirming whether a transaction has posted, checking the account before making a larger purchase, or reviewing activity after using the card in several places.
A realistic example is a busy week in which I use the card for groceries, transportation, and an unexpected household expense. Rather than waiting for a statement, I can open the account center and review the recent picture while those purchases are still fresh in my memory. If something looks unfamiliar, early awareness gives me a better chance to investigate it while I can still remember where I used the card.
Another useful workflow is a short weekly check. I would open the app at the same time each week, scan recent activity, and compare it with receipts or notifications I already have. This is not a full budgeting method, but it is more disciplined than ignoring the account until a payment deadline or statement arrives. The app’s narrow focus can actually help here because it keeps the check quick and specific.
There is also a practical planning advantage. Before using a credit card for a planned purchase, I can check the account rather than guessing based on memory. That does not replace responsible credit planning, and it does not turn the app into a financial adviser, but it can prevent avoidable surprises caused by forgetting a recent transaction or misjudging the account position.
For people who manage money with a partner or family member, the app may also serve as a convenient point for checking the card account during conversations about spending. I would still avoid treating a mobile balance as a complete household budget. It is better used as one reliable reference for the Aspire card than as the sole source for every financial decision.
What I would not expect it to replace
The biggest limitation is scope. A dedicated card center is not the same thing as a multi-account financial dashboard. If I need to compare Aspire activity with checking-account cash flow, another credit card, savings goals, or investment balances, I would need a separate tool or a manual process. That extra step may be acceptable for someone who wants focused access, but it will feel restrictive to anyone seeking one complete view.
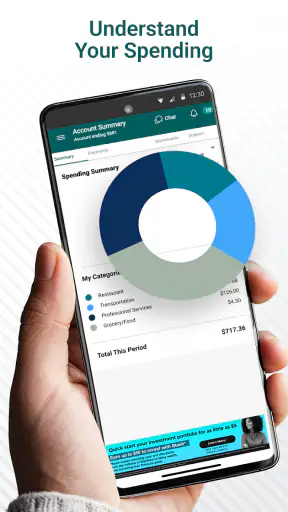
It is also not the right choice for building a detailed spending plan across categories. I can use activity from a card as one input, but a card-management app should not be confused with a budgeting system that brings together income, recurring bills, cash transactions, and accounts from different providers. People who want category trends or long-term financial projections will probably get more value from a dedicated budgeting product, assuming they are comfortable connecting their accounts there.
I would also keep a browser or statement-based backup habit. An app is convenient, but important financial records should not exist in only one place. For routine awareness, the mobile experience is attractive. For carefully reviewing a long history, saving records, or handling a complicated account question, a larger screen or direct support channel may be more comfortable.
Another trade-off comes from the app’s account-specific nature. Its usefulness follows the Aspire relationship. If I change cards, primarily use another issuer, or want a neutral tool that does not center on one provider, the app becomes less relevant. A broad finance app may require more setup, but it can remain useful even when my financial products change.
Who is likely to get the most value
I would recommend trying it first if you are an Aspire cardholder who prefers handling routine account checks on a phone. It makes particular sense for people who travel between home, work, and stores, because mobile access is more convenient than waiting until a computer is available. It can also suit anyone who wants a small, repeatable account-review habit without adopting a much larger budgeting platform.
It is a reasonable fit for users who are comfortable with a focused finance tool. You do not need the app to solve every money-management problem. You need it to make the Aspire card easier to monitor. That narrower expectation is important because it prevents disappointment and helps the free access deliver its intended value.
I would be more cautious if you are trying to reduce the number of financial apps on your phone. If your bank already provides a consolidated view that includes this card, installing another app may not add enough convenience. The same is true if you rarely use the card or prefer managing everything through monthly statements. In those situations, the app may simply duplicate a process that already works for you.
People who want advanced budgeting, shared household planning, debt payoff projections, or a combined view of several institutions should probably choose a broader finance solution instead. That does not make Aspire Account Center poor at its job; it means the job is narrower than the needs of those users. I would rather use a focused account center alongside a budgeting tool than expect one specialized app to perform both roles.
My view of its reputation and maturity
The app has an average rating of 3.3 from around 2.1 thousand ratings, with roughly 967 written reviews. I read that as a mixed signal rather than a reason to dismiss it. There is enough user activity to show that the app has been used by a substantial audience, but the rating also suggests that the experience will not satisfy everyone equally.
Its reach is reflected in more than 500 thousand installs. That does not prove that every user has a smooth experience, yet it does indicate that the app is not an obscure experiment. Combined with its multi-year availability, the numbers make it reasonable to consider as an established account-access option while still keeping expectations realistic.
For me, the rating reinforces the importance of matching the app to the right use case. A person looking for basic Aspire card access may judge it more favorably than someone expecting a polished replacement for a full banking dashboard. Finance apps are especially sensitive to login flow, account synchronization, and the clarity of transaction information, so a focused purpose does not eliminate the need for a dependable day-to-day experience.
I would also pay attention to how the app fits my own routine rather than assuming the public rating predicts my exact experience. Before relying on it for an important payment decision, I would install it, sign in, confirm that the account information is clear, and keep another way to access records. That small amount of caution is sensible with any financial application.
Small habits that make the app more useful
My first tip is to use it for short, regular reviews instead of opening it only when something goes wrong. A quick scan after a few days of card use can make unfamiliar activity easier to recognize. Waiting until the end of a long statement period makes memory less reliable and turns a simple check into detective work.
Second, I would separate account awareness from budgeting. Use the app to understand what is happening on the Aspire card, then record or combine that information in whatever broader system you use for household planning. This avoids a common mistake: assuming that knowing the card activity is the same as knowing the complete financial picture.
Third, I would check the account before large or unusual purchases rather than relying on an old balance remembered from a previous visit. This is a small workflow change, but it is more useful than treating the app as something to open only after a transaction is disputed. The point is to use current information when making a decision.
Finally, I would keep statements and important payment details organized outside the app as well. Mobile access is excellent for immediacy, while statements and other records are better suited to deliberate review. Combining both approaches gives me convenience without making the app carry more responsibility than it should.
My recommendation for potential users
My final judgment is positive but deliberately narrow. Aspire Account Center is worth trying when I already use an Aspire credit card and want free, direct mobile access to manage that relationship. The focused design can make routine checks less cumbersome, and its broad Android compatibility means it is available to users with older supported devices as well as newer ones.
I would skip it as my main finance app if I need one place for several banks, detailed budgeting, investment monitoring, or broader household planning. In that case, a multi-account finance tool is a better match, even if it involves more setup. I would also skip it if my current browser or banking routine is already convenient and I rarely check the card.
My buy-or-skip verdict: install it if you are an Aspire cardholder who values simple mobile account access; skip it if you are looking for a complete personal-finance dashboard. Because it is free, the trial decision is low-risk, but the real value appears only when the app becomes part of a sensible checking routine. I see it as a useful specialist, not an all-purpose money manager—and that is exactly how I would recommend using it.
FAQ
What is Aspire Account Center used for?
Aspire Account Center is designed to give Aspire customers a central place to manage and review their account information. Depending on the services available in your region, you may be able to check account details, review activity, access support resources, and manage selected settings without contacting customer service for every request. The exact tools can vary by account type and location.
Who can use Aspire Account Center?
The app is generally intended for existing Aspire customers with an eligible account or service. You will normally need valid login credentials and may be required to complete an identity or security verification step before accessing personal information. Availability can depend on your country, Aspire product, and account status, so prospective users should confirm that their specific service is supported before downloading.
Is Aspire Account Center safe for managing personal account information?
Because the app may provide access to sensitive account details, users should treat it like any financial or personal-management application. Download it only from an official app store or an authorized Aspire source, verify the developer name, and keep the app updated. Avoid sharing passwords or verification codes, and use a secure connection rather than public Wi-Fi when reviewing private information.
What should I do if I cannot sign in to Aspire Account Center?
If login fails, first check that your email address, username, password, and internet connection are correct. Look for an available password-reset or account-recovery option and make sure your device can receive required verification messages. Repeated failed attempts may temporarily restrict access. If recovery tools do not work, contact Aspire through its official support channels instead of relying on unofficial websites or third-party assistance.
Does Aspire Account Center work on every Android or iPhone device?
Compatibility depends on the current version of the application, your operating-system version, and whether Aspire officially supports your region and device. Older phones may not receive all features or may be unable to install the latest release. Before downloading, review the app-store requirements, available storage, and permissions. Keeping Android or iOS updated can also improve security and reduce compatibility problems.











