

Acorns Early: Kids Money App
4.5FinanceUpdated October 2, 2026
Screenshots
Pros
- Teaches saving habits through age-appropriate money activities.
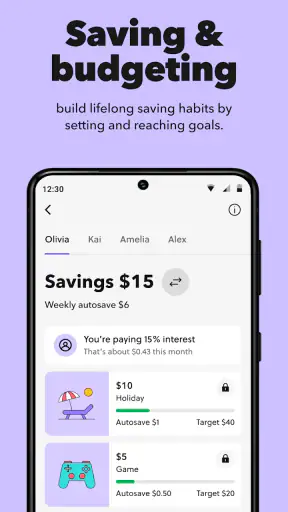
- Parents can set goals and track progress from one dashboard.
- Designed to encourage conversations about spending and saving.
- Simple interface is accessible for younger children.
- Useful companion for families introducing financial responsibility.
Cons
- Requires parent involvement to deliver the most value.
- Some features may depend on an eligible Acorns family plan.
- Children may need help understanding real-world money concepts.
- Limited appeal for kids who prefer highly interactive games.
- Account setup and permissions can take time for parents.
 Analysis By Mobexer
I approached Acorns Early as a parent-facing finance app rather than as a simple savings game. Its purpose is to help families introduce children and teenagers to money through an investing plan, so the important question is not only whether the interface feels friendly. It is whether the app gives adults enough clarity and control to make thoughtful choices on a child’s behalf. After spending time with it, I see a focused product for families who want to make long-term financial habits part of everyday life, but I would not treat it as a complete financial education system by itself.
The app is free, belongs to the finance category, and is developed by Acorns. It has an average rating of 4.5 from around 3,200 ratings, with more than 500 written reviews and over 100,000 installs. Those figures suggest that it has attracted a meaningful audience without making it feel like a mainstream banking replacement. The age classification is Everyone, which fits the family-oriented presentation, although parents still need to remain involved because investing decisions are not something I would hand over entirely to a young user.
What Acorns Early is really trying to do
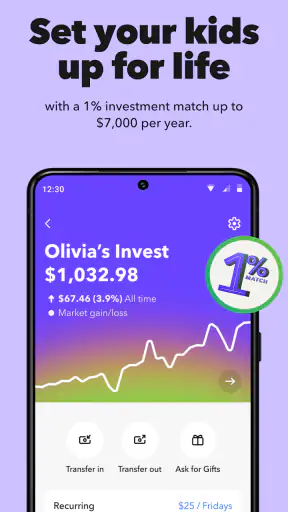
The central idea is straightforward: connect a child’s financial development with a smart investing plan. That makes the app different from a basic allowance tracker, a digital piggy bank, or a budgeting worksheet. Instead of focusing only on recording money coming in and going out, it is designed around building a longer-term relationship with saving and investing.
I think that distinction matters. A child who sees a balance in a savings app may understand that money can be stored. A child who discusses why money is being invested can begin to understand that financial decisions involve time, goals, uncertainty, and patience. The app is most useful when an adult uses it as a conversation starter rather than presenting it as an automatic solution to money education.
In a realistic household, a parent might open the app during a weekly allowance conversation. Rather than handing over cash and forgetting about it, the parent can use the moment to discuss how much is available now, what portion is intended for a near-term purchase, and why another portion may be connected to a longer-term plan. That routine is more valuable than simply checking the app every few months. The technology provides a place for the discussion, but the learning comes from the explanation around it.
That also explains why I would not recommend this app to someone looking for a full-featured personal finance dashboard. An adult who wants detailed spending analysis, complex budgeting categories, or an all-purpose investment workstation may find a conventional finance service more appropriate. Acorns Early is narrower and more family-centered. Its strength is the child-and-teen context, not professional-level financial control.
Trust starts with the adult account holder
Financial apps deserve a higher level of scrutiny than ordinary entertainment apps because users may connect personal information, money decisions, and family relationships in one place. With this product, I would begin by identifying who is expected to make decisions. The store summary clearly frames the experience around building a child’s or teenager’s financial wellness, but that should not be confused with giving a minor unrestricted authority over an investment plan.
My practical advice is to set it up with the adult’s involvement from the beginning. Read each screen during registration, pay attention to which choices are presented as optional or required, and avoid rushing through account prompts simply to reach the main interface. A finance app can feel simple while still asking for decisions that deserve a pause. The safest workflow is to treat every connection, transfer, and permission as a separate choice instead of accepting the entire setup as one package.
I also prefer a family discussion before any money is committed. A child should know whether the app is being used for learning, for a real long-term financial goal, or for both. That distinction prevents a common misunderstanding: an investing plan is not the same thing as a guaranteed result. Even when the interface is designed to be approachable, adults should explain that financial outcomes can change and that money intended for an immediate need should not be treated like distant savings.
The developer name, Acorns, gives the product a clear identity, but a recognizable developer should not replace personal review. I would still examine the account screens, the available controls, and the privacy choices directly. Trust is built through visible explanations and deliberate choices, not through branding alone.
Controls that parents should check before involving a child
The most useful way to evaluate Acorns Early is to look for control points. Before introducing it to a young user, I would confirm who can initiate or approve financial actions, who can view activity, and how the adult can change or stop the arrangement. These questions are more important to me than whether the app has a cheerful design.
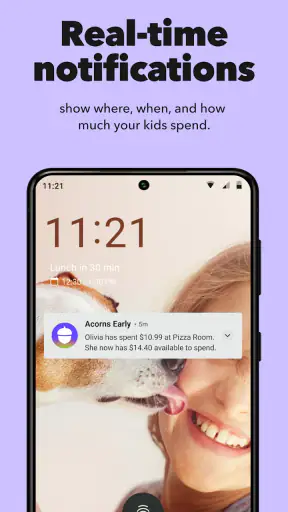
I would also establish a household rule for notifications and review sessions. If the app sends alerts, they should support awareness rather than create pressure to check constantly. A monthly conversation may be enough for one family, while another may prefer a shorter weekly check-in. The important point is that the parent decides the rhythm instead of allowing the app to become the child’s only source of financial guidance.
Another practical step is to separate learning from spending requests. If a child uses the app to understand a goal, that does not automatically mean the child should be able to change the goal, move money, or request a withdrawal without adult discussion. I would look for those boundaries during setup and revisit them whenever the child becomes more independent. A control that is suitable for a teenager may not be suitable for a younger child.
There is a trade-off here. More adult control can make the experience slower and less spontaneous, but that friction is not necessarily a flaw. In a financial product, a confirmation step can prevent an impulsive decision. I would rather spend an extra minute reviewing an action than create a system where a child believes every visible button represents an immediate, consequence-free choice.
Data-sensitive moments deserve a slower review
Family finance apps naturally bring sensitive moments into one workflow: creating an account, identifying the adult, connecting financial information, adding a child, and reviewing activity. I would pay the closest attention during those transitions. The main screen is usually the least revealing part of a finance app; the important choices often appear during setup, account linking, or changes to personal details.
When a screen asks for information, I would first ask why it is needed and whether the app explains how it will be used. I would read the privacy and account notices rather than relying on a quick glance at the interface. If the app presents separate choices for communications, sharing, or notifications, I would make each decision independently. This is a small habit, but it gives the parent more agency and reduces the chance of agreeing to something unintentionally.
I would use the same care when inviting a child or teenager into the experience. A young person may not understand the difference between a profile, a financial account, and a learning view. Before sharing access, explain what the child will be able to see and what remains under adult control. If the app shows family activity, decide whether that visibility is appropriate for the child’s age and maturity.
Device security matters too. I would protect the phone with a screen lock, avoid leaving the finance app open on a shared device, and sign out or secure the device when other people can access it. These are not glamorous features, but they are part of responsible use. An app can offer useful controls while still being exposed by an unlocked phone or a casually shared login.
I would also review the account periodically rather than assuming that the original settings will remain ideal forever. Children grow, family circumstances change, and an account that made sense at setup may need different visibility or supervision later. That review is especially important when a teenager begins asking for more independence. The right response is not automatically to remove all oversight or to keep every restriction forever; it is to adjust access deliberately.
Where the app gives families useful agency
For me, the best part of Acorns Early is the opportunity to turn abstract financial ideas into a repeatable family routine. The app can give a parent a concrete reference point when discussing goals, patience, and responsibility. Instead of explaining investing only through a book or a one-time lecture, an adult can return to the same plan and connect it with real decisions.
A useful workflow is to choose one goal, define what the child is trying to understand, and then review progress at a calm interval. For example, a parent might use a birthday contribution as a chance to explain that not every dollar has to be used immediately. Later, the family can discuss whether the goal is still meaningful and whether the child understands the difference between money set aside for now and money intended for later. This makes the app part of a lesson without turning every interaction into a lecture.
A second useful approach is to let the child ask questions before showing the numbers. Ask what they think will happen, what they want the money to do, and what they would change if the goal took longer than expected. Then use the app to support the conversation. This prevents the interface from becoming a scoreboard where the child judges success only by whether the balance rises.
A third insight is that visibility should match responsibility. Giving a teenager more involvement can make the experience educational, but only if the adult explains the limits clearly. A child can participate in setting a goal or reviewing activity without being responsible for decisions they are not ready to understand. I see that gradual approach as more useful than either extreme: hiding everything from the child or giving unrestricted access too early.
There is also value in using the app alongside ordinary money habits. Let a child compare a planned purchase with a longer-term goal, or discuss why an emergency reserve is different from investment money. The app should not replace cash handling, basic arithmetic, or conversations about needs and wants. It works best as one piece of a broader lesson.
How it compares with familiar alternatives
The usual alternative is a simple savings account or a parent-maintained spreadsheet. Those options can be easier to understand and may involve less technology. A spreadsheet gives an adult complete control over what is recorded, while a savings account may feel more concrete to a child who is learning the idea of setting money aside. If your main goal is tracking allowance or teaching basic budgeting, either option may be enough.
Acorns Early becomes more appealing when the family wants investing to be part of the lesson. It offers a more focused setting for connecting a child’s financial development with a longer-term plan, which a basic tracker does not naturally provide. The trade-off is that investing introduces more concepts to explain. A spreadsheet is mechanically simple; an investment-oriented family app requires more care around expectations, time horizons, and adult supervision.
Compared with a general adult finance app, this product appears better aligned with conversations about children and teenagers. A standard adult app may provide more detailed financial tools, but it can feel too complicated or too detached from a child’s learning process. I would choose the general alternative for my own detailed budgeting or investment analysis, and choose Acorns Early when the family goal is to make money education visible and shared.
Compared with a purely educational money game, the advantage is seriousness and relevance. A game can teach vocabulary or simulate choices without involving a real family plan. Acorns Early is more suitable when the parent wants lessons connected to actual financial behavior. The disadvantage is that real money requires more caution. I would not use it as a casual game or leave a young child to interpret financial outcomes without guidance.
In short, the choice depends on the lesson. Choose a basic tracker for simple allowance management, a general finance tool for adult-level detail, and Acorns Early when a parent wants a child-oriented path into long-term financial thinking.
Who should use it, and who should pause
I think the app is a good fit for parents who are comfortable staying involved and who want a structured way to discuss saving and investing with a child or teenager. It may also suit families that have struggled to make financial education consistent. A recurring review of one shared plan can be easier to maintain than a collection of disconnected lessons.
I would be more cautious if a family expects the app to teach everything automatically. A young user may see a polished financial interface and assume that the recommended path is risk-free or universally suitable. That is where adult explanation matters. The app can support a plan, but it cannot replace judgment, context, or a conversation about what the money is for.
I would also pause if the household needs highly detailed budgeting, complicated account management, or a single tool for every adult financial task. The child-and-teen focus is the reason to choose this product, but it also defines its limits. A broader finance service may be better for someone who wants extensive customization and adult-oriented analysis.
Families should consider skipping it if they are not ready to review account access and privacy choices carefully. That is not a criticism unique to this app; it is a sensible standard for any service involving children and money. If the setup feels rushed or unclear, stop and inspect the choices before adding financial information or involving a child.
My cautious verdict after using it
Acorns Early makes the most sense to me as a supervised family finance tool, not as an independent money manager for children. Its free availability, Everyone age classification, and clear focus on children’s and teenagers’ financial wellness make it approachable, while its connection to an investing plan gives it more depth than a basic allowance log. The current version is 9.7.0, and the app was released on November 8, 2024; on Android, it requires version 7.0 or later.
My recommendation is conditional but positive: use it if you want a practical setting for ongoing conversations about goals, saving, and investing, and if you are willing to inspect controls each time the family’s needs change. Start with a small, clearly explained routine. Review who can see what, who can approve actions, and which notifications or account choices are truly useful. Those steps make the experience more deliberate and reduce the risk of treating the app like an automatic financial authority.
The strongest reason to choose Acorns Early is not convenience; it is the chance to make financial decisions visible, discussable, and age-appropriate. The strongest reason to hesitate is that a friendly family interface can still involve serious choices. I would recommend it to an involved parent who wants investing to become part of a child’s education, while pointing someone seeking a complete adult finance platform toward a more specialized alternative.
Used with that perspective, Acorns Early can be a helpful bridge between everyday allowance conversations and longer-term financial thinking. I would keep the adult firmly in the driver’s seat, use the app to encourage questions rather than make promises, and revisit the account settings as the child grows. That balance of participation and supervision is where the product has the most practical value.
FAQ
What is Acorns Early: Kids Money App, and who is it designed for?
Acorns Early: Kids Money App is a family-focused financial education and money management tool designed to help parents teach children about saving, spending, and earning. It is intended for families who want to introduce age-appropriate financial habits through practical activities and parental guidance. Availability, account features, and eligibility may depend on the child’s age, the parent’s Acorns account, and regional requirements.
Is Acorns Early safe for children to use?
The app is designed with parental involvement in mind, rather than giving children completely independent access to financial services. Parents typically manage permissions, monitor activity, and decide how the app is used. Before downloading, review the current privacy policy, parental controls, data practices, and account terms carefully. You should also explain basic online safety rules to children and avoid sharing login details.
Does Acorns Early teach children real financial skills or only provide games?
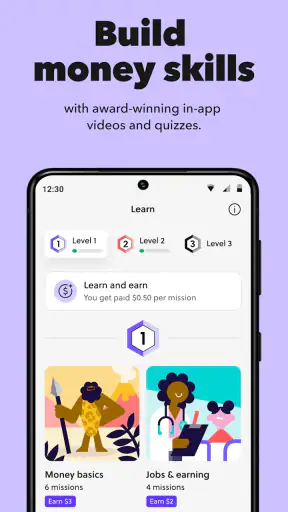
Acorns Early combines educational content with practical money concepts, so it is more than a collection of games. Depending on the available version and account setup, children may learn about saving goals, responsible spending, earning money, and making choices. The app works best when parents discuss the lessons with their children and connect digital activities to real-life financial decisions.
Does using Acorns Early require an Acorns subscription or additional fees?
The cost of using Acorns Early can depend on the Acorns plan, location, account type, and features selected by the parent. Some family or children’s features may be included with an eligible subscription, while others may require a paid plan or have specific conditions. Check the latest pricing information in the official app listing and Acorns’ terms before creating an account.
Can children receive, save, or invest real money through Acorns Early?
The app may support family money features such as allowances, savings goals, or other account-related tools, but the exact options depend on the current product, the parent’s account, and legal eligibility. Investment features can involve risk and are not the same as a guaranteed savings account. Parents should verify how money is held, transferred, or invested before enabling any financial feature.











