UKG Wallet
4.5BusinessUpdated October 2, 2026
Screenshots
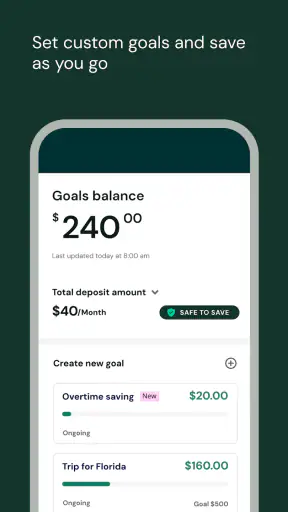
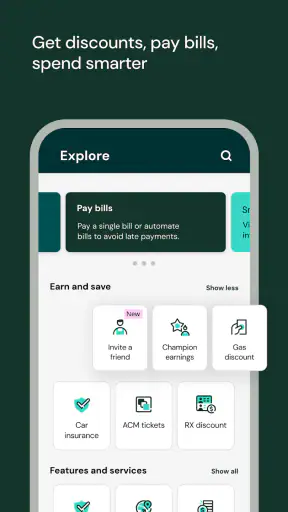
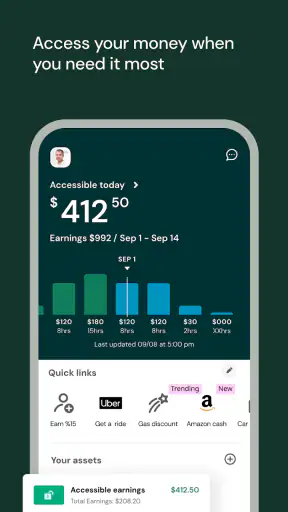
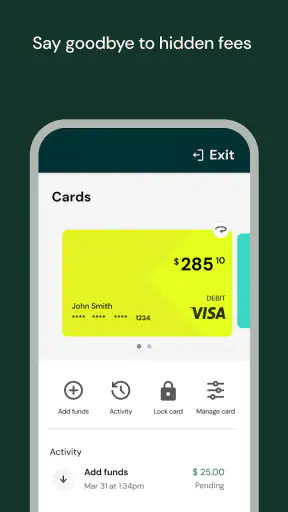
Pros
- Centralizes pay
- tax
- and benefits information in one place.
- Useful notifications can highlight important payroll or HR updates.
- Supports access to workplace resources while away from a computer.
- Secure sign-in options help protect sensitive employment information.
- Clean layout makes common account details easy to locate.
Cons
- Most features require an employer using compatible UKG services.
- Some functions may be unavailable depending on company settings.
- Payroll information can be delayed until the employer publishes updates.
- A stable internet connection is needed for most account actions.
- Support options may direct users to their employer rather than UKG.
 Analysis By Mobexer
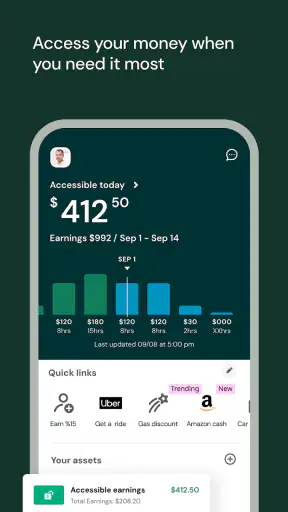
Getting access to money you have already earned can be useful when an unexpected bill arrives before payday, and that is the central reason I would consider UKG Wallet. This free business app from UKG, Inc. is designed around earned-wage access rather than general budgeting, banking, or payroll management. In my experience, that distinction matters: it can be a practical bridge between work already completed and the date your regular paycheck arrives, but it is not a complete replacement for a bank account or a full personal-finance app.
The app has a 4.5 average from around twelve thousand ratings, with roughly two thousand written reviews and over one hundred thousand installs. Those figures suggest that it has found a real audience among employees whose workplaces support its service. It is rated for Everyone, and the current release is version 1.0.25 for devices running Android or iOS equivalent to operating system version ten or newer. The basic download is free, which makes it easy to try if your employer uses the UKG system and gives you access.
How UKG Wallet fits into everyday pay management
The baseline workflow is simple, but eligibility comes first
The first thing I would do is treat UKG Wallet as an extension of an existing employment and payroll setup, not as a standalone money app. The important question is not simply whether the app installs on your phone. It is whether your employer has enabled the relevant UKG Wallet service for your workplace and whether your earnings are visible inside the account. If those pieces are not in place, the app cannot provide the same value it offers to an eligible employee.
Once access is available, the basic routine is easy to understand. I would open the app when I need to check what earned wages are available, decide whether taking some of that money now is worthwhile, and use the regular payroll schedule for the rest. That creates a useful separation between money already earned and money I am still expecting to earn. It is a healthier way to think about the feature than treating the available balance as extra income.
A realistic example would be a household bill that falls due a few days before payday. Instead of relying on an overdraft or putting the expense on a credit card, an eligible worker could check UKG Wallet and see whether earned wages are available for access. If the amount is enough, the app may offer a way to handle the short gap using pay connected to completed work. I like this use case because it is specific and controlled: the tool is most helpful when it solves a timing problem, not when it encourages routine spending beyond a person’s normal income.
I would also build a habit of checking the app after a shift pattern changes, overtime is recorded, or a pay period is nearing its end. The balance shown in a wage-access app should be treated as a working figure connected to payroll activity, not as a permanent account balance. A quick check before making a decision helps prevent confusion between wages that have been earned, wages that have been requested, and the amount that will arrive through the normal payroll process.
What I would check before relying on an early wage request
My first practical rule would be to compare the amount I want to access with the bill that created the urgency. Taking only what is needed reduces the chance of making the next regular paycheck feel unexpectedly small. This is one of the most important habits with any earned-wage product: convenience can hide the fact that an earlier withdrawal changes the cash flow later in the pay cycle.
I would also keep a simple note of any amount accessed and the date. That is not because the app is necessarily difficult to use; it is because personal records make payroll questions easier to resolve. If the next payslip looks different from what I expected, I can compare it with my own record instead of trying to reconstruct several decisions from memory. UKG Wallet can help with access, but a small personal tracking habit still gives me better control.
Another useful distinction is between an emergency and a recurring shortage. If I needed early access once to cover a one-off timing issue, the app could be a sensible tool. If I needed it every pay period for groceries, rent, or utilities, I would see that as a warning that my monthly budget needs attention. In that situation, a traditional budgeting app, a conversation with payroll, or a review of fixed expenses may be more helpful than repeatedly moving payday forward.
Settings and account details worth checking
I would spend a few minutes reviewing the account and notification settings before using the service under pressure. The goal is not to change everything, but to make the app fit the way I actually manage money. Notifications can be useful when I need timely information about activity, while unnecessary alerts can become background noise and make important messages easier to miss.
It is also worth checking that the employment information and account details shown in the app are current. A worker who has changed jobs, moved between locations, or experienced a payroll update should not assume that an old connection will automatically reflect every change. If something looks wrong, I would pause before requesting access and contact the appropriate workplace or payroll support channel rather than guessing.
Security deserves the same attention as convenience. I would use a strong device passcode, keep the phone’s operating system updated, and avoid opening a financial app on a shared device without protection. I would also be careful with messages that ask for login information or direct me to unusual pages. UKG Wallet may be an employee benefit tool, but it still handles information connected to earnings, so the normal precautions for financial services apply.
One setting-related habit I find especially useful is separating “information I want immediately” from “information I can review later.” If the app allows notification choices on the device, I would keep meaningful account activity visible while reducing distractions. That makes the app more useful as a quick check-in tool instead of something that constantly interrupts the day.
Faster patterns for repeat users
After the first few uses, I would create a repeatable decision process. Before opening the app, I would answer three questions: what bill am I covering, how much do I actually need, and what will the next regular paycheck need to cover? This takes less time than making an emotional decision in the middle of a cash-flow problem, and it keeps the app connected to a plan.
I would also check the app at a consistent point in my work-and-pay routine rather than opening it repeatedly throughout the day. For example, reviewing it after recorded work has been updated gives me a clearer picture than checking immediately after every shift. The exact timing depends on the employer’s payroll process, but the principle is the same: fewer, more deliberate checks are easier to understand and less likely to turn available wages into impulse spending.
Another efficient pattern is to use UKG Wallet for a defined category of short-term needs. I might reserve it for an urgent utility payment or a necessary repair, while keeping ordinary discretionary purchases on my regular budget. That boundary makes it easier to judge whether the service is helping. If every type of spending starts to depend on early access, the convenience is no longer solving a narrow problem.
I would avoid treating the displayed availability as a forecast of my final paycheck. Work hours, payroll timing, deductions, and employer processes can affect what reaches the normal pay cycle. The safer workflow is to use the app for a modest, clearly understood amount and leave room for normal deductions and recurring commitments. This is a small behavioral rule, but it is more valuable than any shortcut because it protects the next pay period.
Where the app is stronger than usual alternatives
Compared with a standard budgeting app, UKG Wallet addresses a different problem. A budgeting tool can show where money goes, categorize expenses, and help plan ahead, but it generally does not solve the immediate gap between completed work and payday. UKG Wallet is more direct for that particular situation because its purpose is tied to earned wages rather than a manually entered budget.
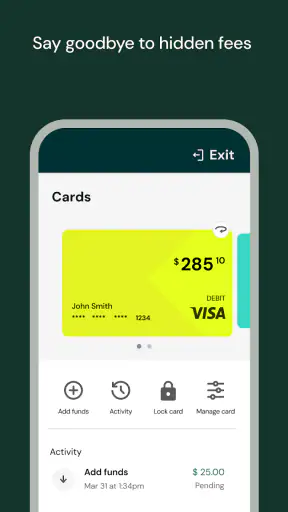
Compared with a credit card or overdraft, the appeal is that the user is working with wages already earned instead of borrowing against a credit limit. That can make it a less complicated option for a short timing issue, especially when the alternative would be a high-cost or stressful form of debt. Still, the practical result is not “free extra money.” Accessing wages early changes what remains for the regular payday, so the comparison should include future cash flow, not just the ease of the first transaction.
Compared with checking a payroll portal, the value is convenience around earned-wage access rather than merely viewing a payslip. A payroll system remains the better place to verify official pay information and employment records. I would use UKG Wallet for the immediate decision and the payroll system for formal confirmation when something affects my paycheck or employment details.
The app is therefore best for employees who want a focused tool connected to their workplace. It is less suitable for someone looking for investment tools, detailed spending analytics, bill negotiation, savings automation, or a complete digital bank. Installing it will not turn a short-term wage-access feature into an all-purpose financial command center, and expecting that would lead to disappointment.
Advanced limits and points where I would slow down
The biggest limitation is that the experience depends on the employer relationship. A person can download a free app, create interest in the feature, and still find that the practical usefulness depends on workplace participation and the way payroll information is made available. That is not a flaw I would judge in the same way as a broken interface, but it is a real boundary around who can benefit.
There is also a psychological limit. Seeing earned wages available on a phone can make money feel more accessible than it really is in a monthly budget. I would be particularly cautious if my rent, loan payments, or household expenses are timed around the normal paycheck. Early access may solve today’s problem while creating a larger problem later, especially when used without recording the amount.
For users who need formal payroll corrections, tax documents, or a definitive explanation of deductions, I would not rely on the wallet view alone. Those questions belong with the employer’s payroll process. Similarly, anyone who needs a long-term plan for debt reduction or saving should pair this app with a proper financial routine rather than expecting earned-wage access to provide one.
Device compatibility is another practical checkpoint. The app supports devices using operating system version ten or later, so anyone on an older phone should check compatibility before planning around it. The rating for Everyone makes it broadly approachable from an age-classification perspective, but workplace eligibility and responsible money management matter more than the age label in deciding whether it is appropriate.
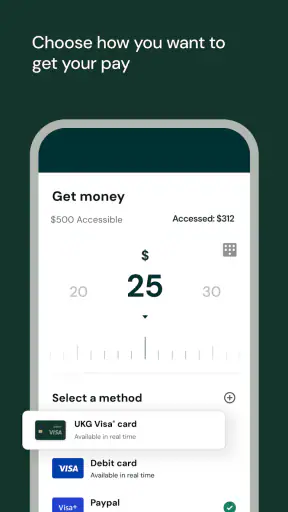
I would also avoid making a request while distracted or rushed. The most useful advanced habit is to read the amount carefully, confirm the destination and timing shown in the app, and then record what was done. A few extra seconds can prevent the common mistake of selecting an amount based on the total visible balance rather than the smaller amount actually needed.
Who should use it, and who should choose something else
I would recommend UKG Wallet to an employee whose workplace supports it, who occasionally faces a short gap before payday, and who is comfortable tracking early access as part of the next paycheck. It can be especially useful for people with variable work schedules who want a clearer view of wages associated with work already completed. The strongest fit is someone who uses it selectively and has a plan for the following pay period.
I would be more cautious recommending it to someone already depending on each paycheck for essential expenses. In that case, repeated early access can conceal a structural budget problem. A budgeting tool, a savings cushion, or direct help from an employer or financial counselor may offer a better long-term answer. Someone seeking a complete banking experience should also look elsewhere, because the app’s focus is much narrower.
My final assessment after using the workflow
UKG Wallet is a focused business app with a clear purpose: helping eligible employees access earned wages before the usual payday. I appreciate that its usefulness is easy to understand when a real timing problem appears, and the free price removes one barrier to trying it. UKG, Inc. has positioned it as a practical workplace tool rather than a broad personal-finance platform, and that limited scope is both its strength and its main constraint.
My advice is to install it only with a specific routine in mind. Check the account after work information is updated, request no more than the immediate need, keep a personal record, and compare the decision with the obligations due on the next normal payday. Those habits turn a tempting balance into a controlled option.
The best way to use UKG Wallet is as a safety valve, not as a second paycheck. For the right employee, it can reduce the need for credit when money and payday do not line up. For someone looking for budgeting, savings, payroll administration, or everyday banking in one place, another app will be a better match. I would recommend it selectively, with the clearest praise reserved for its narrow but genuinely useful role.
FAQ
What is UKG Wallet and what does it do?
UKG Wallet is a financial wellness feature connected with participating UKG workforce and payroll systems. It can give eligible employees access to earned wages before the regular payday, while also providing tools for viewing pay information and managing withdrawals. The exact services available depend on the employer’s UKG setup, payroll configuration, location, and employee eligibility.
Can everyone use UKG Wallet, or does my employer need to support it?
UKG Wallet is not generally available as a standalone banking app for everyone. Access normally depends on whether your employer has enabled the service through a compatible UKG solution and whether your employee account meets the required conditions. After downloading or opening the app, you may need to verify your identity and connect through your employer’s approved UKG credentials.
How quickly can I receive money through UKG Wallet?
The timing of a withdrawal depends on the delivery method, payroll processing schedule, bank or card network, weekends, holidays, and your employer’s configuration. Some transfers may arrive quickly, while standard bank deposits can take longer. Before confirming a transaction, carefully review the estimated arrival time, available balance, and any applicable fees shown in the app.
Does using UKG Wallet affect my normal paycheck or taxes?
Using an earned-wage feature generally means receiving part of wages you have already earned before the normal payday, so the amount accessed may be deducted from your upcoming paycheck. It does not automatically increase your total earnings. Payroll deductions, tax treatment, limits, and reporting can vary, so review the in-app disclosures and contact your employer’s payroll or HR department if you are unsure.
Is UKG Wallet safe, and what should I do if I lose access?
UKG Wallet may use account authentication, identity verification, encryption, and security controls to help protect personal and payroll information, but users should still use a strong password, enable available security features, and avoid sharing login codes. If your phone is lost, your account is compromised, or a transaction looks unfamiliar, contact your employer’s UKG administrator or official support promptly.