Snap Finance
4.8ShoppingUpdated October 2, 2026
Screenshots
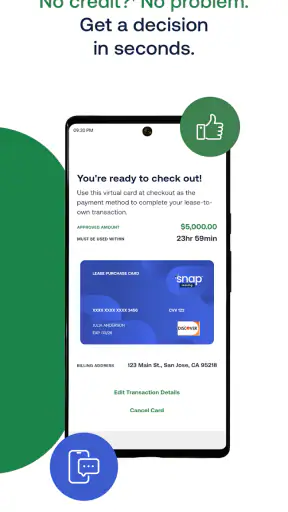
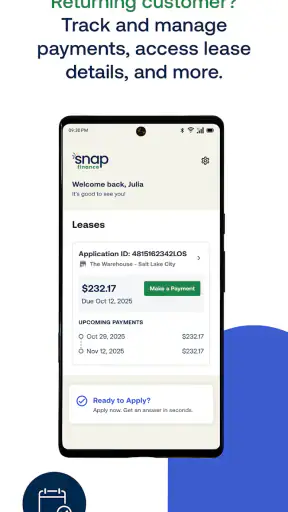
Pros
- Fast application process with minimal paperwork required.
- May help finance purchases when traditional credit is unavailable.
- Clear repayment schedules make payment planning easier.
- Available for qualifying purchases at participating retailers.
- Online account access helps track balances and upcoming payments.
Cons
- Approval does not guarantee favorable terms or a high spending limit.
- Interest and fees can make financed purchases considerably more expensive.
- Late payments may lead to penalties and negatively affect your credit.
- Usability depends on retailer participation and purchase eligibility.
- Some users may receive promotional terms that later change or expire.
 Analysis By Mobexer
When an unexpected purchase cannot wait, I find myself asking a more important question than “Can I get it today?” I ask whether the payment plan will still feel manageable after the excitement of the purchase fades. Snap Finance is built around that decision. It is a free shopping app from Snap Finance that lets eligible shoppers look for a way to shop now and pay later, with no traditional credit requirement presented as the starting point. In my experience, its value is less about browsing for entertainment and more about giving a planned purchase another payment route.
I would describe it as a financing-focused shopping companion rather than a general marketplace. That distinction matters. You are not opening it simply to compare every product on the internet or to replace a favorite retailer’s app. You are opening it when the payment method is part of the purchase decision. That makes it particularly relevant for people facing a necessary household expense, replacing an important item, or trying to divide a larger checkout into scheduled payments.
The app sits in the Shopping category and is rated for Everyone, which makes the presentation approachable for a broad audience. It was released on March 29, 2023, and the current version is 2.2.11632, with support beginning at Android 7.0. Those details make it accessible to many existing Android users, although compatibility is still worth checking before planning a purchase around it.
How I Decide Whether Snap Finance Is the Right Fit
Start with the purchase, not the payment promise
My first test is simple: would I still want or need the item if paying over time were not available? If the answer is no, I would not use Snap Finance to justify the purchase. A payment option can make a product feel easier to afford without making the underlying expense smaller. The app is most useful when it helps organize a purchase I have already considered, not when it encourages an impulse decision.
I also look at whether the item is urgent, practical, and likely to remain useful throughout the repayment period. A replacement appliance, essential furniture, or another planned household purchase can make more sense than a short-lived want. This is one of the less obvious trade-offs: the convenience of spreading payments is strongest when the value of the item lasts longer than the payment schedule.
Understand what “no credit needed” means in practice
The phrase attached to Snap Finance is appealing because it speaks to shoppers who may not have a conventional credit history or who would rather avoid making a traditional credit application the center of the process. I would still treat it as a financing decision, not free money. Before accepting anything, I would read the full payment terms, check the total amount owed, and confirm the timing of each payment.
This is also where I would slow down if my budget is already tight. A plan that looks comfortable on its own can become difficult when combined with rent, utilities, subscriptions, and other installment commitments. The app may open a door for shoppers who have fewer ordinary credit options, but it does not remove the need to judge affordability carefully.
Separate app convenience from approval expectations
Another sensible criterion is whether I am comfortable with the possibility that the final shopping experience depends on eligibility and the terms shown during the process. I would not assume that every purchase, merchant, or situation will work in exactly the same way. The practical question is not just whether the app is available on my phone; it is whether the financing route offered for my intended purchase fits my budget.
That makes Snap Finance different from paying with cash or a standard debit card. With those options, the main decision is whether I have enough money now. With this app, I also need to understand the future commitment. I would keep the purchase details nearby, review the agreement before confirming, and avoid treating an initial estimate as the final cost.
Use the app as a checklist before checkout
One of my favorite ways to approach a financing app is to turn it into a short checklist. I would decide the highest amount I am genuinely willing to spend, identify the item that solves the problem, and then compare the offered repayment plan with my normal monthly budget. If the plan only works when nothing unexpected happens, it is probably too aggressive.
I would also ask whether a short delay could let me save enough to pay directly. That comparison is easy to overlook because installment payments feel smaller than one full payment. Yet paying from money already set aside can be simpler and may avoid the administrative effort of tracking another commitment. Snap Finance is more compelling when waiting is impractical or when the payment arrangement has a clear, comfortable place in my budget.
What I noticed about the app’s position in the market
Snap Finance has built a substantial audience for a relatively recent Android release: it has passed half a million installs, carries an average rating of 4.8 from roughly 9,200 ratings, and has 818 written reviews. I see those figures as evidence that many people find the basic idea useful, but not as a substitute for reading the terms of an individual offer. Ratings describe the broad app experience; they cannot decide whether a particular repayment plan is sensible for me.
The free download also lowers the barrier to exploring the service. I can investigate the process without paying for the app itself. Still, “free” should be understood as the app’s price, not automatically as the total cost of every financed purchase. That distinction is central to using it responsibly.
Where it wins for shoppers with a specific problem
The strongest part of Snap Finance is focus. If I already know that I need a purchase and conventional credit is not a comfortable or realistic route, the app puts the payment question near the front of the experience. That can be more useful than a general retailer app that shows products beautifully but gives me little help deciding how the purchase will fit into my finances.
I also like the psychological clarity of separating shopping from everyday spending. A debit card removes money immediately, while a financing arrangement creates a schedule that I can examine before committing. For some shoppers, that structure is easier to plan around than a single large withdrawal. The benefit depends entirely on following the schedule, but the app’s purpose is well matched to that kind of planning.
A realistic everyday scenario
Imagine that my washing machine stops working during a busy week. I have compared replacement options, know the basic features I need, and cannot comfortably pay the entire amount today. In that situation, I would use Snap Finance to explore whether the available payment route makes the replacement manageable. I would write down the total repayment amount, the first payment date, and every later due date before accepting anything.
I would then compare that commitment with my next several pay cycles. If the schedule leaves enough room for groceries, transport, bills, and a small emergency cushion, the app could be a practical bridge. If it only works by postponing another essential bill, I would stop and look for a cheaper model, a used option, a retailer-specific plan, or a way to wait. The app helps me evaluate the purchase; it cannot make an unaffordable one affordable.
Three practical habits that improve the experience
- Set a personal ceiling before opening the shopping flow. I would decide the maximum total I can accept, rather than letting the size of each installment determine my budget.
- Save the repayment dates in the same place as my other bills. This reduces the risk of forgetting a payment simply because it is connected to a shopping purchase rather than a regular utility.
- Compare the full repayment with paying directly. The smaller scheduled amount is not the only figure that matters; the complete obligation is the better basis for a decision.
- Keep the purchase narrow. If the app makes several add-ons feel manageable, I would return to the original need and remove anything that was not part of the plan.
These habits are not flashy features, but they make a meaningful difference. The app is easiest to misuse when I focus on the immediate checkout and ignore the later calendar. Treating it as a budgeting decision tool, rather than a permission slip to spend, brings out its practical strength.
Where the experience may feel less comfortable
The same focus that makes Snap Finance useful can make it feel limited for shoppers who want a full retail discovery experience. I would not choose it as my main destination for comparing broad product ranges, reading extensive independent buying advice, or managing every purchase from multiple stores. Its role is tied to financing and shopping access, so people who already have a preferred payment method may find an ordinary retailer app more direct.
There is also a mental cost to adding another payment commitment. Even when the app is easy to use, I still have to monitor the agreement and remember that the purchase continues after the delivery or collection is complete. Someone who prefers a clean, one-time transaction may be better served by saving first or using money already available.
When a different category of alternative is better
If I have enough savings, paying directly is usually the simplest alternative. It avoids another schedule and makes the final cost easy to understand. If I already use a bank card with terms I know well and a repayment plan that fits my budget, that familiar option may be more convenient. The important point is not that one category is always superior; it is that each one solves a different problem.
A retailer’s own payment service can also be a better fit when I am buying from one store repeatedly and want all order history, returns, and payment information together. A general shopping marketplace may be preferable when product choice, seller comparison, and reviews matter more than financing access. Snap Finance stands out when the payment route is the reason I am looking for help in the first place.
I would be especially cautious if I am considering the app for a nonessential purchase that I cannot comfortably cover. In that case, the better alternative may be postponing the purchase, choosing a less expensive item, or building a small savings buffer. No shopping interface, however convenient, changes the risk of committing future income.
What switching to Snap Finance involves
Moving from a normal checkout to a financing-centered app changes my routine in several ways. I need to understand the agreement, keep track of scheduled payments, and preserve records of the purchase. That is the real cost of switching: not the free download, but the extra attention required after checkout.
For a one-off emergency purchase, that effort may be worthwhile if it prevents a serious disruption. For frequent small purchases, it can become harder to manage several separate obligations. I would therefore avoid using the service casually across unrelated shopping trips. Keeping it for purchases with a clear purpose makes the arrangement easier to remember and evaluate.
There is also a switching cost in habits. If I am used to judging affordability by the amount in my account today, I must start judging it by the money that will remain available over future pay periods. I would only make the change if I am willing to maintain that discipline. Otherwise, the familiar simplicity of direct payment is a genuine advantage, not a missed opportunity.
Device access and practical expectations
Android users with version 7.0 or later can consider the app within its stated operating-system range. Because the current release is 2.2.11632, I would keep the app updated when possible and make sure my phone has enough room for normal app updates. I would also use a secure device and review every screen before confirming a financial commitment, especially if someone else occasionally uses my phone.
The Everyone age rating makes the app’s general presentation suitable for a broad audience, but that should not be confused with every financing decision being suitable for every person. Younger users and anyone unfamiliar with installment agreements should involve a trusted adult or financially experienced person before accepting a commitment. Clear understanding matters more than the simplicity of the interface.
Questions I would answer before accepting a plan
I would want to know the total amount I will repay, the exact timing of payments, and what happens if my budget changes. I would also check whether the item can be returned through the normal retailer process and how that interacts with the payment arrangement. These are practical questions because returning a product does not automatically mean every financial step is instantly resolved.
I would keep confirmation details and receipts until the purchase and payment schedule are fully finished. If I expect to move, change bank accounts, or experience an irregular income period, I would consider those events before committing. The app may make the initial step convenient, but my responsibility continues beyond the first approval or checkout screen.
Finally, I would ask myself whether I am choosing Snap Finance because it genuinely solves a timing problem or because it makes an unaffordable item look harmless. That single question filters out many poor decisions. It also explains why I would recommend the app to some friends without recommending it for every shopping situation.
My recommendation
I recommend Snap Finance to shoppers who have a real, considered purchase, need an alternative to conventional credit, and are prepared to track the full repayment obligation. Its free access, broad Android compatibility, and strong user response make it worth investigating when spreading the cost is part of a sensible plan. The developer, Snap Finance, has kept the product’s purpose clear: connect shopping with a payment option for people who may not want or have access to traditional credit.
I would not recommend opening it simply to increase spending power. I would also steer away from it if I already have a straightforward way to pay, if I dislike managing multiple due dates, or if my current budget has no room for another commitment. In those cases, paying directly, saving first, choosing a cheaper item, or using a familiar retailer option may be better.
My final view is positive but careful. Snap Finance can be useful precisely because it addresses a specific obstacle rather than pretending every shopper needs the same solution. I would use it with a written budget, a clear purchase limit, and a full reading of the terms. The best reason to choose it is controlled flexibility, not permission to spend more. Used that way, it is a practical shopping app for a defined situation; used casually, it can make future expenses easier to overlook.
FAQ
What is Snap Finance, and how does it work?
Snap Finance is a consumer financing service that allows eligible shoppers to apply for payment options when purchasing products from participating retailers. Instead of paying the full amount immediately, approved customers may repay the balance over time according to the terms shown in their agreement. Approval, available spending limits, fees, and repayment schedules can vary, so users should review the complete offer carefully before accepting it.
Can I apply for Snap Finance through the mobile app?
Depending on your location and the retailer involved, Snap Finance services may be accessed through a participating merchant’s website, checkout process, or mobile experience rather than through a standalone application. Applicants generally provide personal and financial information for identity verification and eligibility assessment. Before downloading anything, confirm that you are using an official Snap Finance source or an authorized retailer and avoid unofficial apps requesting sensitive information.
Does using Snap Finance affect my credit score?
The effect on your credit can depend on the product, application process, and applicable terms in your region. Some financing applications may use alternative approval methods, but that does not automatically mean there will be no credit-related consequences. Late or missed payments can result in additional costs and may affect your financial record. Read the disclosures carefully and contact Snap Finance if the agreement is unclear.
What fees and repayment terms should I check before accepting financing?
Before accepting a Snap Finance offer, examine the total amount you will repay, payment frequency, contract duration, interest or equivalent charges, late-payment fees, and any other applicable costs. A product that appears affordable through small installments may cost considerably more over the full term. Also check whether early repayment is allowed without penalties and make sure the scheduled payments fit comfortably within your budget.
Is Snap Finance safe to use, and what should I do if I have a problem?
Snap Finance can be used safely when accessed through official channels and when customers understand the financing agreement before signing. Protect your account details, never share verification codes, and check that websites use the correct company domain. If you notice an unauthorized transaction, suspicious message, billing error, or difficulty making a payment, contact official customer support promptly and keep copies of your agreement and communications.