Qualifier Plus IIIx
4.8BusinessUpdated October 2, 2026
Screenshots
Pros
- Handles advanced scientific calculations with complex numbers and matrices.
- Supports customizable formulas
- constants
- and frequently used functions.
- Clear multi-line display makes long calculations easier to review.
- Useful for engineering
- physics
- mathematics
- and technical coursework.
- Works offline
- so calculations remain available without an internet connection.
Cons
- The interface can feel dated compared with newer calculator apps.
- Its extensive functions may overwhelm users seeking only basic calculations.
- Entering complex expressions takes practice on a small mobile keyboard.
- Some advanced features require checking the manual or built-in help.
- Not ideal for users who prefer natural-language or graph-based math tools.
 Analysis By Mobexer
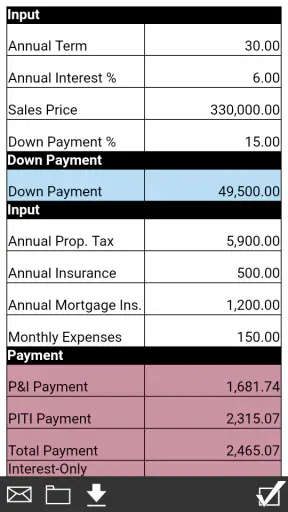
I found Qualifier Plus IIIx most useful when I treated it as a focused mortgage-work tool rather than a general finance app. It is built for one job: helping you work through mortgage payment calculations without reaching for a paper worksheet or a much larger spreadsheet. In my experience, that narrow purpose is also its biggest strength. It keeps attention on the loan figures, but it means the app is less suitable if you want budgeting, property research, document storage, or a complete home-buying dashboard in one place.
Developed by Calculated Industries, this free Business app has earned a 4.8 average from over 300 ratings and has passed 10 thousand installs. Those figures suggest a small but clearly satisfied audience, and my impression matches that: it feels designed for people who already understand why mortgage calculations matter and want a dependable calculator close at hand. It is available for Everyone, runs on Android 6.0 or later, and the current version is 10.4.11. Optional in-app purchases range from 49 cents to $29.99 per item, so I would check the available functions and purchase prompts before assuming every part of the experience is included.
Where the first calculations can go wrong
The main difficulty is not downloading the app. It is entering the right kind of number in the right place. Mortgage questions often mix purchase price, down payment, loan amount, interest rate, term, taxes, insurance, and payment frequency. If I type a figure without first deciding what it represents, the result can look perfectly reasonable while answering a different question from the one I intended to ask.
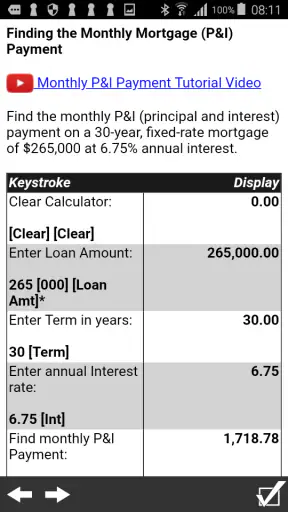
My first practical rule is to write down the question in plain language before opening the calculator. For example, “What would the principal-and-interest payment be if I borrow this amount at this rate for this term?” is much safer than beginning with a property price and tapping through fields from memory. Once the basic payment is clear, I can separately consider taxes, insurance, association charges, or other ownership costs. That separation prevents me from mistaking a loan payment for the entire monthly cost of a home.
Another common sticking point is confusing the purchase price with the amount borrowed. A down payment changes the loan balance, so entering the full property price when the question concerns the financed amount will inflate the result. Conversely, entering only the down payment gives a deceptively small payment. I recommend calculating the financed amount on paper first, then entering that figure deliberately rather than trying to make several changes at once.
Interest rates also deserve a careful pause. A rate is not the same thing as a dollar amount, and a small decimal-entry mistake can change the result dramatically. I check whether I am entering the annual rate in the format the calculator expects, then compare the output with a rough mental estimate. I do not need to reproduce the calculation manually; I only need to notice an implausible result before using it in a conversation with a lender or seller.
Loan term is another easy source of confusion. A shorter term generally means a higher regular payment and less interest over the life of the loan, while a longer term usually lowers the regular payment but extends repayment. If the result seems unexpectedly high or low, I recheck the term before blaming the app. People often switch between years and months in their notes, and that simple mismatch can explain more problems than a software fault.
What I check before trusting an answer
I use a small setup routine every time I start a new scenario. First, I identify whether I am testing a new loan, comparing an alternative loan, or revisiting an existing balance. Second, I keep the property price, down payment, loan amount, rate, and term in a separate note. Third, I enter one scenario at a time and record the result before changing a field. This takes less effort than trying to remember which value I changed after several taps.
The most useful habit is to preserve the question alongside the result. A payment number without its rate, term, and loan amount is not a meaningful comparison. When I compare two homes or two financing options, I label each result in my notes instead of relying on memory. That makes the app useful during a viewing, a phone call, or a later discussion at home, when several similar numbers can otherwise blur together.
I also avoid treating the displayed payment as a promise. A mortgage calculator can help me understand a scenario, but the final figure from a lender may reflect details that are not part of a simple payment calculation. Depending on the situation, fees, insurance arrangements, taxes, loan structure, and lender requirements can affect the amount I actually need to budget. Qualifier Plus IIIx is valuable for exploration and comparison; it should not replace a formal loan estimate or professional advice.
Making the app fit a real buying decision
A realistic use case is a buyer comparing two properties with different prices and down-payment requirements. I would calculate the loan payment for the first property, write down the assumptions, then start a fresh comparison for the second. After that, I would add the non-loan costs outside the app using a separate note or household budget. This produces a more honest monthly picture than choosing the property with the lower calculator result alone.
The same approach works for a refinancing conversation. I can compare the proposed balance, rate, and term with the existing loan assumptions, then ask whether the payment change is large enough to justify the broader costs and commitment. The important insight is that a lower payment does not automatically mean a better deal. Extending the repayment period may reduce the monthly burden while increasing the time spent paying interest. The calculator helps expose the payment difference, but I still need to judge the trade-off.
For a real-estate professional, the app can be handy during an early conversation when a client asks, “What might this cost each month?” I would use it to create a quick illustration, clearly label it as an estimate, and avoid presenting the number as a guaranteed approval result. For a homeowner, it can support a what-if exercise: changing the loan amount, rate, or term one at a time makes it easier to see which assumption has the greatest effect.
One less obvious benefit of this workflow is that it reduces emotional decision-making. When I am looking at a home I like, I can be tempted to focus on the purchase price or the headline payment. Running a few consistently labeled scenarios makes the comparison more concrete. I can see how much the down payment changes the borrowing need, how a different term affects the regular payment, and whether the remaining budget still feels comfortable after ordinary household expenses.
Recovering when a result looks wrong
When the output surprises me, I do not immediately clear everything and start tapping randomly. I work backward from the result. I recheck the loan amount, interest rate, and term first because those are the assumptions most likely to explain a major difference. Then I confirm that I did not accidentally carry over a value from a previous scenario. A calculator is only as clear as the inputs I give it, and mortgage comparisons encourage repeated editing.
If I am unsure whether a field contains the value I intended, I restart the scenario in a controlled way. I keep the original figures visible in my notes, enter them again slowly, and record the new result. Comparing the two outcomes tells me whether the problem was an input mistake or a broader issue. This is safer than changing several values together, because multiple changes make it impossible to identify what fixed the calculation.
It is also worth checking the app environment before assuming the calculation engine failed. I make sure the app is installed on a supported Android device, since the stated minimum is Android 6.0. If the interface behaves oddly, I close and reopen it, then repeat a simple calculation. If the same issue continues, I check whether the app needs an update through the official app store and confirm that I have enough device storage for ordinary app operation. These are basic steps, but they often separate a temporary display problem from an incorrect financial assumption.
I keep screenshots or written notes only after verifying the assumptions. Saving a wrong result gives it an undeserved sense of authority, especially when I return to it days later. My preferred record includes the loan amount, rate, term, date of the scenario, and what the result represents. That small amount of context makes the calculation reusable and helps me explain it to someone else without reopening the app and guessing what I entered.
Another useful recovery technique is to use a known, simple scenario as a test. I enter a clearly defined loan example with round figures and check whether the app produces a stable result when I repeat it. I do not use that test to prove the app is universally correct, but it can reveal whether my difficulty comes from the current set of inputs. If the simple test works and the original scenario does not, I return to the original figures and inspect them one by one.
When the app is not the cause
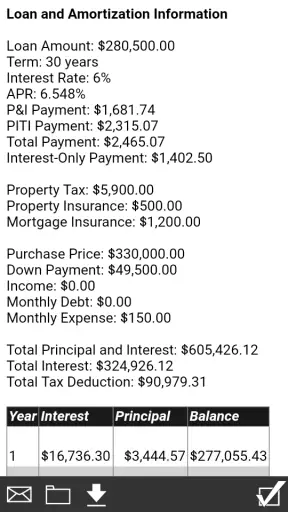
Some disagreements are caused by comparing different definitions of “payment.” One person may be discussing principal and interest, while another is quoting a broader monthly housing cost. Taxes and insurance can make the second figure much higher even when both people are using the same loan amount and rate. Before deciding that Qualifier Plus IIIx is wrong, I ask what each number includes.
Rounding can create a smaller difference as well. A lender’s documents may show rounded monthly amounts, while a calculator may retain more precision during the calculation and display the result differently. That does not necessarily indicate a meaningful financial disagreement. I focus first on whether the assumptions match, then on whether the difference is material enough to affect the decision.
Loan structure can be the bigger issue. A straightforward payment calculation may not capture every feature of a specialized loan, changing-rate arrangement, unusual repayment schedule, or fee structure. If the loan being discussed has conditions that are not represented by the assumptions I can enter, I use the app only for a rough reference and rely on the lender’s documents for the official figures. This is one of the clearest situations where a spreadsheet or professional estimate is the better tool.
I would also skip this app if my main goal is full financial planning. It does not replace a household budget, a debt payoff plan, a property-tax estimate, or a document organizer. Someone who wants charts, long-term cash-flow projections, shared financial records, and detailed scenario management may be happier with a spreadsheet or a broader personal-finance app. The trade-off is that those alternatives usually require more setup and can make a quick mortgage question feel unnecessarily complicated.
On the other hand, a general calculator may be too limited for someone who regularly works with mortgage scenarios. Qualifier Plus IIIx makes more sense when the mortgage calculation itself is the priority and I want a dedicated tool rather than a blank spreadsheet. The choice depends on whether I value focused access or a wider financial workspace. For occasional home shoppers, a lender’s calculator may be sufficient; for repeated comparisons, a specialized app can be more convenient.
Small workflow choices that improve accuracy
I avoid changing the rate, term, and loan amount simultaneously unless I am intentionally modeling a completely new offer. Varying one assumption at a time shows what actually drives the payment. For example, I might hold the loan amount and term steady while testing rate changes, then return to the original rate and test a different term. This produces a clearer comparison than comparing two scenarios with every input changed.
I also calculate the effect of a larger down payment separately from the effect of a lower purchase price. They may reduce the loan amount in similar ways, but they represent different decisions for my cash reserves and buying strategy. A lower loan balance can improve the payment result, yet using too much available cash for the down payment may leave less room for moving costs, repairs, emergencies, or other ownership expenses. The app helps with the payment side; my broader budget must handle the cash-reserve question.
For conversations with other people, I round only after I have recorded the calculator’s displayed result. I can say “about this much per month” in a casual discussion, but I keep the original figure and assumptions in my notes. This avoids false precision while preserving enough detail to repeat the scenario later. It is a simple distinction, but it makes the app’s output easier to communicate responsibly.
I pay attention to what a result is useful for. A single payment is good for an initial affordability check, while a set of consistently prepared scenarios is better for comparing choices. The app becomes much more useful when I treat it as a question-answering tool: What changes if the rate moves? What happens if I borrow less? How does the term affect the regular payment? Those questions lead to better decisions than asking for one isolated number and accepting it without context.
Who should use it and who should look elsewhere
I would recommend Qualifier Plus IIIx to a buyer who wants a direct way to examine mortgage payment scenarios, a homeowner preparing for a refinancing discussion, or a professional who needs a focused calculation tool during early conversations. Its free entry point makes it easy to try, and the strong average rating indicates that many users find the approach useful. The Everyone age rating also makes it accessible for ordinary household planning rather than limiting it to a specialist audience.
I would be more cautious about recommending it to someone who dislikes entering financial assumptions manually or expects the app to explain every part of a mortgage. The tool is most helpful when the user already knows the basic meaning of the figures and is willing to verify them. A first-time buyer who needs education about closing costs, loan eligibility, affordability, and local taxes will need additional resources alongside it.
The optional purchase range is another reason to inspect the app before building a workflow around it. The app itself is free, but some functions may involve purchases from 49 cents to $29.99 per item. I would try the free experience first, identify the exact calculation tasks I need, and only then decide whether an optional purchase is worthwhile. That approach prevents paying for capabilities I may never use.
My practical verdict after using it
Qualifier Plus IIIx succeeds because it stays close to a real mortgage question. I can open it when I want to compare a loan amount, rate, or term without setting up a full spreadsheet. The developer, Calculated Industries, has positioned it in a clearly defined Business category, and the app’s long availability since Aug 6, 2012, gives it the feel of an established utility rather than a novelty. Its current version, 10.4.11, is the one I would use when checking compatibility and deciding whether it fits my device.
My recommendation comes with one important condition: treat every result as an estimate tied to explicit assumptions. The app cannot rescue an incorrectly defined question, and it should not be used as a substitute for formal lender figures. If I record the inputs, separate principal and interest from wider housing costs, and compare scenarios methodically, it becomes a practical companion for mortgage planning.
For quick, focused payment comparisons, I would choose it over a generic calculator. For complete financial planning, detailed loan documentation, or unusual loan structures, I would choose a spreadsheet, a broader finance tool, or professional guidance instead. Its real value is not replacing those options; it is making the first mortgage conversation clearer and more concrete. That is enough to make it worth trying for anyone who regularly asks, “What would this loan payment look like?”
FAQ
What is Qualifier Plus IIIx, and who is it designed for?
Qualifier Plus IIIx is a financial calculator app designed for students, professionals, and anyone who needs to solve time-value-of-money and business-finance calculations on a mobile device. It is particularly useful for mortgage, loan, investment, cash-flow, bond, and interest-rate problems. Users familiar with the physical Qualifier Plus IIIx calculator will find the layout and functions recognizable, although beginners may need some time to learn the calculator’s financial terminology and keystroke-based workflow.
What types of financial calculations can Qualifier Plus IIIx perform?
The app is built for a broad range of financial calculations, including loan payments, amortization, present and future values, interest rates, cash flows, mortgages, bonds, depreciation, and other business-math problems. It can help compare financing options and check answers for coursework or professional work. However, the accuracy of the result depends on entering the correct values, payment frequency, compounding settings, and cash-flow signs, so users should always review the setup before relying on an answer.
Is Qualifier Plus IIIx suitable for beginners and students?
It can be suitable for students, especially those taking finance, accounting, real estate, or business mathematics courses, but it is not a simplified calculator with step-by-step lessons for every operation. The app follows the logic of a professional financial calculator, meaning users must understand concepts such as N, I/Y, PV, PMT, FV, cash-flow signs, and payment timing. Students should use the included help or a course guide while learning rather than treating every displayed result as self-explanatory.
Does Qualifier Plus IIIx work offline, and what device features does it require?
A financial calculator app such as Qualifier Plus IIIx is generally intended to perform its core calculations without a continuous internet connection, which makes it convenient for classrooms, exams, travel, or work locations with limited connectivity. It primarily requires a compatible Android or iOS device and enough storage for installation. Exact compatibility, supported operating-system versions, screen behavior, and any platform-specific limitations should be checked on the official store listing before downloading, particularly on older phones or tablets.
Are there any limitations or important things to check before downloading Qualifier Plus IIIx?
Before downloading, users should verify the app’s current price, licensing terms, supported device version, and whether all desired functions are included in the edition available for their platform. The interface may feel dense compared with ordinary calculator apps, and entering financial data incorrectly can produce misleading results. It should be used as a calculation aid rather than as financial advice. For important loans, investments, or business decisions, independently confirm the inputs and results with official documents or another reliable method.