NYC Employees PPO Plan
4.7MedicalUpdated October 2, 2026
Screenshots
Pros
- Clear overview of eligible NYC employee healthcare benefits
- Helps members understand PPO coverage and provider options
- Useful reference when comparing in-network and out-of-network care
- May simplify access to plan documents and contact information
- Supports informed decisions about medical services and costs
Cons
- Coverage details can be difficult to understand without insurance knowledge
- Out-of-network care may involve higher costs and claim paperwork
- Benefits and provider availability can change over time
- Some information may require contacting the plan administrator
- Not a substitute for personalized advice from a benefits professional
 Analysis By Mobexer
When I look at a medical app, I want one thing before anything else: a clear reason to keep it on my phone. NYC Employees PPO Plan has a narrow but useful purpose. It is the mobile companion for members of the NYC Employees PPO Plan, and access begins with receiving the member ID card. That boundary matters because this is not a general health guide, symptom checker, or replacement for a doctor’s advice. It is a plan-focused tool for people who already belong to the relevant PPO plan.
I reviewed it with that practical question in mind: would this make everyday plan-related tasks easier than relying on a physical card, a browser, or a call to customer service? My answer is yes, provided you are the intended member and approach it as an access point for your plan rather than as a complete medical-management platform. The app is free, carries an Everyone age rating, and is published by UNITED HEALTHCARE SERVICES, INC. Its store presence is still relatively compact, with over ten thousand installs, but the average rating is a strong 4.7 from around one hundred seventy ratings.
How the app fits into a shared household
The most realistic use case is not someone sitting down for a long session. It is a quick household moment: a member needs to show or check plan information before an appointment, a partner asks which card details to use, or someone is completing a health-related task while away from home. In that situation, having the plan app available can be more convenient than searching through a wallet, a drawer, or old email.
That convenience becomes more noticeable when one person in a household handles practical administration for several people. A spouse or partner may arrange appointments, help an older relative prepare for a visit, or keep track of which information needs to be available when contacting a provider. The app can support that coordination when the member is present and willing to share the relevant screen or information. I would not treat it as a shared household dashboard, though. Its starting point is individual member access, so the person whose plan it is should remain the center of the process.
On a shared phone or tablet, I would use it deliberately rather than leaving it open for everyone. Medical and insurance information deserves the same care as banking details. If another household member needs to help, I would hand over the device only for the specific task, then close the app afterward. That is not a criticism of this particular product; it is simply the sensible way to handle a plan-related account on a device used by several people.
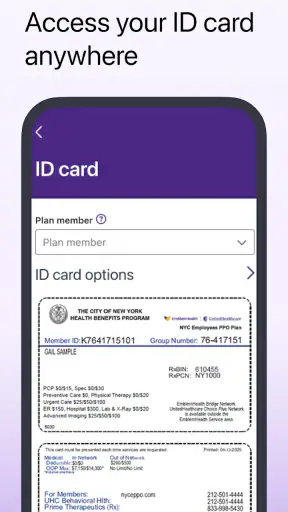
A useful habit is to prepare before leaving for an appointment. Open the app at home, make sure you can reach the member area, and check that the member ID card is available to you. Doing this before standing at a reception desk avoids the awkward combination of a busy waiting room, a poor connection, and a forgotten sign-in detail. The app’s value is strongest when it removes that small piece of friction at the exact moment you need it.
What it is good for in ordinary situations
I see three especially sensible uses. First, it can serve as a convenient digital route to your plan information after you have received your member ID card. Second, it can help you keep plan access close at hand when the physical card is not in your wallet. Third, it gives a household member a straightforward way to assist with plan-related preparation without turning the process into a hunt through paperwork.
There is a trade-off here. A physical card is immediate and does not depend on a battery, a login, or a working app. The mobile version is easier to carry and harder to misplace if your phone is always with you, but it introduces the normal responsibilities of phone security and account access. I would keep the physical card available as a backup, especially before an important visit or while traveling.
The app is also not the right choice for every health question. If I wanted help understanding symptoms, comparing treatments, recording detailed health measurements, or communicating directly with a clinician, I would look for a different kind of medical service. This app’s strength comes from being tied to the NYC Employees PPO Plan, not from trying to cover every part of healthcare.
Setting it up without crossing account boundaries
The first setup boundary is simple: access is connected to membership. The app’s purpose is to let a member use the NYCE PPO app after receiving the member ID card. That means downloading it before the card or before eligibility is established is unlikely to be useful. I would wait until the card is in hand and keep the information nearby during the initial setup.
That detail is particularly important in a household where one person manages paperwork for everyone. Helping someone install the app is fine, but I would avoid assuming that the helper should create or control the member’s access. The cleanest arrangement is for the actual member to complete the account steps, review what is shown, and decide whether another person should assist later. This keeps responsibility clear and reduces the chance of mixing one person’s plan information with another’s.
Shared devices need the same separation. If two eligible people use one tablet, I would not treat the device as though it automatically belongs to both accounts. Each person should use their own appropriate access path, and the household should be careful about leaving one member’s information visible when another person picks up the device. The app can be useful in a shared setting, but it does not remove the need for personal account boundaries.
Before relying on it, I would also make sure the phone itself is protected with a lock and that the operating system meets the app’s requirement. The current version is 1.8.0 and requires Android 9 or later. That makes the app accessible on many still-common Android phones, while users with older devices may need to use another way to reach their plan information. I would check compatibility before an appointment rather than discovering the limitation at the last minute.
A practical setup routine
Have the member ID card available before beginning.
Install the app on the member’s usual, protected device rather than a public or borrowed phone when possible.
Complete access while the member is present, even if another household member is providing technical help.
Open the app again before an appointment so the member knows where the relevant information is located.
Keep the physical card available as a fallback for situations involving a dead battery, an unavailable device, or an older phone.
This routine may sound cautious, but it reflects the app’s role. It is not something I would install casually and then expect to work as a universal healthcare organizer. It is a plan-access tool, so the quality of the experience depends partly on having the right member information and the right person using it.
One friction point is that a household helper may know the member’s paperwork better than the member does. That can make setup feel less convenient if the helper assumes they can simply use their own details. I would resist that shortcut. For insurance-related access, clarity is more valuable than shaving a minute off installation. The member should know which account is being used and what information is being displayed.
Using it to coordinate appointments and plan-related tasks
Coordination is where I think a plan-specific app earns its place. Imagine a parent helping an adult child prepare for a visit, or a partner calling a provider while the member is at work. Instead of passing around a paper card or searching through messages, the member can open the app and provide the relevant plan information directly. That does not make the app a family-management system, but it can reduce the number of small handoffs that cause mistakes.
I would use it as a preparation tool rather than as the sole source of truth during a complicated healthcare situation. Before making a call, I would have the member review the information personally. Before an appointment, I would make sure the person attending knows which member’s details are being presented. These simple checks matter when several people in a household have different coverage arrangements.
A non-obvious benefit is that digital access can improve the timing of coordination. The person managing the household does not necessarily need to keep every card in one place. The member can bring the information to the conversation when needed, which is useful when adults in the same household work different schedules or live separately. The trade-off is that coordination becomes dependent on the member’s willingness and ability to open the app at that moment.
I would also avoid sending screenshots around casually. A screenshot may be convenient for a short-lived administrative task, but it can remain in a photo library or message thread long after the appointment. Showing the information directly on the member’s device is usually the tidier approach. If a provider specifically needs details entered into a form, I would enter them carefully instead of assuming a saved image is the best solution.
Another practical limitation is scope. A person coordinating care may still need other sources for provider questions, clinical records, prescriptions, appointment scheduling, or urgent guidance. The app should sit alongside those tools, not replace them. If the task is about understanding a medical decision, I would contact the appropriate healthcare professional. If it is about plan access or presenting member information, this app is the more relevant place to start.
When another option is better
For a one-time visit, the physical member ID card may be faster than installing an app. For someone who rarely uses a smartphone, a direct conversation with the plan or provider may feel less stressful. For a household that already has a secure, reliable way to organize insurance documents, the extra app may not add enough value to justify another sign-in and another item to maintain.
On the other hand, people who often leave their wallet at home, switch between work and personal locations, or help coordinate plan details from a distance may appreciate having access on a phone. I would especially favor it for the member who wants a digital backup but still keeps the physical card available. That combination gives the convenience of mobile access without making the phone the only option.
Age, trust, and responsible household use
The Everyone rating makes the app suitable in age terms for a broad audience, but age suitability is not the same as independent account readiness. A teenager might be able to operate the app, while an adult should still decide how plan information is handled. An older family member may appreciate help with installation or navigation, yet still want to remain the person who approves access and decides what is shared.
I would explain the app in plain language to anyone who needs assistance: this is for accessing information connected to the NYC Employees PPO Plan, not for diagnosing illness or making treatment decisions. That distinction is useful for younger users, older relatives, and anyone who might assume that a medical-category app provides medical advice. Clear expectations prevent the wrong kind of trust.
Trust also matters between household members. A partner helping with an appointment should not automatically have unrestricted access simply because they handle other family tasks. The member should choose when to share the screen and should be comfortable with who can see the information. On a family tablet, I would be particularly careful about leaving the account open while children or visitors are using the device.
For older adults, the best approach may be guided setup followed by independent practice. I would help the person open the app, locate their plan information, and repeat the process once while they do it themselves. Then I would write down a simple reminder such as “open the PPO app before the visit,” without recording sensitive sign-in details in an exposed place. This turns the app into a support tool rather than making the older user permanently dependent on another person.
For younger household members, I would focus on context. They may be able to show a card or read information, but they should know that plan details are private and that a provider’s medical questions still belong in the proper clinical conversation. The app does not need complicated family rules to be used responsibly; it needs a clear understanding of who the member is and why the information is being accessed.
What the rating and maturity details suggest
The app’s 4.7 average from roughly one hundred seventy ratings is encouraging, especially for a focused medical utility. I read that as a sign that many people find the basic experience useful, not as proof that every household or every device will have the same experience. A focused app can receive positive feedback because it solves one important problem well, while still feeling limited to users expecting a full healthcare platform.
The Everyone age classification also fits the app’s administrative purpose. It does not turn the app into something a child should use without supervision, and it does not remove the need for privacy awareness. In my view, the rating is reassuring for general availability, while the account boundary remains the more important consideration in a shared household.
My household verdict
I would recommend NYC Employees PPO Plan to eligible members who want a convenient mobile way to reach their plan information after receiving their member ID card. Its best qualities are focus and practicality: it is free, tied to a specific PPO plan, and simple to position in an everyday routine. The developer, UNITED HEALTHCARE SERVICES, INC., has kept the product’s purpose clear rather than presenting it as an all-purpose medical companion.
I would not recommend installing it just because it appears in the medical category. If you are not a member of the NYC Employees PPO Plan, or if you are looking for symptom advice, detailed health tracking, clinical messaging, or a complete family-care workspace, this is probably not the right app. A general health service, a provider’s own system, or a traditional phone call may serve those needs better.
For households, my advice is to use it with a simple division of responsibility: the member owns the access, trusted relatives can help when invited, and the physical card remains a backup. That approach makes the app useful without turning a shared phone into a shared insurance account. It also keeps coordination practical when one person is arranging care for another.
The app was released on October 24, 2025, and its current version is 1.8.0. Those details make it sensible to check that your device is compatible and that you are using the current release before depending on it during an appointment. Overall, I see it as a worthwhile, narrowly defined utility. Its real strength is not breadth; it is having the right plan information available when a member or trusted helper needs it.
FAQ
What is the NYC Employees PPO Plan app used for?
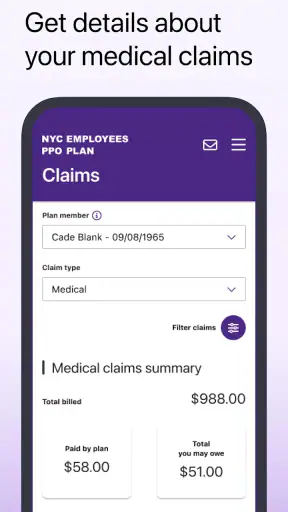
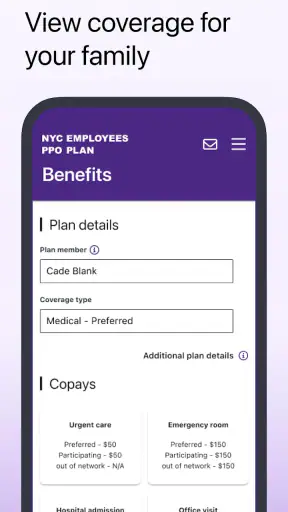
The NYC Employees PPO Plan app is designed to help eligible New York City employees and covered dependents manage health plan information in one place. Depending on the available features, users may be able to review benefits, access member identification details, search for participating providers, check claims or coverage information, and find important customer service contacts without carrying printed documents.
Who can use the NYC Employees PPO Plan app?
The app is generally intended for members enrolled in the NYC Employees PPO Plan, including eligible city employees, retirees where applicable, and covered dependents. Access may require information from your health plan enrollment or member ID card. If you are unsure whether your coverage is supported, confirm eligibility with the plan administrator or the official NYC benefits office before downloading or registering.
Does the app replace my health insurance member ID card?
The NYC Employees PPO Plan app may provide convenient access to digital member information, but it should not automatically be considered a complete replacement for your physical insurance card. Some doctors, pharmacies, hospitals, or administrative offices may still request the original card or specific details printed on it. Keep your physical card available, especially during urgent care, travel, or registration.
Can I use the app to find doctors and check whether services are covered?
A key benefit of a PPO plan app is the ability to locate participating doctors, hospitals, and other healthcare providers. However, provider directories and coverage information can change, and search results may not guarantee payment for a particular service. Before receiving expensive, specialized, or out-of-network care, contact the plan directly to confirm eligibility, authorization requirements, deductibles, and expected costs.
Is the NYC Employees PPO Plan app secure, and what should I do if I cannot log in?
The app may require account credentials, personal member information, or device security features to protect sensitive health and insurance data. Use only the official app listing and avoid sharing your password or verification codes. If login fails, check your connection, update the app, and use the official password-recovery option. For persistent problems, contact the plan’s verified member support service rather than relying on unofficial assistance.