Learn Stock Trading - Finrise
4.6EducationUpdated October 2, 2026
Screenshots
Pros
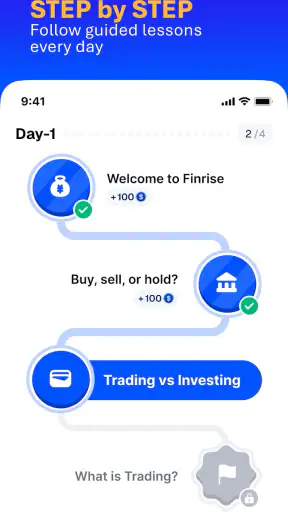
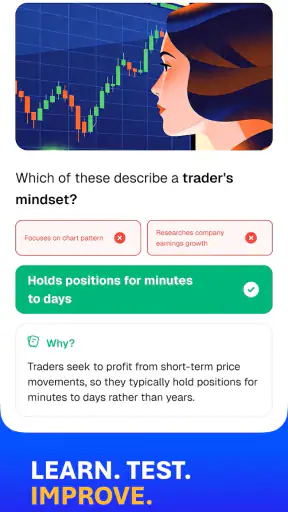
- Beginner-friendly lessons explain stock market basics in simple language.
- Short learning modules make it easy to study during spare moments.
- Covers essential trading concepts before introducing more advanced topics.
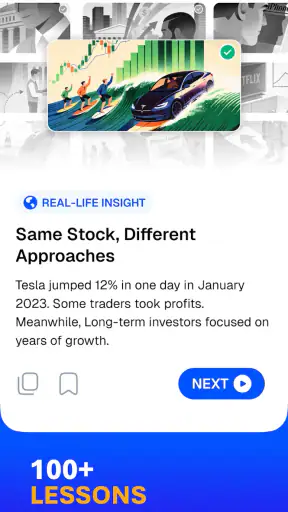
- Practice-focused content can help users build confidence without risking money.
- Clean interface makes lessons easy to browse and follow on mobile devices.
Cons
- Some advanced strategies and market topics may receive limited coverage.
- Educational content cannot replace personalized financial or investment advice.
- Premium lessons or features may require a subscription or in-app purchase.
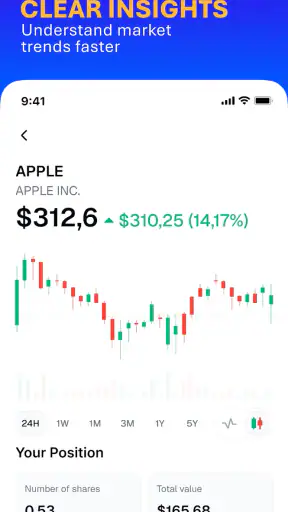
- Users may need external tools for live charts
- research
- and actual trading.
- Market examples can become outdated as financial conditions and rules change.
 Analysis By Mobexer
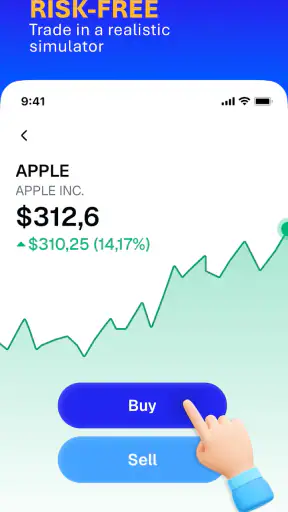
I found Learn Stock Trading - Finrise most useful when I treated it as a shared learning tool rather than a replacement for a brokerage account. It is an education app from Deep Flow Apps built around realistic market simulation, so the main appeal is being able to practise investing decisions without immediately putting household money at risk. That makes it interesting for a parent and older child, partners learning together, or friends who want to compare their reasoning while sitting at the same table.
The app is free to install, with optional purchases ranging from $6.99 to $59.99 per item. It is rated for Everyone, runs on Android 7.0 or later, and the current version is 1.1.0. Those details make it accessible on many older devices, although accessibility should not be confused with suitability for every child: the subject matter is financial, and a younger user still needs an adult to explain that simulated results are not promises about real investments.
How Finrise works when several people share the learning experience
My preferred way to use Finrise was as a conversation starter. One person can make a simulated decision, then explain why it seemed sensible before looking at the result. Another person can challenge the assumption: was the decision based on a trend, a company story, fear of losing, or simple guesswork? That discussion is where the app becomes more valuable than a quick round of random buying and selling.
A realistic household scenario would be a short evening session after dinner. A parent might let a teenager choose a simulated position while asking the teenager to write down the reason first. The next session can focus less on whether the result was positive and more on whether the original reasoning was consistent. This small habit helps separate a good process from a lucky outcome, which is one of the hardest lessons for beginners to learn.
I would not hand the phone over with the expectation that the app will teach everything automatically. The simulation gives decisions a practical shape, but a new learner may still need plain-language explanations of risk, diversification, time horizons, and the difference between investing and frequent trading. Finrise works best when the people using it agree to pause and discuss those ideas instead of racing toward the most exciting result.
It is also worth deciding what “shared use” means before starting. If two people take turns on one device, they should say whose turn it is and keep a simple note of the decisions made. If each person uses a separate device, they can compare choices verbally without assuming that one person’s simulated outcome proves superior skill. The app can support a joint learning routine, but the household has to create the boundaries and communication around it.
What I would agree on before opening the simulator
The first boundary is that simulated money stays separate from real money. I would make this explicit with a child or beginner, especially after a successful run. A convincing result can create overconfidence, while a poor result can make someone believe that investing is simply gambling. Neither conclusion is useful. The exercise should be about testing decisions under changing conditions, not predicting a guaranteed path to wealth.
The second boundary is time. A short planned session is more productive than leaving a beginner to chase every movement. I prefer choosing one question for each session, such as whether the decision was too concentrated or whether the entry was based on evidence. This keeps the experience educational and reduces the temptation to treat every simulated change as an urgent event.
The third boundary concerns purchases. Since the app is free but includes optional in-app purchases, I would review the purchase situation before allowing unsupervised use on a shared device. That is especially important when a child uses a parent’s phone or tablet. A household can enjoy the free starting point while deciding together whether any paid item is genuinely useful for its learning goal. I would never connect a purchase decision to a child’s simulated performance.
There is also a practical account boundary. I would avoid assuming that one shared device automatically creates separate learning histories or private spaces. If the app presents a shared session, each user should identify their choices in a notebook or household document. That simple record prevents confusion over who made a decision and makes later review much more meaningful.
For adults, the same rule applies in a different way. A partner who uses the app should not be expected to reveal personal brokerage details just because both people are practising together. Finrise is a simulation tool, not a reason to blur financial privacy. Discussing a decision is healthy; demanding access to someone’s real portfolio is a separate matter.
Turning simulated decisions into useful coordination
The strongest shared workflow I found was to divide the activity into three moments: prediction, decision, and review. Before making a move, the user states what they expect and what could prove them wrong. During the decision, they choose an action without changing the explanation to fit the outcome. Later, everyone reviews the result and asks whether the original logic still makes sense. This method is more revealing than celebrating every gain.
A second useful technique is to give each person a different role. One user can focus on the company or market story, another can question the level of risk, and a third can act as the note-taker. The roles should rotate so that the same person is not always the cautious voice or the enthusiastic trader. Finrise becomes a small decision laboratory rather than a contest over who gets the best result.
I also recommend comparing decisions by consistency, not just performance. If one person takes a very aggressive approach and another uses a cautious approach, the outcome alone cannot settle the argument. The better question is whether each person followed the approach they claimed to be testing. This is a non-obvious advantage of using a simulation in a household: it makes financial habits visible without exposing anyone to an immediate real-world loss.
For a teenager, an adult can add a simple reflection after each session: what information mattered, what information was ignored, and what would make the decision change? For two adults, the same questions can reveal different comfort levels with uncertainty. The app does not need to force everyone into one style. Its value is in giving the household a common situation to analyse.
One limitation is that coordination depends heavily on the users. I did not treat the app as a built-in family classroom, and I would not assume that it provides household profiles, parental dashboards, or automatic turn-taking. Anyone looking for those controls should choose a service that explicitly offers them. Finrise is better suited to guided cooperation than to managing several learners independently.
Age, trust, and the difference between practice and advice
The Everyone rating makes the app broadly approachable, but the topic still deserves age-appropriate supervision. A child may understand the buying-and-selling idea while missing the deeper point that real investments can lose money, take time to recover, and involve decisions that affect family goals. I would use the app with younger learners only alongside an adult who can translate the simulation into everyday examples.
Trust matters too. If a household turns every result into a judgment about intelligence, the learning value disappears. A losing simulated decision should be treated as something to examine, not as evidence that the person is careless. Likewise, a winning decision should not be presented as proof that the person is ready to invest real savings. Keeping that emotional boundary is more important than squeezing out another round.
Older teenagers and adults are likely to get more from the app because they can discuss uncertainty and delayed results with greater maturity. Even then, I would keep the app separate from actual financial instructions. It can help someone practise thinking in scenarios, but it should not be the only source used before opening a real account or choosing an investment.
This is where Finrise differs from the usual alternatives. A stock-news app is better for following current events, a brokerage app is designed for real transactions, and a long-form course may explain concepts more systematically. Finrise sits between those options: it gives abstract lessons a decision-making context, but it cannot replace professional advice, current research, or the discipline of a real financial plan. For a beginner who learns by doing, that middle ground is useful. For someone seeking detailed analysis or live execution, another tool is more suitable.
What the app does well for beginners
The realistic simulation gives beginners a safer place to notice their own reactions. I found that a user can discover whether they tend to chase an exciting move, hesitate after a loss, or change direction too quickly. Those patterns are difficult to spot when reading definitions alone. A simulation makes the emotional side of decision-making easier to discuss because the consequences remain contained.
It is also a good fit for people who find financial textbooks intimidating. The store summary presents it as a way to master investing and strategic stock trading through market simulation, but I would frame the benefit more modestly: it helps turn financial vocabulary into choices that can be examined. That is a meaningful first step, especially for someone who has avoided the subject because it seemed too technical.
Another strength is its usefulness in short, repeatable sessions. A household does not need to organise a formal course. Ten or fifteen minutes of focused discussion can be enough to test one idea, provided the users record their reasoning and return to it later. The best learning comes from revisiting decisions rather than constantly starting over with a new exciting scenario.
The app’s public reception is encouraging without being a reason to lower your standards. It holds a 4.6 average from around 1.5 thousand ratings, has more than 50 thousand installs, and lists 43 written reviews. I read those figures as signs that the concept has found an audience, not as evidence that it will match every learner’s preferred style. A simulation can be well received and still feel too simple for an advanced investor.
Deep Flow Apps has kept the entry point approachable, but the free label should be read carefully because optional purchases are present. I would start with the free experience and only consider spending after identifying a specific learning need. Buying extra material simply because a simulated result was disappointing would be the wrong reason to pay.
Where I felt the limits most clearly
The central limitation is that practice can create confidence faster than understanding. A user may become comfortable making simulated trades while still lacking a personal budget, an emergency fund, or a realistic time horizon. Finrise can help with decision habits, but it does not make those broader financial responsibilities disappear.
There is also a risk of focusing too much on activity. Stock trading feels more engaging when something happens frequently, yet long-term investing often involves patience and restraint. I would deliberately include sessions where the best discussion is whether doing nothing would have been more sensible. If a learner believes every visit must produce a trade, the simulation may reinforce the wrong habit.
Shared use can introduce friction when people have different goals. One person may want a calm introduction to investing, while another wants a competitive trading challenge. Without an agreed purpose, the more confident user can dominate the session and the beginner can become a spectator. I would solve that by setting turn limits and letting each person explain one decision before anyone critiques it.
Finrise is not my first recommendation for someone who already understands valuation, portfolio construction, and risk management. That user may prefer detailed market tools, specialist research, or a real portfolio tracker. The app is more compelling for beginners, families starting a conversation, and adults who want to test their instincts before making real commitments.
I would also skip it if you want direct financial advice, real account integration, or a substitute for a regulated investment service. The simulation format is precisely what makes it safer for learning, but that same separation means it should not be mistaken for a complete financial platform. Its job is to support practice and discussion, not to manage household wealth.
My household verdict
After using it as a guided learning activity, I see Finrise as a sensible free starting point for households that want to talk about investing without immediately involving real money. Its strongest use is not predicting the market; it is helping people explain decisions, recognise emotional habits, and compare different approaches respectfully.
I would recommend beginning with one shared device, one clearly stated learning question, and a written note of each decision. Keep real accounts and personal financial information outside the exercise, supervise younger users, and treat optional purchases as a separate adult decision. Those steps address the main practical risks without pretending the app includes family-management features of its own.
The app is less suitable for independent child use, advanced investors, or anyone looking for live trading and personalised guidance. It also needs a little structure from the people using it, because the educational value can fade if sessions become a race for the highest simulated result. Used thoughtfully, though, it gives a household a common language for discussing risk and patience.
With a 4.6 average, over 50 thousand installs, an Everyone rating, and support for Android 7.0 or later, it is easy to see why the app appeals to newcomers. My final view is positive but measured: Finrise is best when it turns investing into a shared conversation, not when it is treated as a shortcut to real-market confidence. For a beginner who wants to practise reasoning before risking savings, that is a worthwhile role.
FAQ
What is Learn Stock Trading - Finrise, and who is it designed for?
Learn Stock Trading - Finrise is an educational app focused on introducing users to stock-market concepts, investing terminology, chart reading, and basic trading ideas. It is mainly suited to beginners who want a structured starting point rather than experienced traders looking for advanced professional tools. The lessons can help organize your learning, but they should not be considered personalized financial advice or a guarantee of investment success.
Can I use Finrise to buy and sell stocks directly?
Finrise is primarily a learning and education platform, not necessarily a full brokerage service. Its purpose is to explain how markets and trading work, so users should not assume that completing lessons gives them access to live stock orders. Before downloading, check the current app description and available features in your region to confirm whether it includes simulations, market tracking, broker connections, or any real-money trading functionality.
Is Learn Stock Trading - Finrise suitable for complete beginners?
Yes, the app is intended to be approachable for people who have little or no previous investing experience. Its educational format can help explain subjects such as stocks, market movements, risk, and trading strategies in a more accessible way than many technical finance resources. However, beginners should still study independently, compare information from reliable sources, and avoid investing real money until they understand potential losses and fees.
Does Finrise provide reliable financial advice or guaranteed trading results?
No educational app should be treated as a source of guaranteed returns, and Finrise should not replace advice from a qualified financial professional. Market conditions can change quickly, and even strategies that appear successful in lessons may produce losses in real trading. Use the app to build general knowledge, question promotional claims, and make independent decisions based on your financial situation, risk tolerance, and investment goals.
Is Learn Stock Trading - Finrise free to download, and are there in-app purchases?
The download model, available lessons, subscriptions, and premium features may vary between Android and iOS and can also change over time. Some educational apps provide introductory content for free while placing advanced courses, progress tools, or additional materials behind a subscription or one-time purchase. Review the store listing carefully before installing, including trial terms, renewal pricing, cancellation rules, and the permissions requested by the app.