InmateSales
3.8CommunicationUpdated October 5, 2026
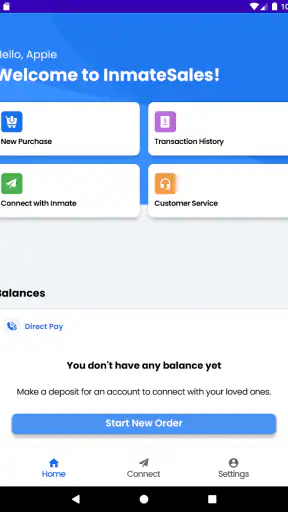
Screenshots
Pros
- Convenient way to manage inmate commissary and approved purchases remotely.
- Supports multiple facilities through one account in many cases.
- Order details and payment confirmations are easy to review.
- Reduces the need for phone calls or in-person facility visits.
- Useful for sending approved care-package items to eligible inmates.
Cons
- Availability and features vary significantly by correctional facility.
- Orders may be delayed by facility processing and security inspections.
- Service fees can make small purchases noticeably more expensive.
- Refunds or corrections may require contacting support or the facility.
- Recipient eligibility and item restrictions can limit available purchases.
 Analysis By Mobexer
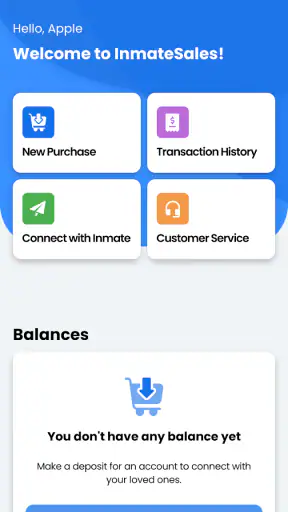
When a family member is in a facility and you need to handle deposits, the difficult part is often not the payment itself but keeping the process organized. InmateSales is built for that narrow communication and account-management job. I see it as a practical companion for people who already use an InmateSales account and need a mobile way to manage it, rather than as a general messaging app or an all-purpose family finance tool.
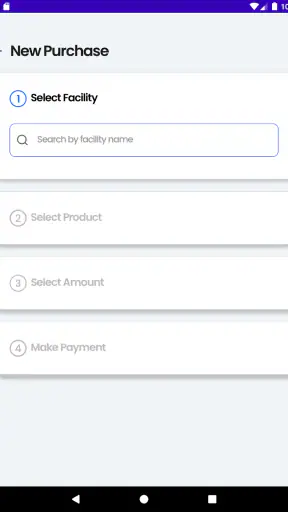
I tested the app with that distinction in mind. Its role is straightforward: it lets you manage your account and make deposits at certain facilities. That wording matters because the facility connection is central to the experience. This is not an app where every function is available everywhere; its usefulness depends on whether the relevant facility supports the service. When that match exists, having the account tools on a phone can remove a lot of unnecessary back-and-forth.
The app is free, aimed at everyone, and developed by Combined Public Communication LLC. It belongs in the communication category, although its practical value is closely tied to account and payment tasks. With a 3.8 average from around 1.5 thousand ratings and over 500 thousand installs, it has clearly reached a sizeable group of users, while the rating also suggests that the experience may not feel equally smooth for everyone.
Using InmateSales in a shared household
The most realistic use case is a household where more than one person may need to coordinate support for someone in custody. One person might be responsible for checking the account, another might handle a deposit, and a third may simply need to know whether the task has been completed. The app can be useful as the place where the account action happens, but I would not treat it as a shared household dashboard.
That difference is important. A family may discuss responsibilities through ordinary text messages, a group chat, or a shared calendar, then use InmateSales only when the actual account needs attention. In my view, this separation is safer and clearer than expecting one app to manage every part of the family conversation. The app handles the service-related step; the household chooses its own method for reminders, approvals, and record keeping.
A simple routine works well. Before opening the app, the family can agree on who is making the deposit, which account should be used, and whether anyone else needs confirmation afterward. The person completing the action can then use the mobile account tools without asking several people to sign in. This reduces duplicated attempts and makes it less likely that two relatives will unknowingly perform the same task.
For a shared phone, I would be more cautious. If several people use the same device, the next person should not automatically assume that the visible account belongs to them. I recommend treating the app as personal account access even when the phone itself is communal. Close the session when finished, avoid saving sensitive details where other users can see them, and make sure the person using the device understands which account is active.
That advice is not a criticism of the app so much as a sensible boundary for any service that combines personal account information with deposits. InmateSales can support a household workflow, but it does not replace clear ownership. The household still needs to decide who is authorized to act and how the result will be communicated.
What the first setup should accomplish
My first recommendation is to begin with the account rather than with the deposit. Confirm that you are using the intended InmateSales credentials and that the facility involved is one of the places supported by the service. If the facility is not covered, repeatedly retrying the same action will not solve the underlying problem; you will need to use the channel accepted by that facility instead.
On a personal phone, I would also check the app identity before entering account information. The developer shown for this app is Combined Public Communication LLC, which gives you a useful detail to compare when installing or updating. The current version is 1.10.1-b605150303, and the app requires Android 8.0 or later. Those details are especially relevant in a household where an older spare phone may be used for occasional account tasks.
Older hardware can create a misleading impression. If the app feels slow or unreliable on a device that barely meets the operating-system requirement, the problem may involve the phone rather than the account workflow. I would first try a stable connection, close unrelated apps, and repeat the task carefully before deciding that the service itself is unusable. For important deposits, I would avoid waiting until the last possible moment to discover a device or connection problem.
Another useful boundary is separating account access from family discussion. Do not pass around one phone while displaying account details simply because several relatives are involved. Instead, decide whether one trusted person will manage the account or whether each authorized adult will use their own access. The app gives you a mobile route into the service, but the household arrangement around that access remains your responsibility.
Because the app is rated for everyone, it may appear suitable for any member of a family to open. I would interpret that age rating as broad content guidance, not as a recommendation that children should manage deposits or account credentials. Financial responsibility and private account access are adult decisions, even when a younger family member is helping with a phone or reminder.
Making deposits without losing track of responsibility
The deposit function is the feature that gives the app its practical purpose. I like the idea of being able to handle this task from a phone, particularly when a relative is away from a computer or needs to act while traveling. The convenience is real, but it can also encourage rushed decisions. A few taps on a familiar device can make a financial action feel more casual than it actually is.
For that reason, I would use a short verbal or written checklist before confirming anything: identify the intended account, verify the facility context, confirm the amount independently within the household, and record who completed the action. The app can perform the service step, but a separate household note can prevent confusion later. This is one of the most useful ways to combine the app with ordinary family coordination.
I would also avoid making a deposit on behalf of someone else without a clear agreement. In shared households, people often assume that a close relative will understand the arrangement, but assumptions become awkward when several people are contributing money. A quick message such as “I am handling this one” can prevent duplicate payments and make the family’s records easier to follow.
There is another trade-off here: the app is convenient precisely because it focuses on a specific service, but that focus means it should not be treated like a complete personal-finance application. I would not use it as the only place to track a household budget, divide contributions, or document long-term support. Use a separate method for those broader tasks, and keep InmateSales for the account action it is designed to provide.
If a deposit does not behave as expected, patience is more useful than repeated tapping. First check whether the account and facility are correct, then review the transaction context before trying again. Repeating an uncertain action can make it harder to understand what happened. A household member who is not making the deposit can serve as a second pair of eyes, especially when the account has emotional importance and mistakes would be stressful.
Coordination between relatives and caregivers
InmateSales is most effective when it sits inside a simple communication plan. I would assign one person to perform the account action and another person, if needed, to maintain the family’s reminder or contribution schedule. That division keeps the app from becoming a crowded shared workspace and makes accountability much clearer.
For example, imagine two siblings supporting the same incarcerated relative. One sibling may be near a computer during the day, while the other is more comfortable using a phone. They can agree that the phone user will manage the deposit through InmateSales, while both record their contributions in a shared note. The app handles the mobile transaction; the note handles the relationship between the two contributors. That arrangement avoids asking both people to navigate the account at once.
Caregivers should be especially careful about verbal instructions. If one person asks another to “put money on the account,” that may be too vague when a household supports more than one person or when several facilities are involved. Before opening the app, clarify exactly whose account and which facility are intended. This small step is easy to skip and has more value than any clever shortcut.
I also would not assume that every relative needs direct access. Sometimes the best setup is one trusted account holder, with other family members receiving confirmation through their normal communication channel. Fewer account holders can mean fewer forgotten sessions, fewer misunderstandings, and less exposure of personal information on a shared device. On the other hand, if one person is unavailable often, a second authorized adult may make the household more resilient. The right choice depends on trust and responsibility, not on the number of people in the family.
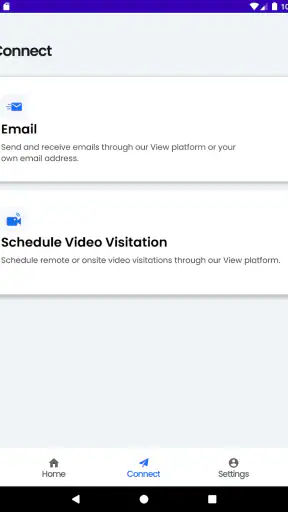
The app’s communication-category placement can be slightly misleading if you expect conversation features. I would not choose it as a replacement for calls, messaging, or family updates. Its communication value is indirect: it helps a household carry out a support-related account task. If your main need is to talk with someone, a normal communication service is the better tool. If your need is to manage the InmateSales account connected to a supported facility, this app is much more relevant.
Age, privacy, and trust on a family device
The everyone age rating makes the app approachable, but it does not remove the need for adult supervision of account activity. A child might help locate the app or hand over a phone, yet I would keep credentials, deposit decisions, and confirmation steps with a responsible adult. This is particularly important when the device is shared between parents, teenagers, grandparents, or caregivers.
On a family tablet or spare phone, establish a clear rule about when the app may be opened. Do not leave it running simply because the device is kept at home. If the phone changes hands frequently, closing the app after use is a basic but worthwhile habit. I would also avoid discussing account details aloud when children or visitors are nearby unless everyone involved understands the privacy implications.
Trust has two sides here. The account holder needs confidence that another person will not make an unintended deposit, while the helper needs clear permission rather than an informal assumption. A written household agreement can be simple: who may use the account, who approves a deposit, and where the family records the result. InmateSales cannot create that agreement for you, but it works better when those boundaries are already settled.
There is also a practical emotional benefit to defined roles. Supporting someone in custody can involve urgency, worry, and several relatives trying to help at once. A clear process gives each person a manageable job. One person checks the account, one confirms the amount, and one keeps the household note current. That structure does not make the situation easy, but it can prevent avoidable tension around the app.
Where this app fits among the alternatives
Compared with using a mobile browser, a dedicated app can feel more direct for someone who repeatedly manages the same InmateSales account. The app keeps the task in a focused mobile environment instead of requiring you to find the service through a browser each time. I value that convenience for recurring household responsibilities.
However, a browser may be the better choice for someone who rarely uses the service, works mainly from a computer, or prefers not to keep a specialized account app on a phone. A browser can also fit better when a family member is using a managed work device or a shared computer with a carefully controlled session. The app is not automatically superior; it is most useful when mobile access is part of your normal routine.
Compared with general payment apps, InmateSales has a much narrower purpose. A standard payment service may be more suitable for sending money to relatives, organizing household contributions, or managing ordinary bills. It is not a substitute for the facility-specific account connection that this app provides. Conversely, a general payment tool may not help at all when the task must pass through a supported InmateSales facility workflow.
This narrowness is both the strength and the limitation. I would recommend it to someone who already knows that their facility uses the service and wants a phone-based way to manage the associated account. I would skip it if the goal is family messaging, broad budgeting, or a universal deposit method. In those situations, another tool will be simpler and more appropriate.
Performance expectations and everyday friction
The app has been available since May 4, 2022, and its current release is 1.10.1-b605150303. I mention the version because users sometimes install a specialized service once and forget to check it again. Keeping the app current is a sensible maintenance habit, particularly when the phone is used for account actions rather than casual browsing.
Still, an update does not guarantee that every household experience will be smooth. The 3.8 average rating, based on around 1.5 thousand ratings and roughly 500 reviews, points to a mixed overall impression rather than universal satisfaction. I would set expectations accordingly: the app may be convenient when the account and facility relationship is straightforward, but you should leave yourself time to troubleshoot if an important task is urgent.
The install base of over 500 thousand also tells me that this is not an obscure one-off utility. It has been used by many people, yet popularity alone should not decide whether it belongs on your phone. The key question is practical: does your facility support the service, and does your household benefit from managing the account on mobile? If either answer is no, the app’s install count will not make it more useful to you.
My best everyday tip is to use the app during a calm moment before you actually need it. Sign in, understand where the account controls are, and establish your family’s process without pressure. Then, when a deposit is needed, you are not learning the workflow while also handling an emotional or time-sensitive request. This preparation is more valuable than trying to make the app do jobs it was never intended to handle.
My household verdict
After looking at the app through a shared-device and family-coordination lens, I see InmateSales as a focused utility with a clear place in a specific household routine. It can make account management and deposits more convenient for supported facilities, especially for relatives who prefer handling these responsibilities from a phone. The free price and everyone age rating make it easy to consider, while Android 8.0 support keeps it usable on many older devices.
I would recommend it to the designated adult in a family who already has an InmateSales account and needs regular mobile access. I would also recommend agreeing on account boundaries before multiple relatives start helping. Use ordinary messaging or a shared note for coordination, keep financial decisions with trusted adults, and treat the app as the transaction tool rather than the family’s complete communication system.
I would choose a browser or another payment option for someone who does not use a participating facility, rarely handles the account, or mainly wants general money management. The app’s specialization is not a flaw, but it does mean the right audience is fairly specific. For that audience, its focused purpose can be genuinely useful; for everyone else, it may simply add another app without solving the real problem.
My final view is that InmateSales works best when paired with clear household roles. It provides a mobile path for the account task, while trust, confirmation, budgeting, and family communication still belong to the people using it. If you approach it with those boundaries in place, it is a sensible free tool to try for supported facilities. If you expect a full family communication or finance platform, I would look elsewhere.
FAQ
What is InmateSales and what can users do with it?
InmateSales is a communication and account-management platform designed to help approved contacts interact with incarcerated individuals through available correctional-facility services. Depending on the facility, users may be able to send messages, photos, electronic cards, or other permitted items, manage contacts, and review transaction history. Available features can vary considerably by institution, location, and service provider.
Is InmateSales available for every correctional facility?
No. InmateSales is not necessarily supported by every jail or prison. Access depends on whether the correctional facility has partnered with the service and which communication options it has enabled. Before creating an account or adding funds, users should search for the relevant facility inside the app or on the official service website and confirm that the incarcerated person is listed and eligible.
How do payments and account balances work in InmateSales?
InmateSales may require users to purchase credits or fund an account before sending messages, media, or other services. Prices, processing fees, minimum deposits, refunds, and expiration rules can differ depending on the facility and the product selected. Review the final checkout screen carefully, keep payment receipts, and verify the recipient and facility before confirming a transaction, since some purchases may not be refundable.
Are messages, photos, and other content reviewed before delivery?
Yes, users should expect communications submitted through InmateSales to be subject to facility rules and staff or automated screening. Messages, photographs, attachments, and other content may be delayed, rejected, or withheld if they violate institutional policies. Prohibited material can include threats, explicit content, coded language, gang-related imagery, or information restricted by the facility. Approval and delivery are never guaranteed.
What should I do if my message, payment, or account is not working?
First, check that the application is updated, your internet connection is stable, and the selected facility and recipient details are correct. Review your account history to confirm whether the payment was completed or the message was rejected. If the issue continues, contact InmateSales support through its official help channels and include your username, transaction details, facility information, and screenshots—without sharing unnecessary sensitive personal data.