CPOS: Tap to Pay Card Reader
4.4BusinessUpdated October 5, 2026
Screenshots
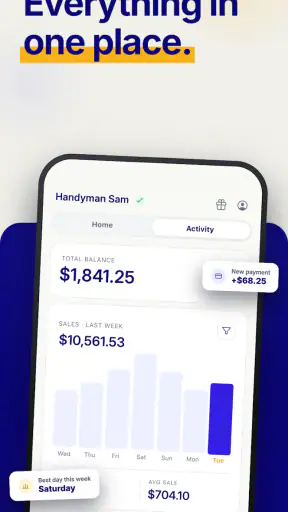
Pros
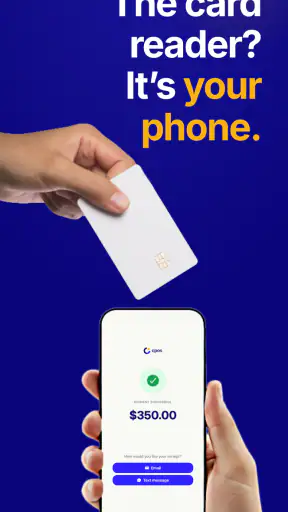
- Turns compatible phones into a convenient contactless payment terminal.
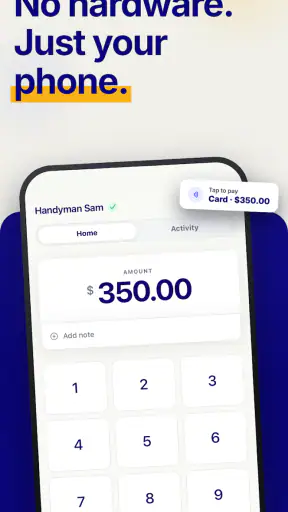
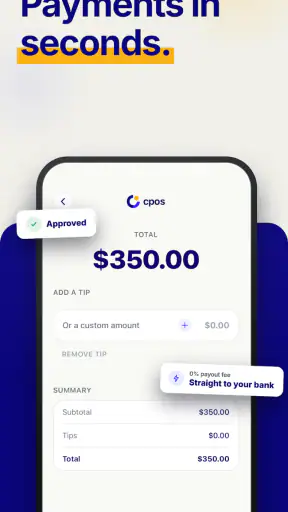
- Supports quick tap-to-pay transactions without dedicated card-reading hardware.
- Useful for small businesses
- mobile sellers
- and on-the-go service providers.
- Reduces the need to carry cash or a traditional POS terminal.
- Can help speed up checkout during busy periods.
Cons
- Device and region compatibility may limit access to tap-to-pay features.
- Transaction fees can reduce earnings
- depending on the payment plan.
- Requires a stable internet connection for reliable payment processing.
- Battery drain may be noticeable during extended payment sessions.
- Some customers may prefer card insertion or cash payment options.
 Analysis By Mobexer
Accepting a card payment from a phone sounds simple until the moment a customer is waiting, the signal is weak, and your usual terminal is somewhere else. CPOS: Tap to Pay Card Reader is built around that exact mobile-business problem. It turns a compatible phone into a card reader, so the appeal is obvious for market sellers, tradespeople, pop-up operators, and anyone who does not want to carry separate payment hardware.
I approached it as a practical business app rather than a novelty. The important question is not whether a phone can replace a terminal in theory, but whether the experience remains manageable when you are moving between places, switching networks, or trying to recover from a payment that does not go through. My overall impression is positive, especially for occasional or mobile sellers, although it is not automatically the best replacement for a full countertop payment system.
How CPOS feels when the network becomes part of the checkout
The developer behind the app is CPOS, and the product sits in the business category. Its central idea is deliberately focused: use a phone as a card reader without adding dedicated hardware or a monthly subscription. That makes the app interesting for a small operation that wants to start accepting card payments without committing to a more elaborate setup.
In practice, connectivity becomes part of the payment experience. A card transaction is not just a tap on the phone; it is a short chain of communication between the device, the payment service, and the customer’s bank. When that chain is healthy, the process should feel close to using a conventional terminal. When it is unstable, the phone becomes both the checkout device and the thing you must troubleshoot.
That distinction matters. A traditional terminal is usually treated as a single-purpose appliance, while a phone is also handling calls, notifications, battery management, and changing networks. CPOS benefits from the phone’s convenience, but it inherits the phone’s distractions and limitations. I would therefore judge it less by how impressive the contactless concept sounds and more by how calmly you can use it during a busy sale.
Where the mobile reader makes the most sense
The strongest use case is a business that does not stay behind one counter. Imagine a craft seller moving between weekend stalls. Instead of carrying a separate reader, the seller can bring the phone already used for messages, inventory notes, and customer contact. The payment point travels with the seller, which reduces the amount of equipment to prepare before leaving.
The same logic works for a repair technician collecting payment after finishing a job, a tutor charging at the end of a session, or a small service provider visiting customers. In these situations, a fixed terminal can feel excessive. The phone is already present, and removing another device from the workflow is a genuine advantage rather than a marketing trick.
There is also a useful middle ground for businesses that mostly take cash or bank transfers but occasionally meet a customer who wants to pay by card. CPOS can serve as a backup option in that scenario. I would not necessarily make it the only payment method without testing it in the places where the business operates, but it can prevent a lost sale when carrying a full terminal is inconvenient.
A realistic checkout routine
Before opening for the day, I would prepare the phone as carefully as I would prepare a cash drawer. That means charging it, closing unnecessary apps, checking the available connection, and keeping the screen easy for a customer to see. These steps are not special CPOS features; they are practical habits created by using a general-purpose phone as a payment device.
At a market stall, I would keep the phone in one consistent position and ask the customer to tap only when the app is ready. This avoids the awkward situation where a customer presents a card or phone too early while the transaction is still being prepared. A small stand would also help, because holding the device in one hand while handling goods or confirming the amount can make the exchange feel less controlled.
The network matters most at the point when the payment is being authorized. A strong connection can make the transaction feel routine, while an unreliable one can leave both people wondering whether to try again. My advice is to avoid immediately repeating a payment after an unclear interruption. First check whether the app shows a completed or pending result, then confirm the customer’s banking notification if appropriate. Repeating too quickly is how confusion and duplicate attempts begin.
Moving between Wi-Fi and mobile data
CPOS is particularly relevant to people who work in changing locations, but that also means network choices deserve attention. A shop with dependable Wi-Fi may offer a smoother environment than an outdoor stall relying on mobile data. On the other hand, public Wi-Fi can be unpredictable, crowded, or poorly configured, so I would not assume that any visible network is suitable for a payment session.
For mobile work, cellular data is often the more practical choice because it avoids asking a business owner to join unfamiliar networks. The trade-off is that coverage can vary from one street to the next, and a busy event may place extra demand on the local network. I would test the app at the actual selling location before advertising card acceptance there.
A useful preparation trick is to perform a small, controlled test before the first customer arrives. Do not wait until the queue forms to discover that the phone has switched to a weak connection or that a system update is demanding attention. This kind of test is especially valuable for temporary venues, where the network conditions can be very different from those at home or in a shop.
I would also avoid switching networks during an active transaction. If the phone is moving from Wi-Fi to mobile data at the same time a payment is being processed, the result may be harder to interpret. Finish or cancel the current attempt, confirm its status, and only then change the connection. That extra pause is much less stressful than trying to untangle an uncertain payment later.
What happens when a payment does not go smoothly
Separating a declined payment from a connection problem
One of the most important habits with a phone-based reader is learning not to treat every failed attempt as the same problem. A bank decline, an unreadable tap, an interrupted connection, and an app issue can all feel similar from the customer’s side, but the next step is different in each case.
If the customer’s bank declines the payment, changing your network will not solve it. The customer may need another card or another payment method. If the phone never appears to register the card, the issue may be positioning, timing, or the device’s contactless capability. If the screen becomes uncertain after the tap, the priority is checking the transaction status rather than asking the customer to tap repeatedly.
This is where CPOS asks more of the operator than a dedicated terminal might. You need to watch the screen, communicate clearly, and keep the customer informed. That is not a reason to reject the app, but it is a reason to train yourself before relying on it during a crowded event.
A recovery plan I would actually use
My recovery routine would be simple. I would keep the original amount visible until the result is clear, note the customer’s name or order reference when the business workflow allows it, and avoid starting a second attempt immediately after a timeout. If the app confirms failure, I would retry once after checking the connection and the phone’s contactless position. If the result remains uncertain, I would move to another payment method rather than creating a chain of guesses.
For a seller, a small written procedure can be more useful than relying on memory. It might say: check the result, ask the customer to wait, confirm whether the bank shows a charge, and only retry when the first attempt is clearly unsuccessful. This is one of the less obvious benefits of testing CPOS before launch: you discover not only whether it works, but also how you and your customers respond when it does not.
I would also keep a backup plan that does not depend on the same connection. That could mean accepting cash or using another established payment route, depending on the business. CPOS removes the need for a separate reader, but removing hardware does not remove the need for contingency planning. A phone can lose signal, run low on battery, or become unavailable for reasons unrelated to the payment app.
Battery, interruptions, and the shared-phone question
Because the app turns a phone into the payment point, battery discipline becomes part of business discipline. Navigation, camera use, social media, calls, and hotspot activity can drain a phone before the selling day ends. I would carry a power bank for mobile work and avoid treating the phone’s remaining battery percentage as a reliable measure of how many transactions are left.
Using a personal phone also raises a practical question: is the device shared with other staff? A solo operator can keep the process straightforward, but a team may need clear rules about who handles the phone, who confirms the amount, and how the transaction is recorded. CPOS may be convenient precisely because it uses a device already in someone’s pocket, yet that convenience can become a weakness if responsibility is unclear.
I would not hand the phone to a customer without first checking that the correct amount is displayed. A brief glance prevents a surprisingly serious error. After the payment, return to the business workflow promptly instead of leaving sensitive transaction screens open while serving the next person. These are ordinary operational safeguards, but they matter more when one device is doing several jobs.
Using less connectivity without making risky assumptions
There is a difference between being data-conscious and assuming that an app can work without a network. I would not plan a selling day around offline payments unless CPOS explicitly confirms that behavior for the specific setup. The safer approach is to treat a reliable connection as part of the operating requirement and prepare accordingly.
That does not mean the app must consume large amounts of data. Payment activity is usually brief, but the phone may also be downloading updates, syncing photos, streaming music, or backing up files. On a limited mobile plan, I would separate those activities from selling hours. Turn off unnecessary background use, avoid streaming at the stall, and reserve software updates for a stable connection when possible.
For privacy and reliability, I would prefer a trusted private connection over an open public hotspot. If a venue provides Wi-Fi, I would ask how visitors are expected to connect and whether the network is stable at the actual booth location. A network that works near the entrance may perform badly in a crowded hall, so a quick test at the payment point is more meaningful than a general signal check.
Another useful habit is to keep the phone’s system and CPOS version current before a major event, rather than updating moments before opening. The app’s current version is 2.34.0, and it requires Android 8.0 or later. That makes compatibility worth checking in advance, especially if you plan to use an older spare phone as the dedicated business device.
Who should choose it, and who should look elsewhere?
I think CPOS is a good fit for independent workers, temporary sellers, and small businesses that value portability over a permanent checkout station. It is also appealing to someone who wants to try card acceptance without paying for a reader or a monthly fee. The free price lowers the barrier to experimentation, although the wider payment costs and account requirements of any card-processing arrangement still deserve attention before making it central to the business.
The app is less convincing for a busy shop with several checkout points, multiple employees, or demanding reconciliation needs. A dedicated payment system may be better when you need a stable counter setup, a separate customer-facing display, integrated receipt handling, or a broader register workflow. CPOS is focused on turning a phone into a reader; it should not be mistaken for a complete retail management platform.
It may also be the wrong choice if your work regularly takes place in areas with unreliable connectivity and no practical backup payment method. The hardware-free design is attractive, but it places more responsibility on the phone and the network. For a remote operator, a solution designed specifically around that environment may be safer than depending on a general mobile device.
Compared with carrying a conventional card reader, CPOS wins on simplicity and packing space. Compared with cash, it can make payment easier for customers who do not carry notes. Compared with a full point-of-sale system, it is likely to feel narrower and more hands-on. That trade-off is the heart of the product: less equipment and less setup, but also more dependence on the person operating the phone.
What the adoption numbers suggest without telling the whole story
CPOS has an average rating of 4.4 from over two hundred ratings, with more than one hundred fifty written reviews and over ten thousand installs. Those figures suggest that the concept is working for a meaningful group of users, but they do not replace a test in your own environment. A payment app can feel excellent in a well-covered urban area and frustrating at a rural event, even when both users install the same version.
The app is free and rated for Everyone, which makes it approachable for a broad audience. It was released on January 17, 2025, so I would still treat direct hands-on testing as important when choosing it for a serious business workflow. Newer products can be perfectly useful, but a cautious operator should build confidence through small transactions and clear procedures rather than switching everything over in one afternoon.
My connectivity verdict
After looking at the app through the lens of real mobile work, I see CPOS as a practical tool for the right scale of business. Its best quality is not simply that a phone can read a card; it is that the phone can accompany the seller wherever the sale happens. That is valuable when hardware would be inconvenient, unnecessary, or easy to forget.
The main limitation is equally clear: the phone, battery, connection, and operator all become part of the payment terminal. If you prepare the device, test the network, avoid repeating uncertain transactions, and keep a backup method available, that arrangement can work very well. If you need a permanent, multi-user checkout system with minimal room for improvisation, a dedicated alternative will probably suit you better.
For my recommendation, I would start with a quiet test period rather than using it immediately at the busiest event of the month. Try the complete routine, including a weak-signal location, a connection change, and a failed attempt. The smartest way to use CPOS is to test the recovery process, not just the successful tap. If that workflow feels comfortable, this free business app offers a genuinely lightweight way to add card acceptance to a mobile operation.
In short, CPOS: Tap to Pay Card Reader is most compelling for people who want fewer devices and more freedom to take payments on the move. It does not eliminate the realities of connectivity, but it makes them manageable when the business owner plans around them. For a solo seller or occasional service provider, that balance can be exactly right.
FAQ
What is CPOS: Tap to Pay Card Reader?
CPOS: Tap to Pay Card Reader is a mobile point-of-sale solution designed to help businesses accept card payments using a compatible smartphone or tablet. Instead of requiring a traditional card terminal, the app can use supported contactless payment technology to process tap-to-pay transactions. It may also provide tools for managing sales, payment records, and basic checkout activity, depending on the account and service configuration.
Can I accept contactless payments without a separate card reader?
The main purpose of CPOS: Tap to Pay Card Reader is to support contactless card acceptance directly through a compatible mobile device, so a separate physical reader may not be necessary. However, this depends on your phone or tablet having the required NFC hardware, running a supported operating system, and meeting the provider’s security requirements. Availability can also vary by country, merchant account, and payment processor.
Which devices and operating systems are compatible with CPOS?
Compatibility should be checked before downloading because tap-to-pay applications normally require specific hardware and software conditions. Your device may need NFC support, an updated version of Android or iOS, screen-lock protection, and an approved security configuration. Some older phones, modified operating systems, tablets without NFC, or devices with unsupported regional settings may not work, even if the application installs successfully.
Is CPOS: Tap to Pay Card Reader safe for processing payments?
Payment applications such as CPOS generally use encrypted communication and industry security controls to protect transaction information, but the exact safeguards depend on the payment provider and account setup. You should download the app only from an official store, keep your device updated, use a strong screen lock, and avoid processing payments on rooted or jailbroken devices. Always review the provider’s privacy policy and merchant agreement.
Are there fees or account requirements for using CPOS?
Downloading CPOS may not be the same as using its payment service without cost. Merchants may need to create or connect an approved business account, complete identity verification, and accept transaction fees or other commercial charges. Pricing can depend on the payment processor, card type, location, settlement options, and optional features. Before relying on the app for daily sales, review the current terms and fee schedule.