BILL Spend & Expense (Divvy)
4.5BusinessUpdated October 2, 2026
Screenshots
Pros
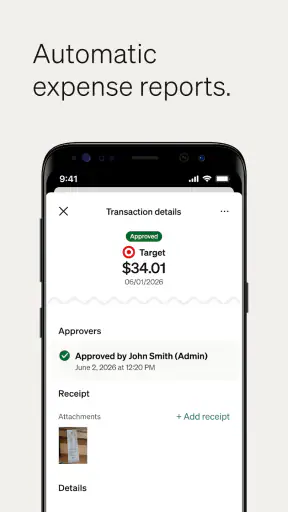
- Automates receipt capture and matches expenses to transactions.
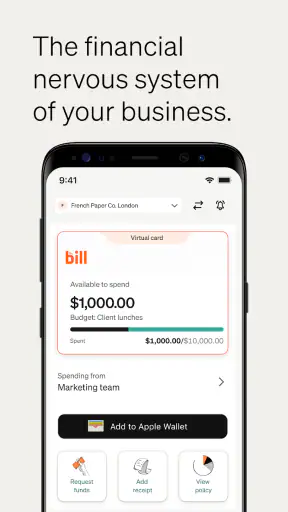
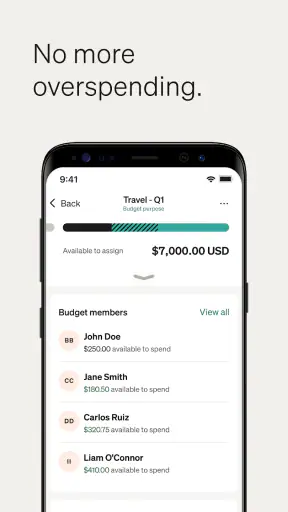
- Real-time spending visibility helps teams monitor budgets closely.
- Virtual cards can reduce fraud and simplify subscription management.
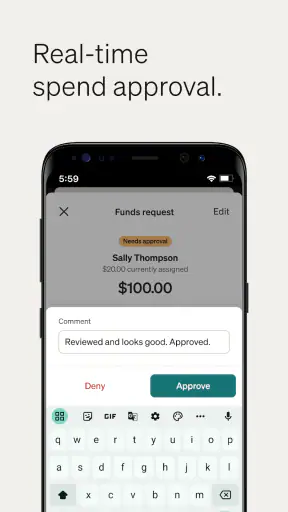
- Custom approval rules support different departments and spending policies.
- Integrates with popular accounting and business software platforms.
Cons
- Some advanced features may require higher-priced plans.
- Employees may need time to learn the approval and coding workflows.
- Requires reliable internet access for many real-time features.
- Limited usefulness for individuals managing only personal expenses.
- Bank and accounting integrations may need occasional reconnection.
 Analysis By Mobexer
I tested BILL Spend & Expense as a business finance app, and my first impression was that it is built for a very specific problem: giving a company a clearer way to manage corporate cards and employee spending from a phone. That sounds simple, but the usefulness becomes more apparent when several people spend money on behalf of the same business. Instead of treating every purchase as an isolated card transaction, the app is designed around the wider expense-management process.
BILL Spend & Expense is free to download, which makes it easy to evaluate without paying upfront for the app itself. It is developed by Bill.com Inc. and sits in the Business category. The store summary focuses on corporate cards and expense management, so I approached it less like a personal budgeting tool and more like a mobile companion for company spending workflows.
The app has an Everyone content rating and requires an operating system version of 12 or later. That matters for teams because compatibility is not just an individual concern: a company may have employees using a mixture of newer and older phones. Anyone considering a wider rollout should check the devices used by staff before assuming every employee can install it.
How BILL Spend & Expense fits into business spending
In everyday use, the main appeal is having corporate spending and expense follow-up connected in one place. A corporate card handles the payment, but the real administrative work begins afterward: identifying the purchase, attaching the right context, and making sure the expense can be reviewed properly. An app focused on both cards and expenses is intended to reduce that gap.
I find that distinction important because many alternatives solve only one side of the problem. A bank app may show transactions but leave employees and finance staff to handle explanations elsewhere. A receipt-scanning app may organize documentation but not provide the same card-centered view. A spreadsheet can be flexible, yet it depends heavily on people entering information consistently. BILL Spend & Expense is aimed at bringing those activities closer together.
A realistic example would be a small consulting team where one employee pays for a client meeting, another buys travel supplies, and a manager needs to review both purchases later. With a normal personal-card reimbursement process, the company may be waiting for messages, receipts, and manually completed forms. A corporate-card and expense workflow gives each purchase a clearer place in the company’s records, which can make the handoff from employee to reviewer less chaotic.
That does not mean the app removes the need for internal rules. A finance manager still needs to decide what counts as an acceptable expense, who reviews it, and how exceptions are handled. The app can support the process, but it cannot replace a sensible spending policy or a person willing to maintain it.
What the free download really means
The price point is one of the easiest reasons to try it: the app itself is free. I would still separate that fact from the total cost of adopting a corporate finance system. Free access to a mobile app does not automatically tell a business what its broader card program, account setup, or service arrangement may cost. Those are different questions, and a careful buyer should evaluate them separately rather than treating the download price as the complete purchasing decision.
For an individual user, free installation lowers the risk of testing the interface. For a company, the more relevant value question is whether the workflow saves enough administrative effort to justify adopting it across a team. That depends on the company’s existing process, number of cardholders, approval habits, and need for centralized oversight. I would not call it a free replacement for every finance system; I would call it a free entry point to assess whether this particular approach fits.
The app has a 4.5 average from around 4.3 thousand ratings, with 555 written reviews shown in the store. Those figures suggest that many users find the product useful, but they should not be mistaken for proof that it will suit every business. Finance tools are especially dependent on company structure. A workflow that feels efficient to a growing team can feel unnecessarily formal to a freelancer who only needs a simple record of personal business purchases.
Where the app can deliver practical value
The strongest value is organizational rather than flashy. When business spending is scattered across personal cards, email threads, paper receipts, and spreadsheets, even a modest improvement in consistency can help. A dedicated app gives employees a recognizable place to deal with company purchases and gives finance staff a more focused environment for checking them.
One non-obvious benefit is the change in timing. Expense administration is easier when handled close to the purchase instead of reconstructed at the end of the month. A team member who opens the app while the details are still fresh is less likely to forget why a charge occurred. That can reduce the vague descriptions that often force a manager to ask follow-up questions.
A second useful insight is that corporate-card management changes employee behavior. When spending is connected to a company-issued card rather than reimbursement from a personal account, the employee does not have to carry the same personal cash-flow burden. That can be meaningful for travel, project materials, or recurring work purchases. However, it also means the company needs clear boundaries, because convenience without clear responsibility can create confusion rather than control.
A third trade-off concerns visibility. Centralized expense information can help a manager spot unusual spending patterns earlier than a pile of reimbursement requests would. The same visibility may feel intrusive to employees if the company has not explained what is being reviewed and why. I would treat communication and policy as part of a successful rollout, not as an afterthought to installing the app.
The app is also potentially useful for reducing the number of tools employees must remember. If staff are already using one place for company card activity and expense follow-up, they may be less tempted to create their own parallel tracking systems. That can improve consistency, although it works only when the whole team actually adopts the same process.
Everyday workflow and small points of friction
My preferred way to use a tool like this is to make it part of the purchase routine rather than a month-end chore. After buying something for work, I would open the app, check the transaction, and add the relevant explanation while I still remember the client, project, or purpose. The exact internal steps will depend on how the business has configured its process, but the principle is straightforward: capture context early.
That habit also exposes a limitation. Mobile convenience cannot make every expense equally easy to classify. A purchase may serve two projects, include both business and personal items, or require a manager’s judgment. In those cases, an app can present the transaction neatly while the underlying decision remains complicated. Users should not expect a clean interface to eliminate ambiguous spending.
Another friction point is adoption. Finance staff may appreciate centralized records, while employees may see expense entry as extra work compared with simply swiping a card. The best results will come when the company explains what information is needed and keeps the process proportionate to the purchase. Requiring excessive detail for every minor transaction can make any expense tool unpopular.
Device compatibility is another practical consideration. The current version is 4.0.17, and the minimum operating system is 12. A business with managed devices should test installation and sign-in on the actual phones used by employees, especially if the workforce includes older hardware. This is a small preparation step, but it prevents a rollout from failing for reasons unrelated to the app’s financial workflow.
How it compares with familiar alternatives
Compared with a spreadsheet, BILL Spend & Expense should be more natural for a team that needs employees to participate in the spending process from their phones. Spreadsheets remain attractive when a business wants total flexibility and already has disciplined bookkeeping habits. They become less comfortable when several people edit records, receipts arrive at different times, and managers need a consistent review routine.
Compared with a normal bank or card app, the emphasis here is broader than simply checking a balance or viewing a transaction list. A bank app is often excellent for monitoring account activity, but it may not be designed around the company’s internal expense workflow. BILL Spend & Expense makes more sense when the business wants card activity considered alongside employee accountability and expense administration.
Compared with a standalone receipt organizer, this app is more relevant to companies thinking about corporate spending as a managed process. A receipt tool may be the better answer for a solo worker who only wants to store documentation. I would choose the BILL approach when the company needs a shared structure around employee purchases, not merely a digital filing cabinet.
Compared with manual reimbursement, the biggest difference is timing and ownership. Reimbursement lets employees use their own cards, but it can delay repayment and create a paperwork trail that grows messy as the team expands. Corporate-card management can be cleaner for approved business spending, though it also places more responsibility on the company to control card use and review transactions promptly.
Who is likely to get the most from it?
I see the strongest fit for small and growing businesses that have moved beyond one person paying for everything but do not want expense administration to become a full-time burden. Teams with multiple cardholders, regular work purchases, or managers who need a clearer view of spending are the natural audience.
It may also suit companies where employees travel or buy materials on behalf of projects. The value is not just recording the final amount; it is creating a repeatable habit around company spending. If the business is already struggling with missing receipts, unclear descriptions, or delayed reimbursement requests, a dedicated mobile workflow is worth investigating.
The app has more than 100 thousand installs, which indicates that it has reached a meaningful business audience. I would still judge it by the fit of the workflow rather than popularity. A large established finance department with highly specialized accounting requirements may need a broader system and deeper integrations than a mobile-first expense tool can provide. In that situation, this app could be useful for cardholders while another platform remains the central accounting system, but the company should confirm that arrangement before committing.
It is less compelling for someone who only wants personal budgeting. The corporate-card focus makes it feel unnecessarily structured for tracking household spending, splitting restaurant bills, or monitoring a single personal bank account. A consumer budgeting app would usually be a more direct choice for those needs.
Who should think twice before choosing it?
I would hesitate if a business has no appetite for changing its expense habits. Installing the app without defining who reviews transactions, how quickly employees should add context, and what happens when a purchase breaks policy will not solve the underlying disorder. In that situation, the company may simply create another place where incomplete information accumulates.
I would also be cautious for a very small operation with only occasional business purchases. If one owner makes nearly every purchase and already keeps accurate records, a spreadsheet or existing banking tools may be faster and easier. The value of centralized card and expense management grows with coordination needs; it is not automatically better just because it is more specialized.
Employees who use older phones should check the operating-system requirement before planning a rollout. Likewise, anyone expecting the app alone to perform full bookkeeping should set expectations carefully. Its clear identity is business spending and expense management, not a promise that every accounting, payroll, tax, or procurement task belongs inside the same mobile experience.
My final view on value
After looking at the app as a business user, I think BILL Spend & Expense is most convincing when the problem is scattered corporate spending. Its free download makes evaluation straightforward, and the combination of corporate cards with expense management gives it a more purposeful role than a basic transaction viewer. The strongest argument is practical: it can help a team capture spending context closer to the moment of purchase and give managers a more consistent review process.
The important qualification is that free access to the app is not the same as a complete statement about the cost of a company-wide financial program. Businesses should assess the wider arrangement, their existing tools, and the work required to train employees. The app’s value comes from reducing friction and improving visibility, but those gains depend on people using it consistently.
My recommendation is to try it if your business has several people spending company money and your current process relies on scattered receipts, messages, or spreadsheets. I would skip it for personal budgeting, very occasional business purchases, or a company that needs a full accounting platform rather than a focused expense companion. For the right team, BILL Spend & Expense can turn an untidy card-and-receipt routine into a more deliberate workflow. For everyone else, its corporate focus may be more structure than they actually need.
As a business app, it earns its place through organization rather than novelty. The developer, Bill.com Inc., has positioned it for a practical workplace problem, and the current release gives compatible users a reasonable way to explore that approach. My buy-or-skip verdict is therefore conditional but positive: choose it when shared corporate spending is the problem you are trying to fix, and compare simpler or broader alternatives when it is not.
FAQ
What is BILL Spend & Expense (Divvy), and who is it designed for?
BILL Spend & Expense, formerly known as Divvy, is a business expense management platform designed to help companies control spending, issue and manage corporate cards, create budgets, and track expenses. It is mainly intended for businesses, finance teams, managers, and employees who need a centralized way to handle purchases, receipts, approvals, reimbursements, and reporting rather than for personal budgeting.
Can employees use BILL Spend & Expense to make purchases and submit receipts?
Yes. Depending on the company’s account configuration, employees can use an assigned virtual or physical corporate card to make approved purchases and then record the transaction in the app. The platform can support receipt capture, expense details, notes, and categorization, helping finance teams review spending. Available actions may vary according to the employee’s permissions, company policy, card status, and the specific BILL subscription.
Does BILL Spend & Expense help businesses set budgets and control employee spending?
Budgeting and spending control are among the platform’s main features. Administrators can create spending limits, establish budgets for teams or projects, and apply approval rules before or after transactions. These controls can make company spending more visible and reduce unauthorized purchases. However, the exact controls available to your organization depend on its configuration, account plan, user roles, and internal approval policies.
Is BILL Spend & Expense free to download and use?
The mobile application may be available to download without an upfront charge, but BILL Spend & Expense is primarily a business service rather than a completely free personal finance app. Companies generally need an eligible BILL account, and pricing, card costs, service fees, or feature availability can depend on the selected plan and agreement. Check the official BILL website or your administrator for current pricing and eligibility details.
What should I check before downloading and signing in to the app?
Before downloading BILL Spend & Expense, confirm that your company uses the service and that an administrator has invited or authorized you. You may need valid work credentials, a supported device, internet access, and permission to use features such as camera access for receipt capture or notifications for transaction updates. Also review your organization’s privacy, card, reimbursement, and expense-submission policies before using the app.