BILL AP & AR Business Payments
4.3BusinessUpdated October 2, 2026
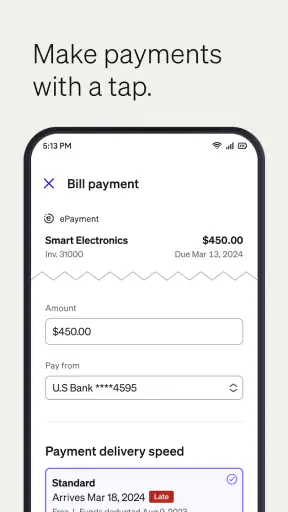
Screenshots
Pros
- Streamlines invoice collection and payment tracking in one place.
- Supports faster reconciliation with organized transaction records.
- Helps reduce manual follow-ups through payment status visibility.
- Useful for businesses managing recurring accounts receivable workflows.
- Can improve cash-flow awareness with centralized payment information.
Cons
- May require setup time before payment workflows run smoothly.
- Advanced features may depend on your subscription or business plan.
- Not ideal for users seeking a simple personal bill-payment app.
- Compatibility with existing accounting tools may vary by setup.
- Business data requires careful access control and security management.
 Analysis By Mobexer
I look at BILL AP & AR as a practical business payments app rather than a complete accounting system. Its purpose is straightforward: help businesses pay bills and manage incoming payments online from a mobile device. That focus makes it interesting for owners, operators, and finance staff who need access away from a desk, but it also means the app deserves a careful look before becoming part of a payment routine.
In my experience, financial apps should be judged by more than convenience. I want to know whether the workflow is understandable, whether I can review an action before committing to it, and whether the account gives me enough control over sensitive activity. BILL AP & AR is developed by Bill.com Inc. and sits in the Business category, with a free download and an Everyone age rating. Those details make it approachable, but they do not remove the need for sensible internal checks.
The app has been available since December 16, 2015, and its current version is 3.7.171. It requires iOS 9 or later, which is useful for people maintaining an older compatible device. Its public reception is also reasonably strong: it holds a 4.3 average from around 7,500 ratings, with roughly 1,500 written reviews and over 500,000 installs. I read that as evidence of meaningful use, not as a guarantee that every business will find the same experience smooth.
How BILL AP & AR fits a careful payment workflow
A mobile companion for accounts payable and receivable
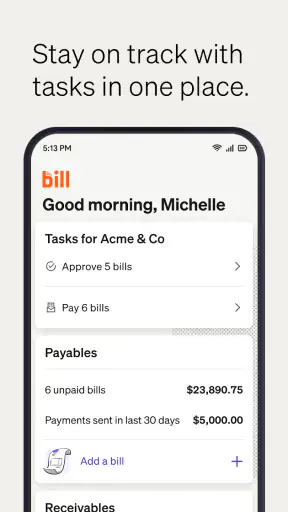
The short label “BILL AP & AR” tells me where the app belongs: accounts payable and accounts receivable. In plain language, that means it is aimed at the two sides of business cash movement. One side involves bills a company needs to settle; the other involves money the company expects to receive. Keeping both ideas close together can be helpful when a small team is watching outgoing obligations while also following up on incoming funds.
I would not treat it as a replacement for every finance tool a company may already use. A bookkeeper may still need broader accounting software, a bank’s own controls, or a separate document-retention process. The value here is the ability to interact with the BILL workflow from a mobile setting. That is especially relevant when the person responsible for payments is traveling, working from a shared office, or handling approvals between meetings.
A realistic example is a small design studio whose owner is away from the office when a supplier invoice needs attention. Instead of waiting until the end of the day to return to a computer, the owner can open the business payment workflow, review what is waiting, and decide what should happen next. The useful part is not simply saving a few minutes. It is keeping payment work visible while the business is moving, provided the owner has enough information to make a responsible decision.
Where it is more useful than ordinary email and banking apps
Email alone is a poor place to manage payment responsibility. Messages can be buried, attachments can be separated from conversations, and it is easy to lose track of whether a bill was merely discussed or actually handled. A banking app is also not the same thing as a bill-management workspace. It may show transactions, but it usually does not organize the surrounding business process in the same way.
BILL AP & AR is more relevant when the task begins with a business obligation rather than a bank balance. That distinction matters. If I only need to check whether money left an account, I would probably open the bank app. If I need to work through business payment activity, the BILL environment is the more natural place to start.
The trade-off is that another system means another account, another workflow to learn, and another place where the business must maintain accurate information. A company that already has a reliable process and rarely needs mobile access may gain little from adding this app. The strongest case is for teams that want their payment work available outside a traditional desktop routine.
What I would check before inviting a team member
Before using the app with other people, I would decide exactly who should be allowed to view, prepare, review, or act on payment-related work. I would not assume that every employee needs the same level of access. A person who collects invoice details does not automatically need the ability to approve an outgoing payment, and someone who watches incoming funds may not need access to every payable item.
This is one of the most important practical insights with a business payments app: mobile convenience should not become automatic authority. The smaller the company, the more tempting it can be to share one login or let everyone use the owner’s device. I would avoid that approach. Individual account controls, where available in the organization’s setup, are easier to review than a shared credential, and they make responsibility clearer when something needs investigating.
Reviewing sensitive activity without rushing
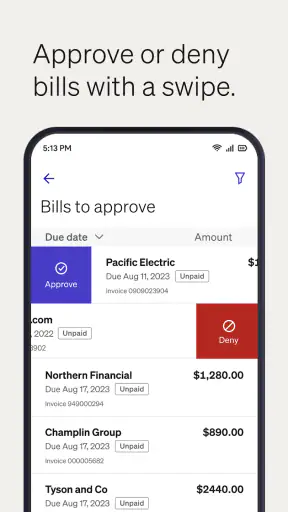
Payment actions deserve a slower rhythm than ordinary mobile tasks. A small screen can encourage quick taps, especially when someone is trying to clear a queue between other jobs. My preferred habit would be to open each item, confirm the business name, amount, timing, and supporting context, and only then continue. I would also avoid approving anything while distracted or using an unfamiliar network or device.
This is not a criticism unique to BILL AP & AR. It is a general risk of moving financial work onto a phone. The app can make access easier, but easier access can also make impulsive decisions easier. For that reason, I see the app as most trustworthy when it supports a deliberate company process rather than replacing one.
Account controls and visible choices
When I assess a financial app, I pay attention to the choices visible during account use: what I can review before an action, whether the current account or business context is clear, and whether I can tell what stage a task has reached. These details matter because payment mistakes are often caused by confusion rather than bad intent.
I would take time to inspect the account area before processing real work. I want to know how the app presents sign-in details, business identity, notifications, and any available security settings. I would also check whether the device is shared and whether its screen lock is enabled. Those are simple controls, but they are part of the trust picture and do not depend on assuming anything about the app beyond what is visibly offered.
For a business owner, the practical question is not “Can I use this from anywhere?” It is “Can I use this from somewhere else without losing the same level of review?” If the mobile layout hides context that is easy to see on a desktop, I would reserve final decisions for the larger interface. If the relevant details remain clear, mobile access becomes much more useful.
Data-sensitive moments in everyday use
Accounts payable and receivable naturally involve sensitive business information. Bills may reveal supplier relationships, amounts, schedules, and internal contacts. Incoming payment work can expose customer details and the financial expectations attached to an invoice. I would therefore treat every notification, screenshot, exported document, and shared device as part of the information-handling process.
A useful habit is to keep notifications as discreet as the app allows, particularly on a phone that may sit on a reception desk or be visible during meetings. I would also avoid sending payment screenshots through casual messaging channels unless the recipient genuinely needs them. The app may be convenient, but the surrounding phone environment can still expose information through previews, backups, or accidental sharing.
I would pay attention to the permissions shown during installation and later use, granting only what is necessary for the task at hand. I would not infer safety from the app’s business category or Everyone rating, and I would not treat a free price as evidence that there are no broader account or service considerations. The responsible approach is to read the permission prompts and privacy choices presented on the device, then revisit them if the workflow changes.
Another non-obvious point is device turnover. When an employee leaves or replaces a phone, the company should not simply hand the old device to someone else with the app still signed in. The account should be reviewed, access should be removed or updated through the organization’s controls, and the device should be cleared according to company policy. That procedure protects the business even when the app itself is working normally.
Handling approvals in a small company
Small businesses often combine roles. The person who receives an invoice may also prepare it, and the owner may be the final decision-maker. That can make mobile approval attractive, but it also creates a separation-of-duties problem. If one person can enter, change, and approve the same payment without another review, an accidental error has fewer chances to be caught.
I would use BILL AP & AR alongside a simple internal rule: the person who prepares a payment should not be the only person who verifies its key details when another responsible person is available. Even a short confirmation through an established company channel can help. The app should support the business process, not become the entire process.
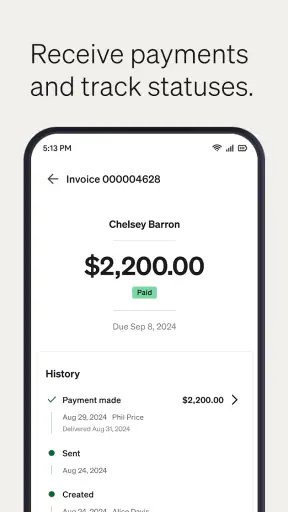
For incoming payments, I would reconcile what appears in the app with the company’s own records rather than assuming that an item is complete simply because it is visible. A payment workflow can show activity, but the business still needs a consistent way to match invoices, customer communication, and bank records. This is where a dedicated accounting system or bookkeeper may be better suited to the deeper reconciliation work.
Who will appreciate it most
I think the app is best suited to small and growing businesses that already use BILL’s payment environment and want a mobile way to stay involved. Owners who approve bills, operations managers who monitor obligations, and finance staff who need access while away from a workstation are the clearest audience.
It can also suit a distributed team, but only if the company has already agreed on roles and review habits. A mobile tool is more helpful when everyone knows what “ready,” “reviewed,” and “completed” mean in their own process. Without that shared understanding, a clean interface cannot prevent duplicate work or unclear responsibility.
I would be more cautious about recommending it to someone who only wants a personal bill reminder, a basic budgeting tool, or a simple way to pay household expenses. The business orientation is important. Likewise, a company that needs advanced accounting analysis, detailed inventory work, payroll management, or a large custom approval structure should compare it with a broader financial platform before deciding.
What may feel limiting
The focused design can be a strength, but it can also feel narrow. People expecting a full accounting dashboard may find that a payment-centered app does not answer every financial question. Mobile screens are also not ideal for reviewing long documents or comparing many items side by side. I would use a desktop workflow when the decision requires extensive reading, multiple reconciliations, or careful comparison across records.
There is also a human limitation: the app makes business activity more accessible, but it cannot decide whether a supplier request is genuine or whether a payment change is suspicious. If an invoice suddenly contains different bank details, I would verify that change through a trusted, separate contact method rather than relying on the document or a message inside the workflow. This kind of independent check is especially important when the app makes it easy to act quickly.
Compatibility is another practical point. The app requires iOS 9 or later, so anyone using an older Apple device should check the operating system before planning a rollout. A company should also test its actual phones, account setup, and day-to-day approval routine before depending on mobile access during a busy period.
My approach to trust and user control
I do not judge BILL AP & AR as trustworthy merely because it has a solid public rating or a substantial install base. Those signals tell me that many people use it, but trust comes from how carefully the business operates it. I would review the app’s visible account options, permission requests, notifications, and sign-in behavior on the devices that will actually be used.
I would also make sure users know how to stop and ask for help. A good internal rule is that an unexpected payment request, changed recipient detail, or unclear approval status should remain pending until someone verifies it. That gives users agency instead of pressuring them to complete a task simply because it appears in a queue.
The free price makes trying the app less intimidating, and the Everyone rating makes it broadly approachable from an age-classification perspective. Still, business suitability depends on the organization’s needs, controls, and willingness to maintain accurate records. I would start with a limited workflow, observe where users hesitate, and only then expand its role.
My cautious recommendation
After looking at BILL AP & AR as a mobile business payments tool, I see a useful companion for people who need to stay close to accounts payable and receivable without being tied to a desk. Its strongest quality is focus: it is designed around business payment activity rather than personal budgeting or general banking.
I would recommend it to a small business that already has a clear approval process and wants convenient mobile access. I would not recommend treating it as the sole safeguard for payments, replacing accounting oversight, or sharing one account among several people. The best results come when the app is paired with separate responsibilities, careful verification, and sensible device security.
My final view is positive but measured. BILL AP & AR can make payment work easier to reach, and its established presence, free availability, and business-specific purpose make it worth considering. Before relying on it, I would test the exact workflow, inspect every visible control, and decide who can do what. If your priority is convenient access with deliberate human review, it is a sensible option; if you need a complete finance suite or minimal process discipline, look elsewhere.
FAQ
What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is a business finance platform designed to help companies manage accounts payable and accounts receivable in one place. It can be used to pay vendors, send invoices, receive customer payments, schedule transactions, and keep payment records organized. It is mainly intended for businesses and accounting teams rather than personal everyday banking.
Can small businesses use BILL AP & AR Business Payments?
Yes, the platform is suitable for many small and growing businesses, especially those that want to reduce manual payment and invoicing work. It can help owners, bookkeepers, and finance teams centralize bills, approvals, invoices, and payment tracking. However, the available tools, user permissions, pricing, and transaction limits may depend on the selected BILL plan and the company’s location.
Is BILL AP & AR Business Payments safe for handling business transactions?
BILL includes security features intended to protect business payment information, account access, and transaction activity. Depending on the account setup, users may have access to approval workflows, permission controls, authentication features, and payment monitoring. Even so, businesses should use strong passwords, limit employee access, verify vendor details carefully, and review every payment before approval to reduce the risk of fraud or mistakes.
Does BILL AP & AR Business Payments connect with accounting software?
One of the platform’s main advantages is its ability to work alongside business accounting workflows. BILL supports integrations with popular accounting systems and can help synchronize bills, invoices, vendors, payments, and related financial information. Before downloading or subscribing, it is worth checking whether your specific accounting software, version, and plan are supported, because integration features can vary by product and subscription level.
Are there fees for using BILL AP & AR Business Payments?
BILL is not necessarily a completely free service. Costs may vary according to the chosen product, subscription plan, payment method, transaction type, and optional features. Some services may include processing or expedited payment fees, while certain plans may charge recurring amounts. Businesses should review the current pricing page and applicable terms before signing up, particularly if they expect to process a high volume of payments.